Investment Trust Dividends
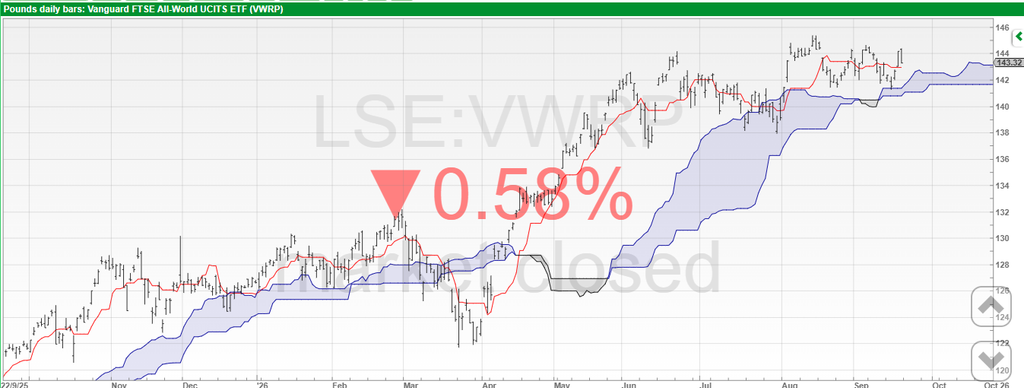
When the price is above the cloud, the sun is shining on your share.
When the price is below the cloud, the market is raining on your share parade.
When the price is in the cloud, the direction of the price is the known unknown.
The current trend is in place but may be showing signs of weakening.
The SNOWBALL earned income of £13,160. This is currently being re-invested but if you spent your dividends that equates to a yield of around 13%.
The equivalent sum for an annuity would be around 7% and you have to surrender all your capital.
The comparator share VWRP using the 4% rule would provide income of £6,873. The gap will continue to grow as the earned dividends are re-invested.
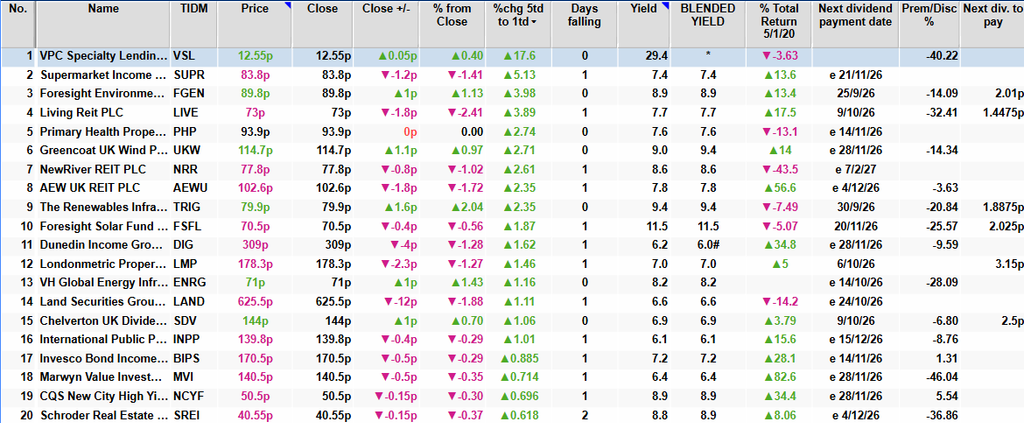
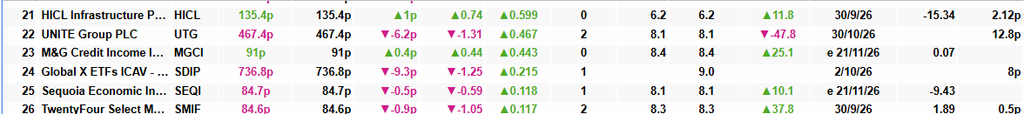
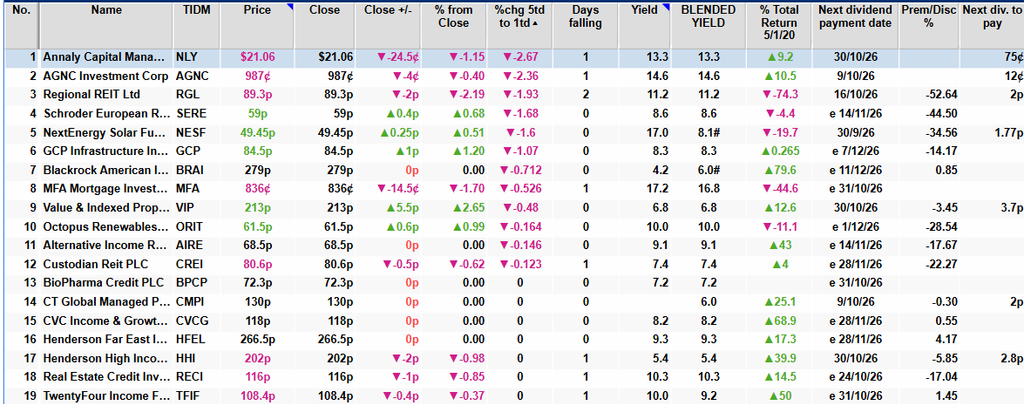
Those on a six-year run also include the 6.6% yielding property firm Land Securities Group LAND
Among other popular sectors for income investors, the 7.2% yield of LondonMetric Propert LMP
represents the current pick of the property space.
The urban logistics-focused REIT has increased its dividend per share for 11 years running, including by 3.8% to 12.45p for the 2025/26 year.
Chief executive Andrew Jones recently said the company was a step closer to its ambition of “dividend aristocracy” – representing 25 consecutive years of growth.
He added: “We are grounded in the belief that income compounding is one of the true wonders of investing – the essential ingredient and rocket fuel of long-term wealth creation.”
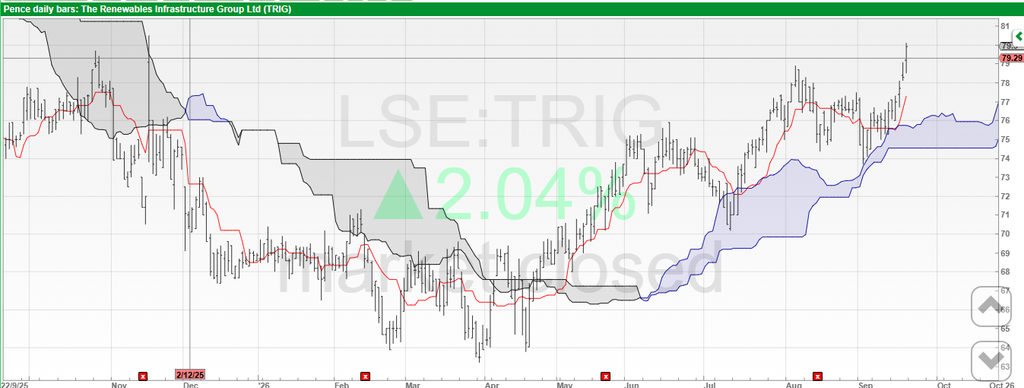
I’ve booked a further profit with TRIG of £400, total profit now £893.00. Remember that Mr. Market could take back all the profit and some, whilst the share is still in the SNOWBALL.
Current yield 9.6%, so remains a strong hold, until it isn’t.
VPC Specialty Lending Investments PLC
PORTFOLIO UPDATE
The Board of Directors of VPC Specialty Lending Investments PLC (the “Company“) is pleased to announce that the largest debt position in the portfolio, Essor Group, Inc. (“Heyday“), has been repaid at its carrying value in the last published NAV as at 30 June 2026 plus all outstanding interest. Accordingly, the Company has received approximately £9.3 million and the Board intends to distribute substantially all the Heyday proceeds to the Company’s shareholders as soon as practicable. Given the Company has insufficient distributable reserves to return this capital through the operation of the Company’s B share mechanism, the Board is exploring with its advisers alternative means of making a distribution to the Company’s shareholders and expects to make a further announcement in due course.
Real Estate Credit Investments Limited (the “Company”)
Ordinary Dividend for RECI LN (Ordinary shares)
Real Estate Credit Investments Limited announces today that it has declared a first interim dividend of 3.0 pence per Ordinary Share for the year ending 31 March 2027. The dividend is to be paid on 16 October 2026 to Ordinary Shareholders on the register at the close of business on 25 September 2026. The ex-dividend date is 24 September 2026.
It’s your duty to check the dividend announcements for your Snowball.
Supermarket Income REIT (SUPR) shares have re-rated in response to the strategic “transformation” made since the start of last year, the company said in annual results today. Shares in the £1.1bn real estate investment trust rose 1.8% to 84p, narrowing the gap to net tangible assets (NTA) of 87.5p per share to 4%. That compares to a 15% discount in March last year when the shares stood at 75p compared to NTA of 88p. Internalising fund management had cut the cost ratio from 13% to 9.2% in the year to 30 June, releasing more money for dividends that are set to grow by at least 2% a year from 2027, helped by a portfolio enlarged by the expanded joint venture with Blue Owl and a £100m equity raise this summer. For the latest year dividends rose 1% from 6.1p to 6.2p per share, with cover for the pay-out falling to 93% from 98% as refinancing costs temporarily knocked earnings per share by 4.1% to 5.7p from 6p last year. The shares yield 7.4%.
Matthew Read said: “Supermarket Income REIT has undergone considerable change over the past 18 months and these results demonstrate the scale of its ambitions. The portfolio has grown to £2bn, the Blue Owl joint venture has expanded rapidly and costs continue to fall, with the EPRA cost ratio down to 9.2%. With the proceeds of July’s equity raise already deployed, SUPR needs to show that it can convert this growth into higher earnings and deliver on its commitment to increase the dividend by at least 2% a year. The grocery property market remains supportive and SUPR appears to have plenty of opportunities to grow within it.”
© 2026 Passive Income Live
Theme by Anders Noren — Up ↑