A retirement plan without an end destination, is better than no plan but it isn’t a good plan.
The SNOWBALL has a comparator share VWRP. We can use this share to compare your options at your planned retirement date.
There are three options with the above when you retire.
A. You can use your fund to buy an annuity
B. Use the 4% rule
C. A combination of both.
A. Would provide income of around £11,500 age dependant but you would have to surrender all your capital so not a viable option.
B. Would currently provide income of £6,616
The SNOWBALL will earn 13% of interest on capital invested > 13k.
Now VWRP is back to the price it was in May of this year, so it hasn’t provided any cash to your retirement pot.
During this period the SNOWBALL has earned just over 6.5k of dividend income
This has been re-invested at a blended yield of 8%, providing another £500 of income for 2027
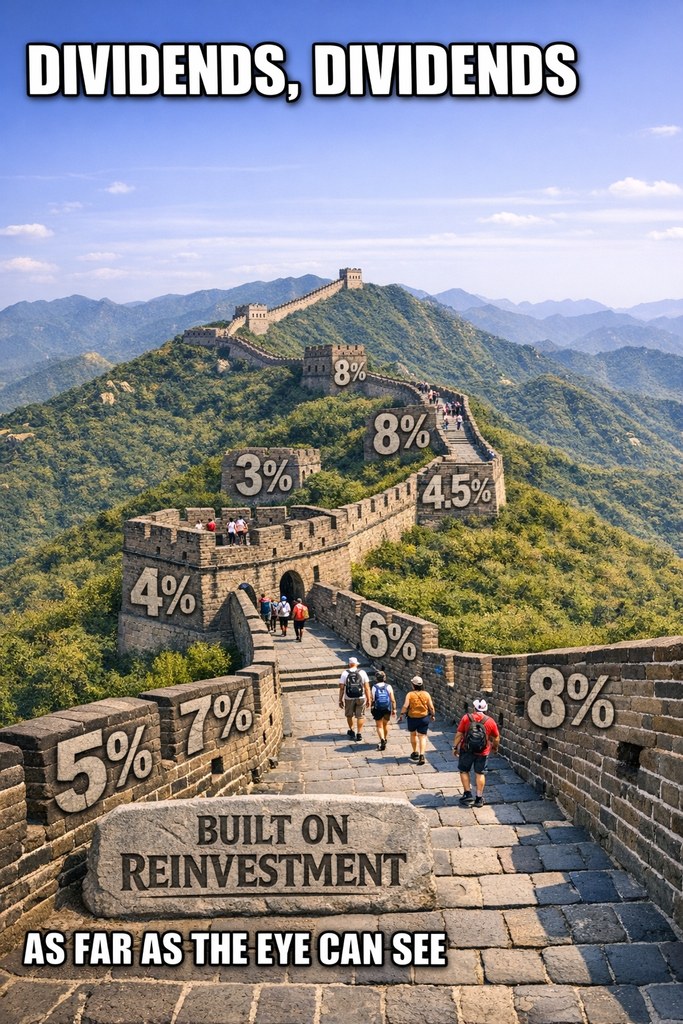
If you have 30 years to retirement, £500 compounded at 8% would compound by 10 ten times, so income of 5k at retirement.
You have to allow for inflation but if you have 30 years to retirement you would have 60 times of the figure above. Obviously the amount changes if you have less years to retirement. Better if in a tax free wrapper.
To earn 8% compounded used to mean buying and holding a share similar to Coca Cola and then wait for compound interest to work its magic. Now with ETF’s and the market selling off Renewable Trusts and Property Trusts, it currently achievable without taking on to much risk.
Leave a Reply