Passive Income Live

Investment Trust Dividends

Page 151 of 453

Over the channel

Continental drift

Are the US and Europe drifting apart?

Alan Ray

Kepler

Disclaimer

This is not substantive investment research or a research recommendation, as it does not constitute substantive research or analysis. This material should be considered as general market commentary.

There have been some fascinating twists and turns in the last 12 months’ journey through the investment landscape, the rising price of gold, China’s equity market surge, and the bond market’s rebuke to the US administration being three that have attracted plenty of headlines. It would be an exaggeration to say that the interplay between the US and Europe has been less well covered, with the game of golf taking on an internationally significant role, but perhaps less so in terms of the interplay between US and European equities, which has quietly been one of the big themes of 2025. At the time of writing, the S&P 500 is up year-to-date by about 7% for a GBP investor compared to about 14% for European markets. Given the huge resurgence of the US market since April, one could be forgiven for not knowing these figures, and they certainly surprised us.

This difference is exacerbated by the polarisation in the S&P 500, where active managers are either long of the Magnificent Seven or are underperforming. In Europe, conversely, owning the GRANOLAS, a set of large-cap growth companies analogous to the Magnificent Seven, has been the wrong strategy, with a resurgence in more domestically orientated stocks, which some active managers have been quick to pick up on. Europe’s equity market resurgence does seem to be partly powered by positive fund flows coming from global investors lightening up on the US, and thus it feels right to ask whether the two continents have drifted apart, or is this just a cyclical phase? Let’s start by taking a short journey back in time and remind ourselves of how, perhaps only two years ago, we would have defined the US and Europe from a big picture investment perspective.

The US is a continental-sized economy united by a single language and with an abundance of natural resources. Its culture favours hard work and innovation. Further, it has an as-yet-unparalleled industrial military complex. Many individuals are directly connected to the equity markets through their savings and are acutely aware of the direction of the S&P 500. The country has an outstanding track record of growing world-leading companies that dominate or even monopolise their niche, as well as some outstanding domestic businesses that, although defined as ‘small cap’, would in any other country be a mid or large cap. Considering the US is a highly developed economy, it maintains a GDP growth rate that other developed economies just can’t seem to match. All of this combines to make the US ‘exceptional’.

Europe, by contrast, has a similar-sized population divided by several languages, borders, and varying political systems. Europeans are hard-working too, but take more holidays. Many Europeans are not very aware of stock markets, and they typically save through products where the links to stock and bond markets are opaque. Europe is innovative too, but often lacks the corporate ambition of the US, with companies often sold at an earlier stage. Far from being exceptional, Europe is seen as being a bit old and tired and probably too dependent on the US for its influence in the world.

Putting it more simply, let’s imagine that Jeff Bezos had started his business in a European country. Would Amazon be what it is today, or would Jeff have been happy running a successful online bookstore? Perhaps to be bought out by one of the traditional retailers after a few years.

All of this adds up to an investment mindset for many of us, myself included, that means we invest in US equities partly because, well, it’s the US and you just have to, right? Whereas Europe doesn’t seem all that essential. But, well, we ought to have a bit there just in case. After all, Europe is big and old enough that it’s bound to have grown a few large successful global companies. More recently, as Europe’s largest companies got their own acronym and it seemed like Europe was finally about more than just expensive handbags, investors did start to take more of an interest, and a very similar pattern of very narrow market leadership developed, with Europe’s ‘global champions’ a.k.a. the GRANOLAS, being the essential ingredient in any portfolio.

In 2025, something very interesting happened, though. In Europe, those ‘global champions’ have not performed well, and instead, more domestically orientated stocks have been doing the driving. For example, banks, which many active fund managers shy away from, have been a standout sector. Engineering and construction companies have seen their share prices run up in anticipation of the German government’s infrastructure spending, and Europe seems genuinely determined to build up its domestic defence industry. For the first time in a long time, European equities have risen because of Europe, rather than in spite of Europe, and it is perhaps no surprise that, in the short term, not all active managers have navigated this. It’s hard to be optimistic about Europe after a career when it has paid not to be. Japanese equity fund managers probably feel the same way.

Some active managers have adapted rapidly, though, and one trust which we think has done an outstanding job is JPMorgan European Growth & Income (JEGI). This trust aims to be an all-weather core holding in Europe and also pays a dividend partly funded from capital, which provides a yield on an asset class that income investors might otherwise be prevented from owning. You can read about why capital dividends can be a very good thing indeed here. The team managing JEGI correctly identified the momentum building behind banks, for example, as well as anticipating the momentum going out of some of those global champions and have significantly outperformed the market as a result, extending a very good long-term track record.

Another very successful strategy in Europe is the succinctly named European Smaller Companies (ESCT). As we noted above, the swing factor for investors shifting allocation to Europe has been a slightly better economic outlook for domestic economies. This has been incredibly helpful for ESCT’s portfolio of mid and smaller companies, where again, we see performance coming from domestic areas such as construction and engineering and defence. We also observe that ESCT has been the subject of more corporate activity in the last year than most investment trusts see in a decade. First, for baffling reasons given its performance track record, ESCT was strong-armed into a tender offer by an activist investor, but then, in recognition of that same track record, became the merger host for one of its peers, European Assets (EAT). In so doing, ESCT has also adopted a capital dividend policy and thus income investors have been given yet another extremely useful tool.

This surge in more domestically orientated stocks has led to others in the peer group underperforming slightly. The largest trust in the group, Fidelity European (FEV), has an outstanding long-term track record, but over the last year has just missed the benchmark. Others, such as Baillie Gifford European Growth (BGEU), BlackRock Greater European (BRGE), and European Opportunities (EOT) have been caught on the same side of the trade. This is, though, a short period of time, and as we’ll look at further on, has Europe really changed all that much? It seems likely that first, active managers will adapt, but second, perhaps it’s also good to reflect that some of those global businesses that have performed less well this year are successful for a reason.

In the US, the polarisation between the Magnificent Seven and ‘the other 493’ (constituents of the S&P500) is well known, and the investment stalwart JPMorgan American (JAM) has done an exceptionally good job of outperforming the index over the last five years, without relying on full Magnificent Seven exposure. We think this is what an investor in a core product should be looking for, and while JAM has trailed the index in the nine months elapsed in 2025, in our opinion it’s a relatively small price to pay for the lower volatility and outperformance it has delivered over five years. A less commented upon divergence in the US market is the underperformance of small caps as an asset class, and while this has persisted for several years, this year’s strong bounce back by the S&P 500 after April’s sharp falls was not matched by small caps, which broadly speaking fell at the same time but failed to bounce.

Again, while corporate activity in investment trusts isn’t always timed as an exact contrarian signal, it’s interesting that, for example, Brown Advisory US Smaller Companies (BASC) very recently introduced a conditional tender offer linking performance to an opportunity for investors to get up to 100% of their money back. BASC’s closest peer, JPMorgan US Smaller Companies (JUSC), did hold a tender offer in 2024, and while this was likely driven by activist investor Saba, it’s still a signal that other investors have lost interest in US smaller companies. Contrarian signals like this are, if nothing else, good prompts to re-examine an asset class. Both these trusts’ managers have really good long-term track records investing in the quality growth domestic businesses that are at the core of the US small-cap universe, and which have not been rewarded by investors at all for quietly compounding, while a few mega-cap stocks undergo explosive growth phases that may, or may not, prove to be rooted in long-term reality. US small caps have had such a tough time getting attention from stock market investors for a long time now that anyone with an ounce of contrarianism ought to be looking more closely.

In a similar vein, North American Income (NAIT) offers investors a real alternative to the concentrated performance of the index and could be, as the name implies, a very good option for income investors otherwise put off by the US’s relatively low dividend yield. Although not its intention, we can see this trust as a natural diversifier from the Magnificent Seven-led index.

A permanent change?

With the polarisation in investment trust performance discussed above seemingly driven by that switch in the fortunes of Europe and the US in investors’ minds, it’s fair to ask whether this really is a case of continents drifting apart, or something more cyclical? Uncomfortable scenes at golf clubs on both sides of the Atlantic this year are representative of a strained relationship between the US and Europe, but perhaps also serve as a reminder of the incredible importance of the relationship between the two. One conclusion we might reach from the last year as investors is that there has been an irreversible shift in the balance. Before, we invested in US equities because of the US, and in European equities, in spite of Europe. Every day that the gold price goes up and the dollar goes down helps confirm this year’s narrative that the rest of the world is seeking to diversify its investment exposure. And now, we are investing in Europe as an ‘improver’ and being more selective about our investments in the US, focussing on its ‘global champions’ that are less reliant on its domestic economy. If true, that’s quite the reversal.

If, on the other hand, we had a slightly contrary streak, we could look at it differently. The shift is real enough. Given the polarising nature of the current US administration, it’s incredibly difficult to compose short sentences that don’t imply some bias, so we’re going to trust our readers to see the next statement as a non-partisan comment. As a dispassionate investor, it is important to acknowledge that it is very likely true that, on average, a negative perception among global investors is an important part of the shift. But perhaps the sheer volume of noise generated means that it’s easy to miss, for example, that the US has made some extremely positive pro-business revisions to the tax system that will encourage more investment.

In contrast, what is driving optimism in Europe? German infrastructure spending is often cited as one of the swing factors, and it’s true that Germany’s very conservative balance sheet does allow it to borrow more to fund this. But infrastructure in democratic countries is notoriously difficult to do at scale, and we don’t think it’s too cynical to point out that politicians’ plans often include previously announced spending to make up the total. Europe’s new determination to spend more on defence is also cited as a positive factor for markets, and while it does seem likely there will be an increase, one can easily imagine there will be wavering once it becomes clear that this comes at the cost of what? Spending on health care? Social care? These are highly prized parts of European society. In short, it’s not hard to see how backtracking from today’s very positive outlook could occur.

Make no mistake, though. A lot of capital has flowed into Europe, and it’s hard to dismiss it all as ‘hot money’ seeking a quick, safe haven from an, ahem, non-conformist US administration. We think European equities deserve to be pushed up the rankings in terms of the attention they receive. But are we really so confident that those two opening descriptions of the US and Europe have changed all that much? It’s a strange world indeed when US equities might be the biggest contrarian bet in global markets, but that’s the world we find ourselves in.
DYOR Kepler

We look at the performance of global equity trusts year-to-date.

Jean-Baptiste Andrieux

Updated 22 Oct 2025

Disclaimer

This is not substantive investment research or a research recommendation, as it does not constitute substantive research or analysis. This material should be considered as general market commentary.

Some figures seem untouchable, no matter how dire the circumstances. Take Tintin, for example, who always emerges unscathed from the most desperate moments — whether escaping assassination attempts by Chicago mobsters, dodging the imperial Japanese army, or returning from space in a rocket running low on oxygen.

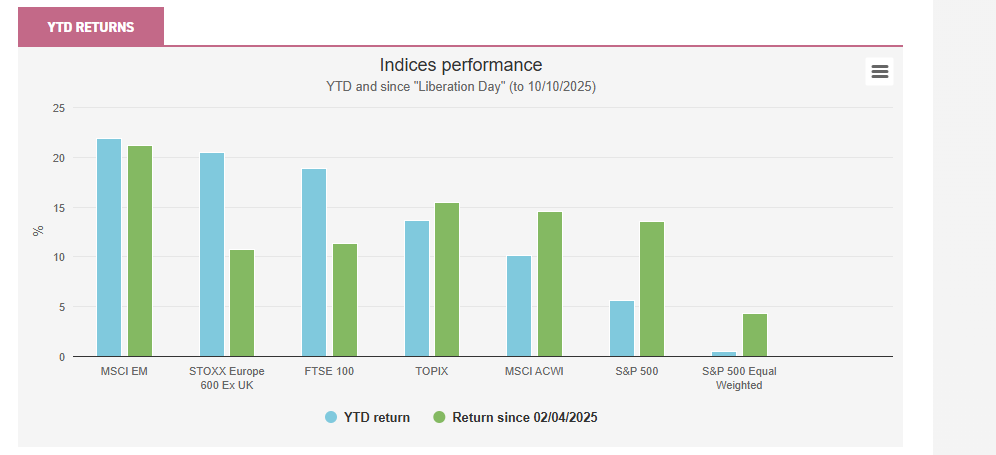
Arguably, a similar resilience can be observed in the US mega cap stocks linked to artificial intelligence (AI), that appear to withstand almost anything thrown their way. These stocks have faced numerous headwinds this year, particularly from escalating trade tensions between the US and the rest of the world. The situation reached a climax on Liberation Day (02/04/2025), when Donald Trump announced higher tariffs against most countries. This triggered a broad market sell-off as investors feared the economic fallout of these tariffs. Yet, much like Tintin’s knack for landing on his feet, AI-related stocks bounced back once tariffs were paused and reduced, further supported by robust second-quarter earnings from US companies. That said, it is worth noting that the US dollar has weakened over the period, negatively impacting returns for GBP investors.

As a result, while the S&P 500 index has lagged European and UK equities (in GBP terms) since the start of the year (to 10/10/2025), some US AI-related companies, such as NVIDIA and Broadcom, have delivered superior returns. In fact, it is worth noting that the equal-weighted version of the S&P 500 has largely underperformed the market-cap weighted version, suggesting that gains in the US equity market have been driven primarily by its largest constituents, many of which are linked to the AI theme.

YTD RETURNS

Source: Morningstar
Past performance is not a reliable indicator of future results

The large-cap tech stocks are outperforming because of their superior earnings outlook, largely due to the impact of AI. The table below shows that over the next two years, the Magnificent Seven are expected to deliver earnings growth way ahead of non-US developed markets, with only the emerging markets expected to deliver a similar result. In fact, the gap between these stocks and the rest of the US market is even wider than it is to the ex-US developed world. There is a strange dichotomy between the optimism around AI and the otherwise sluggish US economy. While US indices are being dragged up by the Magnificent Seven and AI, investors who want to stick with this trade might want to consider a technology-focussed portfolio rather than a US fund or ETF. It is notable how the valuation multiple for the tech stocks rapidly falls when you look out two years, much more rapidly than the multiples for the other indices in our table. The bull case for AI is that it will transform most industries, in which case this superior earnings growth would be expected to continue for many years to come, and the valuation multiple would rapidly decline when considering these further forward earnings.

EARNINGS ESTIMATE

IndexPrice-to-earnings (1-year forward)EPS growth (1-year forward) (%)Price-to-earnings (2-year forward)EPS growth (2-year forward) (%)
MSCI World ex USA14.6x12.112.9x13.5
S&P 50020.7x12.718.8x10.1
Bloomberg Magnificent 729.7x13.825.7x15.4
MSCI Emerging Markets12.7x17.111x15.8

Source: Bloomberg Estimates, as of 17/10/2025

Given the strong performance of AI-related stocks, it is perhaps unsurprising that the best-performing investment company across both the AIC Global and AIC Global Equity Income sectors year-to-date is Manchester & London (MNL). Its portfolio is highly concentrated in AI-related names, with NVIDIA, Microsoft, and Broadcom together accounting for c. 72% of its holdings (as of the end of August). Over that period, MNL generated a NAV total return (TR) of 27.8%, outperforming global equity indices such as the MSCI ACWI Index, which returned 10.1%, and the 8.8% simple average return of global equity-focussed investment companies. MNL, however, can be seen as an outlier within the peer group given its very concentrated portfolio and near-exclusive focus on the information technology sector. The runner-up, Scottish Mortgage (SMT), also has significant exposure to AI-linked companies and has benefited from positions such as Cloudflare, a cloud services provider whose shares have risen 86.9% year-to-date.

Exposure to AI-related stocks, notably Broadcom, also supported the performance of Invesco Global Equity Income (IGET), which outpaced global equity indices with a NAV TR of 12% year-to-date. Yet, IGET’s performance was also aided by overweight allocations to continental Europe and the UK, regions that saw a recovery in the first half of the year, notably with defence companies and banks rallying. Key contributors also included UK-listed bank Standard Chartered, which reported improved earnings and net interest margins, as well as aerospace & defence company Rolls-Royce, which has experienced revenue and profit growth under CEO Tufan Erginbilgiç (appointed in January 2023). Similarly, Murray International (MYI) benefited from its holding in Broadcom as well as from its overweight position in emerging markets, which have performed strongly since the beginning of the year, notably thanks to a weaker US dollar.

The table below lists all investment companies in the AIC Global and AIC Global Equity Income sectors that have outperformed the MSCI ACWI Index since the beginning of the year (to 10/10/2025).

YTD RETURNS

Investment companySectorReturn to 10/10/2025 (%)
Manchester & London (MNL)AIC Global27.8
Scottish Mortgage (SMT)AIC Global18.4
Murray International (MYI)AIC Global Equity Income14.2
Monks (MNKS)AIC Global13.2
Invesco Global Equity Income (IGET)AIC Global Equity Income12
MSCI ACWIN/A10.10%

Source: Morningstar
Past performance is not a reliable indicator of future results

The dilemma

Among his numerous adventures, Tintin sometimes faces painful dilemmas. For example, in Tintin in Tibet, he must choose between risking his life to climb the Himalayas in the hope of rescuing his friend Chang, whose plane crashed in the mountains, or accepting the high probability that his friend did not survive and calling off the perilous expedition. Similarly, global equity investors may face difficult dilemmas in the current market environment. The recent outperformance of non-US equities could be seen as the premise of a sustained broadening of returns beyond the technology-dominated US equity market. Yet, the strong rebound of AI-related stocks since Liberation Day may suggest that the outperformance of international equities was only a short-term blip and that US tech stocks will continue to dominate. Managers of trusts in the AIC Global and AIC Global Equity Income sectors take different views on this matter, with some remaining enthusiastic about AI-related names, while others see better opportunities elsewhere.

Franklin Global Trust (FRGT) is one strategy with significant conviction in the AI theme, expecting it to drive growth for many years, potentially decades. Managers Zehrid Osmani and Jonathan Curtis gain exposure to AI primarily through semiconductor companies — including NVIDIA, ASML, Cadence Design Systems, and BE Semiconductors — which they view as key beneficiaries of increased spending on AI infrastructure. They also anticipate that the next phase of AI development will reward companies capable of monetising the technology. Accordingly, they hold Meta Platforms, which they believe can leverage AI to boost advertising revenue and enhance user experience across its platforms. In the first half of the trust’s 2025 financial year (ended 31/07/2025), the managers also built exposure to AI in China, noting the country’s progress in this area, and initiated a new position in Tencent, China’s leading social media company and a significant player in the global gaming industry. They see multiple ways the company could leverage AI, such as improving advertising allocation, expanding its addressable market, and supporting more efficient game production.

SECTOR ALLOCATION

Source: Franklin Templeton, MSCI

Similarly, SMT is exposed to AI through companies involved in the build-out of the AI infrastructure, such as NVIDIA and TSMC — the world’s largest semiconductor foundry — as well as through businesses that leverage AI by embedding it into their products. For example, the trust holds AppLovin, an ad tech company that uses AI to optimise mobile game monetisation and is expanding into e-commerce advertising, as well as Meta.

On the contrary, Alliance Witan (ALW) exhibits more pronounced underweight positions in the information technology sector and North American equities than usual. ALW is managed by an investment committee at Willis Towers Watson, who aim to keep the portfolio as closely aligned as possible with the benchmark in terms of country, sector, and factor exposure, while allocating capital to high conviction stock pickers. The underweights are therefore due to those stock pickers not investing much in US technology mega-caps. For instance, GQG Partners — a stock picker following a quality growth-at-a-reasonable-price approach — has rotated out of technology names and into defensive stocks. The team is concerned about the valuations commanded by US tech mega-caps, drawing parallels with late 2021 and early 2022, just before interest rates rose and technology stocks subsequently sold off. Other stock pickers also reduced their exposure to technology following the launch of DeepSeek’s cost-efficient AI chatbot in January 2025, which raised questions about the substantial capital expenditure by US tech firms on AI infrastructure.

REGIONAL ALLOCATION

Source: Willis Towers Watson

IGET has an even larger underweight in North America and the information technology sector, and more sizeable overweight positions in Europe and the UK, deviating further from global equity indices. This positioning is not the result of top-down views but stems from the managers’ approach to stock selection, as they favour attractively valued companies with robust fundamentals. This valuation-sensitive approach naturally steers them away from US tech mega-caps, which trade on high multiples, and toward Europe and the UK, where mispriced opportunities are arguably more abundant. Managers Stephen Anness and Joe Dowling have also identified opportunities in the US outside of the tech mega-caps. This includes cruise operator Viking, which benefits from a strong position in the cruise market. The managers also believe that the company could be less sensitive to inflation and recession risks, as Viking targets wealthy US retirees. Nonetheless, Stephen and Joe are also willing to hold stocks exposed to the AI theme if the price is attractive. For example, they have been holding Broadcom rather than NVIDIA, seeing the former as more attractive from a valuation standpoint and offering greater diversification in revenues while providing similar exposure.

Brunner (BUT) is also underweight North America relative to standard global equity indices; however, this is structural, as the trust uses a composite benchmark consisting of 70% FTSE World ex-UK and 30% FTSE All-Share. Conversely, BUT has a structural overweight to the UK, which the managers view as a differentiated market, rich in mature, cash-generative businesses trading at attractive valuations. This does not mean BUT has no AI exposure. For instance, the managers took advantage of the market sell-off in April to build a position in Amazon — whose cloud business, Amazon Web Services, provides exposure to the AI theme — while the portfolio also holds two other Magnificent Seven stocks: Microsoft and Alphabet. That said, the managers view US equities as richly valued in aggregate and have added new positions in non-US stocks since the start of the year, focussing particularly on value-oriented names. Examples include South Korean car manufacturer KIA, noting that it is one of the most profitable automakers with a strong balance sheet and exceptional operating margins, which are uncommon features in the automotive industry.

Flea market

In The Secret of the Unicorn, Tintin purchases an old model ship at Brussels’ flea market to gift it to his friend Captain Haddock. Unknown to him, a scroll containing a clue leading to a 17th-century pirate’s treasure is hidden under the mainmast. This treasure is later found by Tintin and his companions, Captain Haddock and Professor Calculus, in Red Rackham’s Treasure, enabling Haddock to acquire Marlinspike Hall. In short, the modest price Tintin paid for an old model ship technically led to Captain Haddock acquiring a country house — undoubtedly a great bargain. Stretching the analogy somewhat, acquiring shares of investment trusts trading at a discount can prove to be excellent bargains for patient investors, as they may benefit not only from the performance of the underlying NAV but also from a potential narrowing of the discount.

In the AIC Global sector, we think SMT’s discount of 11.5% could be particularly attractive. The trust’s discount has been narrowing from its low point of 22.7% in the first half of 2023 and may continue to narrow if AI-related stocks remain dominant in market returns. That said, given SMT’s high-growth mandate, its discount has historically been, and is likely to remain, prone to sharp swings, reflecting the strategy’s volatility. We would also highlight F&C Investment Trust (FCIT), which offers core exposure to global equities and currently trades at a 7.7% discount. The trust traded close to par or at small premiums in Q4 2022 and Q1 2023, possibly reflecting its resilience during the bear market of 2022 compared with sector peers. In addition, the board operates a share buyback policy aimed at keeping the share price close to NAV and reducing discount volatility. For example, over the course of the year to 10/10/2025, c. 2% of the shares outstanding were repurchased.

DISCOUNT

Source: Morningstar

Most constituents of the AIC Global Equity Income are trading at discounts close to par, with some even commanding a small premium. The outlier is Scottish American (SAIN), which is trading at a 10.2% discount at the time of writing, more than one standard deviation below its five-year average of 3.5%. The trust commanded a premium prior to 2022 but fell to a discount when central banks began hiking interest rates. This may reflect the fact that the trust had a relatively high-growth portfolio for its sector, and has therefore been affected by the higher-rate environment, with the strategy prioritising dividend growth rather than generating the highest possible yield. That said, central banks have been lowering interest rates since 2024, which could make SAIN more attractive. Moreover, we think it is worth remembering that fixed-income instruments do not offer income growth potential.

DISCOUNT

Source: Morningstar

In contrast, many investment companies focussing on smaller companies are offering wide discounts. The higher interest rate environment has been a headwind for smaller companies, as investors’ risk appetite typically wanes in such conditions. However, they could also benefit from falling interest rates. Within the sector, we would highlight Global Smaller Companies (GSCT), which is trading at a 10.4% discount and provides well-diversified exposure to small-caps worldwide, across both developed and emerging markets. Manager Nish Patel focusses on attractively valued, high-quality businesses with strong balance sheets, pricing power, and predictable earnings, offering a more prudent approach to the asset class compared to some of the racier options in the sector.

Conclusion

While AI-related stocks are expected to continue delivering strong earnings growth, we think the high multiples they command leave little margin for error. As such, we believe non-US equities could be more attractive at this juncture, trading on more reasonable multiples while being expected to deliver stronger earnings growth than their US peers outside the AI-related cohort. In particular, we think emerging markets are especially attractive at this stage, offering even higher expected earnings than the Magnificent Seven, while trading at lower multiples than non-US developed markets. That said, we acknowledge the strong track record of US tech leaders in consistently exceeding earnings expectations, an outcome that may persist.

However, the AIC Global and Global Equity Income sectors offer strategies that could cater to different views on this debate. Investors bullish on AI may consider FRGT, which is exposed to the theme through both “picks and shovels” and direct AI beneficiaries. Conversely, investors more cautious on AI could look to IGET, which maintains a selective exposure with a strong focus on valuation, or BUT, which aims to balance the growth, quality, and value factors.

Alternatively, FCIT could be an interesting option for investors seeing strong opportunities in both areas. Manager Paul Niven is constructive on the AI theme, seeing strong long-term potential in it, and believes we could be getting closer to a phase of broader AI adoption, which could drive productivity improvements, and in turn, stronger corporate earnings and improved profit margins. However, Paul also believes that market returns could continue to broaden out of the US, thanks to more attractive valuations and potentially greater flexibility in monetary and fiscal policies in other regions. For example, exposure to emerging markets in the portfolio has increased from c. 5% at the end of 2024 to c. 10% at the end of August, as Paul is seeing tailwinds from a weakening US dollar and the fact that investors remain underinvested in these regions.

We also believe strategies focussing on smaller companies could be attractive at this juncture, as central banks have been cutting interest rates since 2024, and further reductions may be on the horizon. This is because lower rates could boost investors’ risk appetite and reduce pressure on smaller companies, which often rely on floating-rate debt. In addition, many of the investment companies focussing on smaller companies are trading at wide discounts, offering potential upside from both discount narrowing and a small-cap recovery.

Change to the Snowball

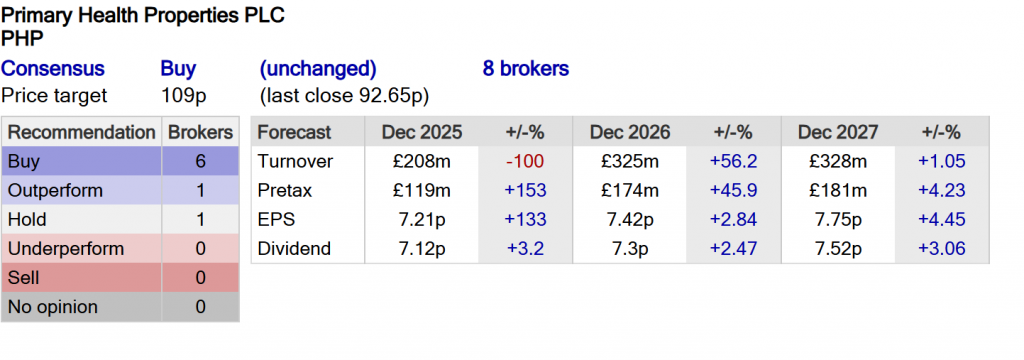
10k of the Snowballs cash will be re-invested in PHP, the yield after the takeover of Assura is not 100% certain but it’s one of the safest yields in the market with the chance of a modest increase in value.

Stifel raises Primary Health Properties to ‘buy’ (hold) – price target 105 (92) pence.

 Barclays reinitiates Primary Health Properties with ‘overweight’.

Currently trading xd

Notice of Interim Dividend

The Company announces that the fourth quarterly interim dividend in 2025 of 1.775 pence per ordinary share of 12.5 pence each will be paid as an ordinary dividend on 21 November 2025 to shareholders on the register on 10 October 2025. 

Current yield 7.5%

Further across the pond

Contatrian Investor


Turn Your Portfolio Into
a Monthly Income
Machine

Fortunately for you and me, the financial markets aren’t 100% efficient. And some corners are even less mature and less combed through than others.

These corners provide us contrarians with stable income opportunities that are both safe and lucrative.

There are anomalies in high yield. In an efficient market, you wouldn’t expect funds that pay big dividends today to also put up solid price gains, too.

We’re taught that it’s an either/or relationship between yield and upside – we can either collect dividends today or enjoy upside tomorrow, but not both.

But that’s simply not true in real life. Otherwise, why would these monthly payers put up serious annualized returns in the last 10 years while boasting outsized dividend yields?

For example, take a look at these 5 incredible funds that pay monthly and soar:

This is the key to a true “9% Monthly Payer Portfolio” – banking enough yields to live on while steadily growing your capital. It’s literally the difference between dying broke and never running out of money!

Across the pond

2 Big Dividends (Up to 17%) That Are Way Too Good to Be True

Michael Foster, Investment Strategist
Updated: October 20, 2025

Business development companies (BDCs) have gained popularity in recent years, but they still don’t get as much attention as they should. Which is too bad, because they pay life-changing (no exaggeration here) dividends.

The two we’ll look at below yield more than 12.9%. In other words, drop $10,000 in and you’re getting $1,290+ back in dividends every year.

That makes BDCs useful tools for retirees. They’re also a “best friend” to what I’ll call “middle market” companies—those that are too big to borrow from a local bank but too small to interest big, institutional players like, say, a Goldman Sachs (GS).

So it’s no surprise that BDCs have started to make it on to the mainstream crowd’s radar. But—these days especially—we do need to be careful with them.

I’ll get into why—and why I prefer another high-yielding asset class to BDCs right now—in a second. But for starters, let me just say that it’s vital to avoid BDCs with two main flaws: 1) Those that are too specialized in one sector and/or 2) Those that are saddled with sky-high management fees.

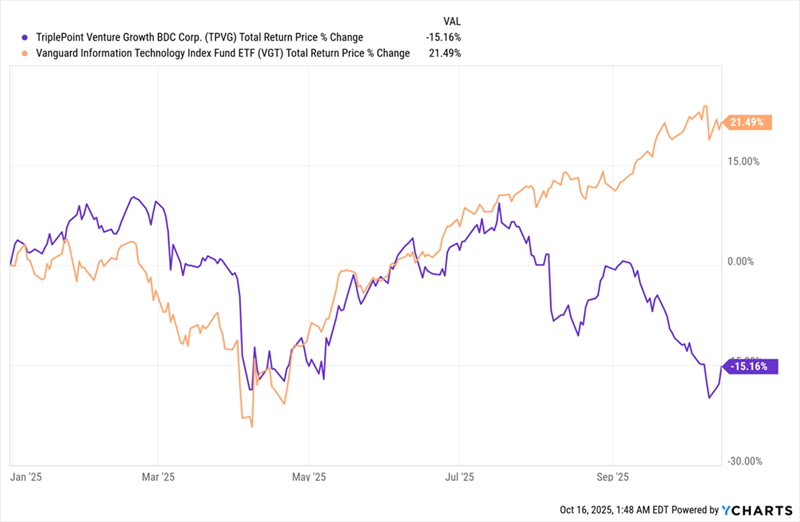
Let’s start with that first point—a BDC too focused on one sector. We’ll do that by looking at the 16.6%-yielding (!) TriplePoint Venture Growth BDC Corp. (TPVG), which mainly lends to companies in the tech sector. Trouble is, on a total-return basis—so including reinvested dividends—the fund is down 15% this year, as of this writing.

This in a year where tech in general is up over 21%, as measured by the Vanguard Information Technology ETF (VGT) index fund. You’d have been better off buying the ETF—or better still, the high-yielding tech-focused closed-end fund (CEF) we’ll get to shortly!

Mainstream Tech ETF Crushes Tech-Focused BDC (Despite Its 16.6% Dividend)

Now let’s talk about that second “BDC trap,” which is very easy to miss: high management fees.

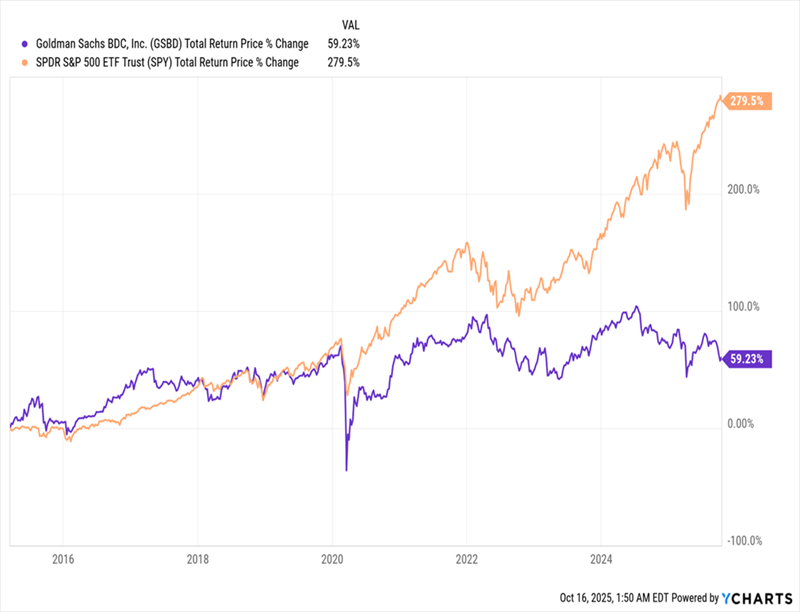
As I said a second ago, BDCs’ borrowers are usually too small for big banks to take on, but that hasn’t stopped big banks from getting into the game by launching their own BDCs. Even Goldman has its own BDC—the unimaginatively named (and 12.9%-yielding) Goldman Sachs BDC (GSBD).

This one launched a decade ago and has trailed the S&P 500 by a huge margin.

S&P 500: 1, GSBD: 0

Beyond that, the BDC charged about 3.9% in fees ($35.2 million in base fees and $23.9 in incentive fees on about $1.5 billion in assets) in 2024, and a similarly high fee bill is accruing for investors in 2025. With so much in fees going to management, it’s tough for the portfolio to generate enough to cover the dividend, too.

Yet many investors overlook that, distracted as they are by GSBD’s outsized yield.

Income investors who want to boost the yield in their portfolio buy BDCs in the hopes that these companies can keep maintaining those big payouts by doing bigger deals that cover their ongoing expenses.

That does work sometimes, but not all the time. In the cases of both GSBD and TPVG, we saw dividends remain reliable—until quite recently.

TPVG, for its part, cut its regular dividend last year, and as a result, shareholders are getting less than they were expecting. Thus, the BDC’s 16.6% yield looks good today, but it will get smaller tomorrow—and the shares could drop again when that happens.

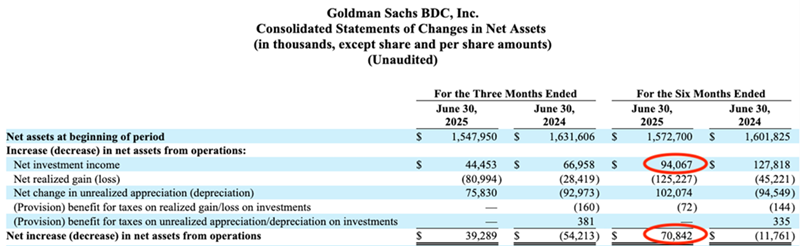
Thus GSBD seems safer, since its payouts have actually gone up since its IPO. But this is an illusion. If you look at the company’s income statement, you see the problem.


Source: US Securities and Exchange Commission

In the first six months of 2025, GSBD earned $94.1 million in investment income, which comes out to about a 12.4% annualized return on the fund’s net assets. At a 12.9% yield, GSBD is coming up just shy of covering the dividend.

Except the net increase in GSBD was much less than that because of a $125-million loss in its portfolio, meaning the net annualized return for the good loans in its portfolio after accounting for losses on the bad loans was 9.4%, still good and enough to cover much of the dividend—but not all.

In fact, if this keeps up, about 40 cents per share of dividends will need to be slashed—lowering GSBD’s yield from its 13% level to more like 9%.

Forget GSBD and TPVG: This CEF Is a Much Safer Play

I’m not saying all BDCs are risky—just that we need to pay close attention to not only how they are run but who they lend to. BDCs can run afoul of situations like First Brands, an auto parts supplier that recently declared bankruptcy. In all, 14 BDCs were invested in the firm (but not GSBD and TPVG).

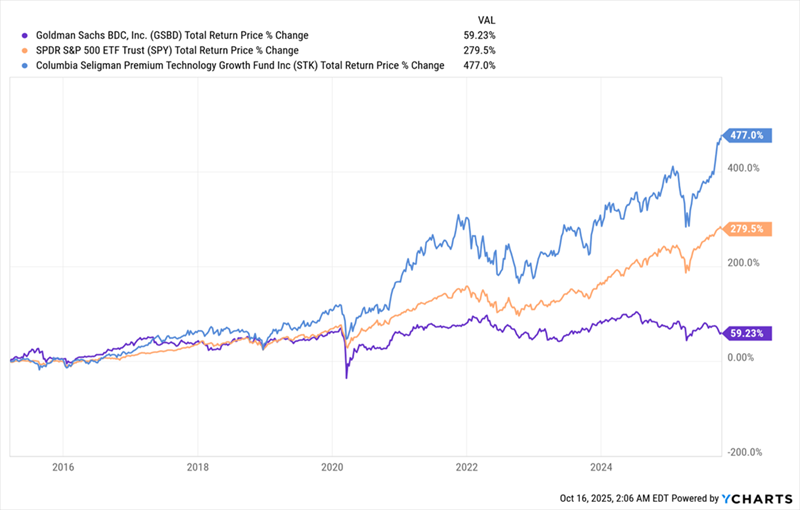
This is not a risk that affects CEFs that invest in blue chip stocks. Consider, for example, a tech-focused CEF called the Columbia Seligman Premium Technology Growth Fund (STK), which has done three impressive things over the last decade. First, the fund (in blue below) has beaten both the S&P 500 (in orange) and GSBD (in purple) as of this writing.

STK Outruns Stocks and Its BDC “Cousin”

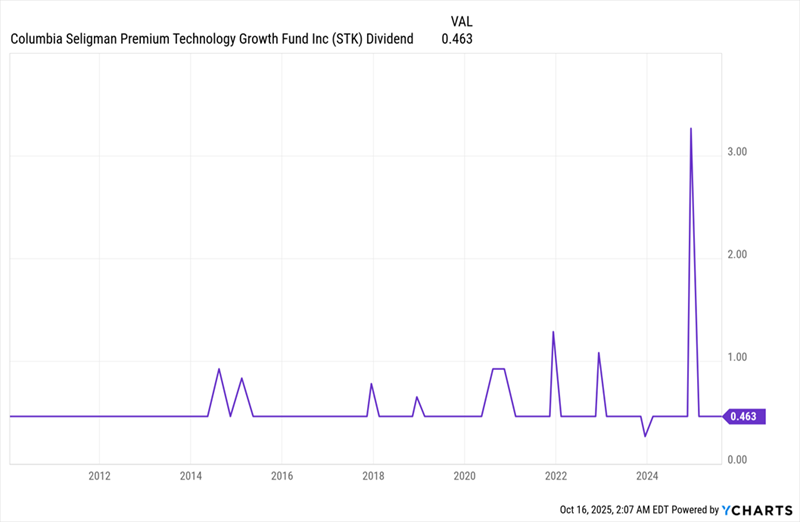
Second, its 5% dividend not only has never been cut—it’s also been bolstered by several special dividends (the spikes and dips in the chart below) over time.

STK’s Special Dividend Parade Keeps Rolling

Finally, it’s done this by holding liquid, conservative mega-cap names like Apple (AAPL), Amazon.com (AMZN) and Cisco Systems (CSCO).

And even after its recent run, STK is cheap, trading at a 5.3% discount to net asset value (NAV, or the value of its underlying portfolio) as I write this. That’s far below its five-year average of a 3.1% premium, setting up a nice (and rare) opportunity to buy its portfolio of top-notch tech stocks for 95 cents on the dollar.

With fewer risks, bigger returns and a generous yield, STK is a compelling alternative to a BDC focusing on the same sector, like TPVG. And STK’s dividend is actually small compared to that of the average CEF, which yields 8.4%. That means you can boost your yield with other, higher paying CEFs without increasing your risk.

More of the same ?

From The Telegraph Editor
Good afternoon.

This week, Ambrose Evans-Pritchard outlines how today’s tech boom is different from that of 25 years ago; while Jeremy Warner argues that Britain’s rampant compensation culture is stifling economic growth.

Ambrose Evans-Pritchard
World Economics Editor

Wall Street equity bubbles do not end just because prices are stretched to extremes. They typically keep running until the US Federal Reserve turns off the credit spigot and forces capitulation.

It may be true that America’s AI boom is showing signs of mass delusion. Nvidia, Meta, Google, Microsoft, Palantir, Tesla or Strategy – take your pick, add au goût – are close to defying the laws of commercial and geopolitical gravity. We may already be deep into greater fool territory.

But that does not preclude a further parabolic rally over the next 12 to 18 months before resurgent inflation compels the Fed – even a captive Fed, once Donald Trump has completed his hostile takeover – to break the fever. A view is taking hold in hedge-fund land that the US is more likely to see an overheating blow-off in early 2026 than a stock market crash.

Every big bubble of the last century was popped by the Fed, either deliberately or by accident.

The New York Fed set out to kill the electrification and radio boom of the Roaring Twenties as early as January 1928, fearing that margin buying at 10 times leverage was feeding dangerous speculation.

The Fed “succeeded” but not until the Dow index had risen a further 65pc by October 1929.

It killed the telecom and dotcom bubble in 2000 by raising rates 175 basis points in the final year of the cycle. By then, US fiscal policy was also extremely tight. The budget surplus was 2.3pc of GDP.

It killed the subprime credit bubble by raising rates 425 points in two years, plateauing at 5.25pc in August 2006. By then, traders at the coal face could already see trouble in a slew of exotic “sliced-and-diced” mortgage securities. The party went on. Bear Stearns (RIP) and Lehman Brothers (RIP) kept rising to giddier heights. Wall Street did not peak until October 2007.

Lesson one is that a bull market with attitude can go on longer than most short-sellers can stay solvent. Lesson two is that it takes iron-fisted policy tightening to stop the stampede.

None of these market crashes has much in common with the monetary cycle of the Fed today or with the fiscal recklessness of Maga Washington. The Powell Fed is cutting rates even though inflation is above target. The budget deficit is 6.2pc of GDP.

“Financial conditions remain very accommodative,” said Pierre-Olivier Gourinchas, the International Monetary Fund’s chief economist. This is an understatement. The average risk spread on BBB corporate debt is near an all-time low of 100 basis points.

Dario Perkins, from TS Lombard, said Trump’s tariffs have temporarily tightened fiscal policy by 1pc of GDP this year: tax cuts in the “one big beautiful bill act” will offset this with loosening of 1pc in 2026.

“You’ve got this big fiscal swing from contraction to stimulus going into next year. The Fed is cutting rates again and that revives housing and construction quite quickly. It’s a big boost to small companies because of the way they finance their debt,” he said.

“All year, central banks around the world have been cutting rates and that is beginning to feed through to credit. You’ve got fiscal stimulus in Germany and potentially from China. All of this is reflationary,” he said.

Mike Wilson, the equity chief at Morgan Stanley, said the US has already been through a series of “rolling recessions” – one after another, hitting consumer goods, housing, manufacturing, transport and finally the Doge purge of the government itself.

“It has effectively rolled through the entire economy,” he said, arguing that the US is now in the classic early phase of a new business cycle.

The Bank of England’s Financial Policy Committee has flagged parallels between AI mania and the internet mania of the late 1990s, fearing an equity rout if AI fails to deliver.

It said the market share of the S&P 500’s top five companies has hit 30pc, “higher than at any point in the past 50 years”. The cyclically adjusted price-to-earnings (Cape) ratio is close to its lowest level in 25 years, “comparable to the peak of the dotcom bubble”.

It said lack of electricity could choke the AI boom, as indeed it might since Trump is waging a culture war on wind and solar – the fastest way to increase power in the US. It warned of supply chain bottlenecks and “conceptual breakthroughs” that suddenly change the AI business model – an allusion to the DeepSeek shock.

All of this is true but it is not yet imminent and the parallel with 2000 goes only so far. Dotcom stars mostly had shallow roots, thin revenues and were often little more than a website. The giants controlling most of the AI industry have deep pockets, real earnings, low debt and entrenched market share. They can take a big hit.

Stephen Jen and Joana Freire from SLJ Capital think the AI boom still has a long way to go.

“We are only at base camp compared to the price action in 1999-2000,” they said.

The P/E ratio of tech stocks was 72 in 2000, compared to nearer 30 today. They said AI is a national security imperative in an existential tech race with China. Nobody had a thought for China during the dotcom bubble.

What could spoil the picture? We could certainly see an economic “growth scare” before the next upward leg of the market.

The US is at the nadir of the policy cycle right now. The US government shutdown is dragging on and 100,000 federal employees are being laid off this quarter. The growth in private jobs has stalled.

JP Morgan’s proprietary credit card data show that retail sales hit a wall in September.

“There is a good chance real incomes will contract in the coming several months,” said the bank.

However, I strongly doubt that the Fed will let this metastasise into a self-feeding recessionary process or that it can even operate any longer as a scientific central bank. Trump is taking over the Fed Board and will progressively compel it to suppress rates far enough to drive a hot economy until the midterm elections next year.

He has appointed his guru Stephen Miran to the Fed with an easy money voodoo agenda – technically, Miran claims that the “neutral” rate of interest is two percentage points lower than Fed experts think. Trump is waging a war of harassment against legacy appointees, either to drive them out or to intimidate them into towing the line on premature rate cuts.

Trump will own as much of the Fed as he needs by mid-2026. I struggle to see how there can be a lasting stock market crash over the next year in this debauched politico-monetary setting.

In the end, re-accelerating inflation could – and will again – push up Treasury yields and short-circuit the asset boom. Should that happen, I have no doubt that the Trump treasury would strong-arm the Fed into capping yields by means of financial repression – as happened in the late 1940s.

If Trump is willing to commit $20bn (£15bn) from the US treasury’s emergency fund – or is it now $40bn? – to buy Argentine pesos and rescue the drowning Javier Milei, he will do anything.

Ultimately, Trump will run out of options and face his own intractable inflation crisis. But that is a story for the middle of his presidency.

It is too soon to bail out of AI mania. At the risk of sticking my neck out too far, I think any further sell-off on Wall Street should be treated as a fresh chance to buy. Keep your nerve.

Change to the Snowball

I’ve sold SEIT on valuation grounds for a profit of £1,463.00 after the share has risen 35% from its low. It still trades on a discount of 35% to NAV so could have further to travel.

I’ve used part of the funds to buy another 4926 shares in ORIT for 3k.

I’ll re-invest the balance maybe tomorrow.

BSIF

Bluefield Solar says merger with fund manager and dividend cut are needed to prevent fund being starved of capital

  • 21 October 2025
  • QuotedData

John Scott, the outgoing chair of Bluefield Solar Income (BSIF), has warned shareholders in the renewables fund that the “business as usual” option is unavailable as he held out the prospect of the double-digit yielder merging with its fund manager Bluefield Partners and cutting its payout.

Delivering his last annual report, Scott said the £493m investment company had responded well to the challenges of the last three years when interest rates had soared and capital markets had effectively closed to the sector with its shares sliding to a 30% discount to net asset value (NAV), preventing conventional fund raising.

While a partnership with pension funds had enabled the company to recycle capital from its portfolio, supporting a high dividend, a £20m share buyback programme and reinvestment in the portfolio, he said shareholders needed to be aware that the absence of additional equity and cheap debt would require the sale of its pipeline assets.

“Such disposals will gradually starve the company of growth opportunities and confine BSIF to its current position, namely the steady erosion of the company’s NAV, reflecting attrition of our capital base, with returns delivered only in the form of income,” he said.

Following earlier efforts to sell the company, Scott said it was clear there was widespread investor support for renewables – despite efforts by right-wing politicians to reverse the move to clean energy – and that BSIF’s value lay in the combination of its operational solar portfolio combined with the development platform of Bluefield Partners.

“The board is therefore considering other paths for the future of BSIF, including options that could see it move towards a more integrated business model which is better placed to capture the growth opportunity that eludes shareholders in the company’s current form, but is more readily available in an integrated Bluefield model,” said Scott.

Initial discussions with Bluefield showed this could be attractive to both the company and its investment adviser.

“Integrating the Bluefield Group’s 140-person platform, covering development activities through to operations, would create a UK-focused green independent power producer, one that with the appropriate capital structure, corporate debt and dividend policies could be a largely self-funded growth model,” he added.

Scott said the transition would require a thorough re-examination of the 10.7%-yielder and its dividend policy to assess how much of its income “we would be able to distribute if we are to fund our pipeline from retained earnings and additional borrowings”.

The shares fell 3.2% to 80.6p

The results showed that despite a second half recovery in irradiation, the net asset value of the portfolio of 122 solar plants, six wind farms and 109 small scale onshore wind turbines fell to 116.56p per share at 30 June from 129.75p a year earlier. Total underlying earnings per share dipped from 10.57p to 10.4pp covering 8.9p of dividends, raised from 8.8p in the previous year. A target of 9p has been set for the current 2026 year.

Our view

James Carthew, head of investment company research, said: “At QuotedData, we have been discussing amongst the analysts what is the way forward for the renewable energy sector. It felt to us as though BSIF was the most likely of the companies in the sector to transition from an investment company to a trading company.

“That seems to be the board’s preferred path. The chairman’s statement makes it clear that one of the casualties of this might be the current high dividend, although the board has indicated that the dividend will rise slightly to 9p for the current financial year.

“We want to see the sector used as an engine to drive the process of decarbonising the UK economy. The government could have done more to encourage this but issues such as the cost disclosure problem have actively frustrated it. BSIF’s proposals will need careful scrutiny, to ensure that BSIF shareholders are not disadvantaged relative to the managers. We await the next step with considerable interest.

QD News
« Older posts Newer posts »

© 2026 Passive Income Live

Theme by Anders NorenUp ↑