Passive Income Live

Investment Trust Dividends

Page 336 of 456

DYOR

Royston Wild

by The Motley Fool

The London stock market is a great place to discover top dividend shares. It’s packed with companies with strong records of dividend growth. What’s more, years of share price underperformance also mean many of these offer some staggeringly high dividend yields.

Dividends are never guaranteed. But if broker forecasts are correct, a £25,000 lump sum invested equally across them would provide me with a £1,750 second income over the next 12 months.

I’m confident too these high-yield shares will steadily increase shareholder payouts over the long term. Here’s why I think they might be great buys for dividend investors.

Wind warrior

Renewable energy stocks like Greencoat UK Wind have significant earnings potential for long-term investors.

Adverse weather conditions can impact power generation from time to time, putting a drag on revenues. But over an extended time horizon, wind farm operators could enjoy exceptional growth as the world switches from fossil fuels to cleaner energy sources.
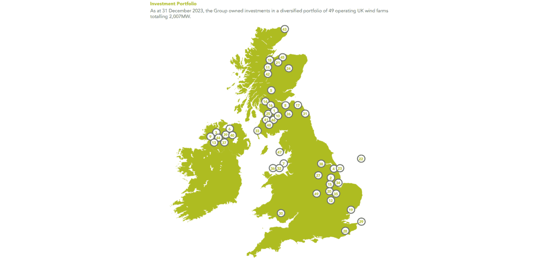
Source: Greencoat UK Wind

Source: Greencoat UK Wind Provided by The Motley Fool

Property giant

Real estate investment trusts (REITs) can also be a great way to source an income over the long term. They are required to pay a minimum of 90% of their annual rental profits out to shareholders.

Urban Logistics REIT is one I expect to thrive as e-commerce steadily grows. As an operator of storage and distribution hubs, it provides an essential service that allows manufacturers, retailers and delivery companies to get product to online consumers.

In fact, this part of the property market is experiencing a huge shortage. And so like-for-like rents (which grew 19% here last year) look set to continue growing strongly.

High interest rates pose an ongoing problem for its net asset values (NAVs). But on balance, I think Urban Logistics is worth a close look.

A riskier pick

Growing political and social turbulence in Georgia threatens to derail the country’s banks like TBC Bank Group.

Financial product penetration’s low in the Eurasian country. And it’s been soaring in recent years as the economy there has boomed.

TBC’s own profits have jumped 111% over the past five years. But it’s performance could slow sharply if turbulence in Georgia continues.

Portfolio update

The current cash, after the capital return from ADIG of £3,7333 is £5,855.17. The return has not been included in the Snowball as it’s not a repeatable payment.

The funds are going to be re-invested in the RGL share subscription

59,100 shares at 10p

Now, u don’t need to use a calculator to realise that is short of the entitlement amount but the dividend tomorrow of £331 from RGL will take the Snowball over the line.

The closing date for subscription is the 14th of July.

The Snowball will be overweight with RGL but the intention is still to pay a reduced dividend, so the position will be sold into, overtime.

The subscription shares are trading around 13p but this price may fall after the share consolidation as the newly issued shares find a new home. One option is to sell some shares in the market and replace them with the subscription shares, when issued.

Income until you cross the bar

Here’s how I’d turn FTSE 100 dividend shares into a second income for life

Here’s how I’d turn FTSE 100 dividend shares into a second income for life Provided by The Motley Fool

by Harshil Pate

There’s a lot to like about dividend shares. For one, they can make an excellent source of passive income.

Once the shares are bought, there’s very little left to do except wait. Long-term investments require a long-term mindset, after all.

Doing so can have a snowball effect after several years, due to the compounding effect.

Finding the best dividend shares

I’d begin by searching for quality shares that offer both growth and income. After all, dividends need to be paid from earnings. So growing earnings can lead to growing dividends.

I’d also look for a long track record of consistently paying dividends. This shows a company’s long-standing approach to distributing cash to shareholders.

Of course, there’s no guarantee that earnings will grow and no certainty that dividends will continue to be paid. But a substantial dividend history can reduce this risk.

Risk can also be lowered by owning a selection of shares, across a variety of sectors. Doing so avoids putting all my eggs in one basket.

Digging for growth

One large-cap share that meets this criteria is Footsie mining giant Rio Tinto (LSE:RIO). It has consistently paid dividends for over a decade.

Bear in mind that it’s a cyclical business though, and demand for its iron ore can fluctuate. But as a low-cost producer, I reckon Rio could withstand such swings in demand.

Also, more than half of its sales are from China. When China expands construction projects, it can have a material effect on Rio’s earnings. But of course, the opposite is also true.

Future growth is likely to come from metals needed for the energy transition and ongoing urbanisation. Rio expects demand to grow by 3.9% per year for the next nine years.

It’s all about the dividend

For shares like Rio Tinto, dividends can have a weighted effect on total returns. For instance, over the past decade, its share price has risen by around 5% a year. If that sounds mediocre, I’d probably agree.

But by factoring in dividends, its total return amounted to a healthier 10% a year. That significantly beats the FTSE 100 average of 6%.

Right now, Rio has a dividend yield of 6.5%. It also ticks some boxes when it comes to business quality. For instance, it offers a return on capital employed of 16% and an operating profit margin of 27%, both meeting my double-digit requirement.

Just like Rio Tinto, I can find several other FTSE dividend shares that tick my boxes. IG Group and BP come to mind. If I had available cash, I’d buy all three to target a solid second income for life.

££££££££££££

remember to leave some of your retained capital to those wee cats and dogs.

GL

Doceo Fund Monitor

The Fund Monitor

Menhaden Resource Efficiency recommences its share buyback programme, Riverstone commits a further £20m to its buyback programme and Tritax Big Box gets a rating upgrade.

By Frank Buhagiar 09 Jul 2024

Menhaden Resource Efficiency hits the buyback trail again

Menhaden Resource Efficiency (MHN) put out a short and sweet press release announcing that it was recommencing its share buyback programme in light of the Company’s wide share price discount to its net asset value. The shares have been trading at around a 40% discount to net assets, not far off the 52-week high discount of 42%.

Riverstone Energy tacks on another £20m to buyback programme

Riverstone Energy (RSE) announced it is committing a further £20m to its buyback programme. That represents around 9% of the fund’s market cap. RSE no stranger to buying back its own shares. Since October 2023, the company has acquired 110,407 of its shares at a total cost of approximately £0.7 million ($0.9 million). But that’s nothing compared to the 15,047,619 ordinary shares acquired via the tender offer earlier this year at a cost of £158 million.

Tritax Big Box gets a rating upgrade

Tritax Big Box (BBOX) noted Moody’s Ratings has upgraded its credit rating outlook on the logistics REIT to Baa1 (positive) from Baa1 (stable) and reaffirmed its long-term corporate credit rating. BBOX puts the upgrade down to growing scale, increased portfolio diversification and ‘a continued focus on high-quality logistics assets, which are supported by the recent acquisition of UK Commercial Property REIT Limited (UKCM).’

Dividend Watch

Artemis Alpha’s (ATS) total payout for the year came in at 6.8p a share, a 9.7% increase on the previous year’s 6.2p a share. That comes after the 4.26p final dividend was announced alongside the latest full-year results. ATS has a policy to “deliver growth in dividends at a rate in excess of inflation”.

Doceo Tip Sheet


The Telegraph says investors should put Alliance Witan on their watch lists, while MoneyWeek believes the combination of HarbourVest’s very strong performance record and ‘inexplicably high discount’ is hard to beat

By
Frank Buhagiar
09 Jul, 2024

Questor: Keep a keen eye on this investment trust about to hit the FTSE 100
The Telegraph’s Questor Column takes a closer look at the latest headline-grabbing deal in London’s investment company space, the proposed combination of long-established global trusts Alliance and Witan. As the article explains, the idea behind the deal is to create a one-stop shop, where investors can gain all their equity exposure via the new trust which will be known as Alliance Witan. Certainly, the two trusts appear a good fit with both adopting a multi-manager approach, whereby external fund managers are mandated to run the bulk of the two funds assets.

With both Alliance and Witan having market caps of over £1billion, the combined £5billion plus fund will likely be a shoe-in for inclusion in the FTSE 100. Promotion to London’s top-tier index not just a nice-to-have. The fund’s profile will be raised, making it easier and likely cheaper to trade in the shares. FTSE 100 inclusion will also put the fund on the radar of a deeper pool of investors. Those investors will also benefit from lower costs as management fees are to be reduced so that total ongoing charges will fall to under 0.6% a year, compared to Witan’s current 0.76% level and Alliance’s 0.62%.

As for performance, Alliance has the upper hand. Since April 2017 when Alliance adopted its multi-manager approach, the fund has grown assets by 102%, or 10.2% a year. That’s comfortably above Witan’s 60% return or 6.8% per annum. All of which leads Questor to conclude ‘investors should put Alliance Witan on their watch lists. A weakening in the share price before or after the transaction completes could provide a good buying opportunity’.

MoneyWeek: Should you invest in HarbourVest ?


The MoneyWeek article opens with a mystery. Private equity fund of funds HarbourVest Global Private Equity’s (HVPE) NAV is up +251% over 10 years and has doubled over five years. Yet the shares trade at a 40% discount to net assets. Why?

One possible answer is that those net assets are overvalued. Quite possible were stock markets selling off, the world hurtling towards recession and the portfolio’s holdings trading on steep valuations. But as MoneyWeek points out ‘markets have been rising steadily against a benign economic backdrop. The average valuation multiple for a representative sample of the portfolio at year-end was a reasonable 14 times cash flow, average cash flow having increased 15% in the year.’ And on valuations, MoneyWeek highlights that during the year ended 31 January 2024, around 10% of HVPE’s portfolio was sold at an average 24% premium to carrying value, suggesting a conservative valuation approach.

The article then runs through a check-list in an attempt to explain that hefty discount such as lack of buybacks, poor liquidity in the shares and high costs. No lack of buybacks though. Since September 2022, HVPE has bought back 2.9 million shares or nearly 4% of those in issue. And with the board allocating $150-$250 million to a buyback pool, more buying appears to be on the table. Nor should the liquidity of the shares be an issue as the private equity fund has a market value of £1.840 billion. As for costs, total expenses in the latest year came in at 1.8% of the average NAV, but as MoneyWeek points out ‘Managing private equity is expensive, with costs more comparable to a listed company than to a fund investing in listed shares, but the returns are significantly higher.’

So, unable to come up with a satisfactory explanation for that HVPE discount, MoneyWeek concludes ‘Within a very undervalued sector, the combination of HVPE’s very strong performance record and inexplicably high discount is hard to beat – especially with the board trying to narrow the discount and add to NAV by buying back shares’.

A lifelong second income for just £3 a day

Here’s how I’d do it.

Story by Harvey Jones

by The Motley Fool

Times are tough but investing a tiny sum such as £3 a day towards building a second income for retirement is well worth the effort.

Everybody needs a bit of cash in an easy access account for emergencies. But for longer-term retirement savings, I believe my money will work a lot harder in stocks and shares.

Stocks beat shares over time

Over the last 20 years, the FTSE 100 has delivered an annual average return of 6.89% a year. That beats even the very best cash savings accounts. It also gives me a better chance of protecting the value of my money against inflation.

Over the long run, history shows that equities beat almost every other type of investment. Better still, by purchasing them inside the £20,000 annual Stocks & Shares ISA allowance, I can take all of my capital growth and dividend income free of tax.

Please note that tax treatment depends on the individual circumstances of each client and may be subject to change in future. The content in this article is provided for information purposes only. It is not intended to be, neither does it constitute, any form of tax advice. Readers are responsible for carrying out their own due diligence and for obtaining professional advice before making any investment decisions.

If I invested £3 a day from age 25 and it grew at 6.89% a year, I’d have an impressive £453,989 by age 65. That’s not a bad return from £3 a day. This assumes I increase my contribution by 5% each year, to keep pace with prices.

If I was 45, my £3 a day would have much less time to compound. It would be worth just £70,499 by 65. That is better than nothing but it shows the cost of putting off investing. If I had no savings at 45, I’d be looking to invest much more than £3 a day. If I put away £10 a day instead, I’d have £234,831 by age 65.

These figures are not guaranteed. Stock markets are volatile, and nobody knows how well they will perform in future.

I like high-yield shares

Either way, I would reinvest all my dividends back into my portfolio while I was working, then draw them as income after retirement

So how much of a second income can a portfolio of shares generate? Let’s say, to keep things simple, that I had £100,000. Placed in FTSE shares that yielded on average 7% a year, I’d have a second income of £7,000.

Next year, the FTSE 100 Index is forecast to yield 4.4%. That would generate income of £4,400 if I placed my £100k into a tracker fund.

Crucially, in both cases I’d still have my capital intact. Its value will rise and fall in line with the stock market. However, history shows that in the long run it should rise and, with luck, so should my second income.

Updated Snowball

I’ve bought for the blog portfolio 11038 shares in FSFL for 10k.

Declaration of Dividend

Foresight Solar is pleased to announce the first interim dividend, for the period 1 January 2024 to 31 March 2024, of 2.00 pence per ordinary share. The shares will go ex-dividend on 25 July 2024 and the payment will be made on 23 August 2024 to shareholders on the register as at the close of business on 26 July 2024.

The Board confirms its annual dividend target of 8.00 pence per ordinary share for the 2024 financial year.

Yielding 8.8%

« Older posts Newer posts »

© 2026 Passive Income Live

Theme by Anders Noren — Up ↑