Investment Trust Dividends

Month: September 2026 (Page 4 of 7)

Insiders Only Buy, Never Sell

Insiders Only Buy, Never Sell, This 12% Monthly Payer
Brett Owens, Chief Investment Strategist
Updated: September 9, 2026

Let’s discuss an investor who banks a $34,533 dividend check on the first of every month. From one fund alone!

Think you can survive on $34,000 in passive income per month, too? From just one position?

Of course you do. And right now, you and I can buy this monthly payer for a better price than the big shot! (Who, by the way, keeps working long days—not what many of us would do with a $34K monthly paycheck!)

I’m talking about Emmanuel “Manny” Roman, the CEO of PIMCO. Yes, that PIMCO, the most famous bond shop in the world. It was the old home of Bond King Bill Gross, who has since been deposed.

Manny grew up in Paris, the son of two artists. He spent 18 years at Goldman Sachs. Now, he runs PIMCO.

In other words, a regular dude just like you and me, right? Ha! Yeah right, but here’s the thing. We can learn from Manny and lock in a better yield for ourselves than he did!

First, we learn. Then, we earn. Let’s look at Manny’s previous buys. In September 2022, the S&P 500 had its worst day since June 2020, in the thick of COVID. Manny’s fund was down 25% from its IPO. Most bond funds were getting waxed as the Fed jacked up interest rates and the bond market feared forever inflation.

PIMCO’s big boss bought the fear then and also the following spring. Regional banks like Silicon Valley Bank were going down—Manny bellied up to buy 100,000 more shares.

And he never sold. Neither has any other PIMCO insider: Not one has reported selling a PDO share in five and a half years of filings. It’s not that he won’t sell. Back in 2019 our hero unloaded 100,000 of another PIMCO fund, this one at a loss. Shot it down in cold blood.

Yet this fund, he’s put $4.3 million into! (I know, relatable, right? Ha.)

The fund is our own PIMCO Dynamic Income Opportunities Fund (PDO), which we bought in May 2023, a little after Manny, at a few dimes higher.

Manny’s average cost is $16.04 per share, giving him a 9.6% yield. But PDO, as I write, yields 12%, nearly three points above Manny’s dividend average!

The thing is, you and I can buy PDO just like a normal stock. It’s a closed-end fund, or CEF, which means it trades on the exchange. The keyword here is “closed,” which means it doesn’t create and redeem shares on demand like an ETF. So PDO can trade above or below what the bonds in its portfolio are actually worth (net of any debt). When it trades below that, you and I score a sweet deal because we secure more dividend for each dollar we invest—and snare a margin of safety to boot.

The fund has paid $0.1279 on the first of the month every month since July 2022. PDO usually trades at a premium because, hey, who doesn’t like a big yield? But it actually sits at a discount right now. Unusual.

PDO owns bonds that are spicier than your stodgy old pension fund can usually buy: mortgages, overseas bonds, and “junk-rated” company bonds. These tend to be below investment grade. Pension mandates usually bar them, so the value gets left on the table. We snatch it up!

How does the yield reach 12%? PDO borrows money, or in suit-speak, uses leverage to buy more bonds, borrowing 38 cents of every dollar it invests. Money costs about 5% today. Not exactly low cost, but it’s a winner for PDO because it buys bonds that yield more than 5%.

Now, why does PDO trade below what its bonds are worth, for 98 cents on the dollar? This dividend payer is a relative minnow at nearly $2 billion in assets, too small for the Wall Street whales to consume.

If you are Goldman Sachs and you’re looking to put your wealthy clients into it, you can’t just splash $50 million to $100 million in there, right? (About $8 million worth of PDO trades per day, so a $50 million order is a full week’s worth of volume! Too heavy for the market to absorb. It would push the price up and the yield down!)

But it’s plenty liquid for us—and Manny, who invested $4.3 million. We don’t move the price.

We can invest like Manny. You can put $10,000, $20,000, $50,000, or even $100,000 into this fund, no problem on the liquidity side. At the current 12% yield, every $100,000 invested mails you about $1,030 a month.

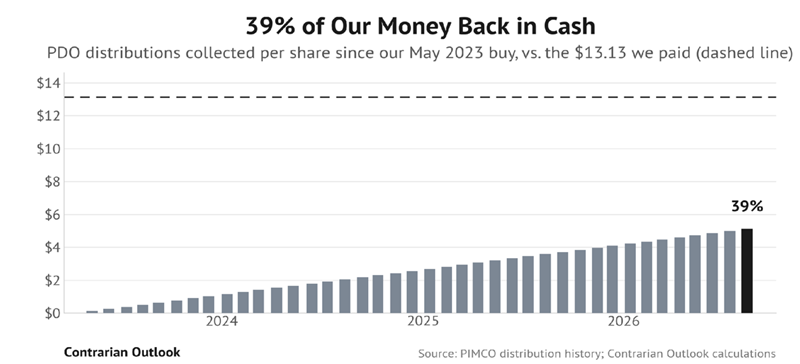
It’s worked out well for my Contrarian Income Report subscribers. We bought the fund in May 2023, after Manny’s most recent purchases. We’ve collected 40 dividend payments to date, $5.12 on our initial purchase of $13.13. That’s a sweet 39% of our money already back in cash.
The PDO “payout sausage factory,” though, is not for the faint of heart. Its income is lumpy, sometimes way over what it needs to pay us and sometimes below. For example, one-quarter of August’s check was investors’ own money handed back, called return of capital.

Coverage was ugly in January, when PDO earned only about 60% of its payout. Over the last three months it earned well above 100%. That’s what we care about. And you can be confident we watch Manny’s action closely for clues of any changes.

For now, the insider money says: “Buy!” His colleague Dan Ivascyn—Bond King Bill Gross’s successor—also has a big stake generating $31,975 in monthly divvies. That’s two huuuuge votes we’re happy to side with.

The fund now trades near fair value of its bond portfolio. Historically, it’s fetched a premium. Let’s take the cue from Roman and Ivascyn. After all, Manny’s check lands on the first of the month. So will yours, if you buy PDO.

Inefficient markets like the one we have in CEF land are key to retiring on monthly dividends, and PDO is not alone.
SUPeR

SUPERMARKET INCOME REIT PLC  

(“SUPR”, or the “Company”)  

ACQUISITION OF SIX NEW ASSETS

Supermarket Income REIT plc (LSE: SUPR, JSE: SRI) announces that it has acquired six high quality grocery assets for £104 million.

Together with the announcement on 15 July 2026 that the Company has exchanged contracts to acquire a portfolio of three supermarkets for £118 million, the proceeds from the £100 million equity raise in July 2026 have now been fully deployed, at an average net initial yield of 6.6%[1] and a weighted average unexpired lease term (“WAULT”) of 10 years.

Sainsbury’s, Macclesfield

•     74,000 sq. ft. supermarket with a Click & Collect facility and home delivery vans

•     Triple-net unexpired lease term of 13 years

•     Annual RPI-linked rent reviews (subject to a 4% cap and 2% floor), with rent of £37 per sq. ft.

Morrisons, Leeds

•     80,000 sq. ft. supermarket with a Click & Collect facility and home delivery vans

•     Triple-net unexpired lease term of 13 years

•     Five-yearly RPI-linked rent reviews (subject to a 4% cap and a 0% floor), with rent of £21 per sq. ft.

M&S anchored retail park, Nottinghamshire

•     Fully let 50,000 sq. ft. scheme includes national retailers B&Q, Costa, Greggs and Mountain Warehouse

•     Triple-net leases with a weighted average unexpired lease term of five years

•     Five-yearly open market rent reviews, with rent of £18 per sq. ft.

Co-op, Birmingham

•     4,000 sq. ft. foodstore with a triple-net unexpired lease term of eight years

•     Five-yearly RPI-linked rent reviews (subject to a 4% cap and 1% floor), with rent of £20 per sq. ft.

M&S, Glasgow[2]

•     10,000 sq. ft. scheme anchored by M&S with a triple-net unexpired lease term of six years

•     Five-yearly open market rent reviews, with rent of £20 per sq. ft.

Sainsbury’s grocery distribution centre, Avonmouth2

•     67,000 sq. ft. distribution centre let to Sainsbury’s, with a triple-net unexpired lease term of 14 years

•     Five-yearly open market rent reviews, with potential to capture reversion

Rob Abraham, CEO of Supermarket Income REIT, commented:

“These acquisitions add six high-quality grocery assets to our portfolio, marking the completion of the deployment of the proceeds of our £100 million equity raise in July. We are pleased to have delivered this compelling pipeline of acquisitions within two months. Importantly, these acquisitions represent further progress in our strategy to diversify the portfolio, adding grocery distribution and additional exposure to grocery-anchored retail, to our core UK foodstores, which span larger, omnichannel supermarkets through to convenience.”

Three cheap UK equity income trusts ?

By Helen Kirrane IC

Published on September 9, 2026

The dependable portfolios of UK equity income investment trusts, filled with financial, energy and mining companies, look especially appealing in the aftermath of the July sell-off of AI stocks.

Trusts in this sector tend to have low exposure to the US, and there is a broad array for investors to choose from – some of which have performed remarkably well over the long term. Temple Bar (TMPL) and Law Debenture (LWDB) have comfortably beaten their FTSE All-Share benchmark over three, five and 10 years. Meanwhile, the venerable City of London (CTY) has raised dividends every year for almost 60 years, and the shares are up by more than a fifth in the past year.

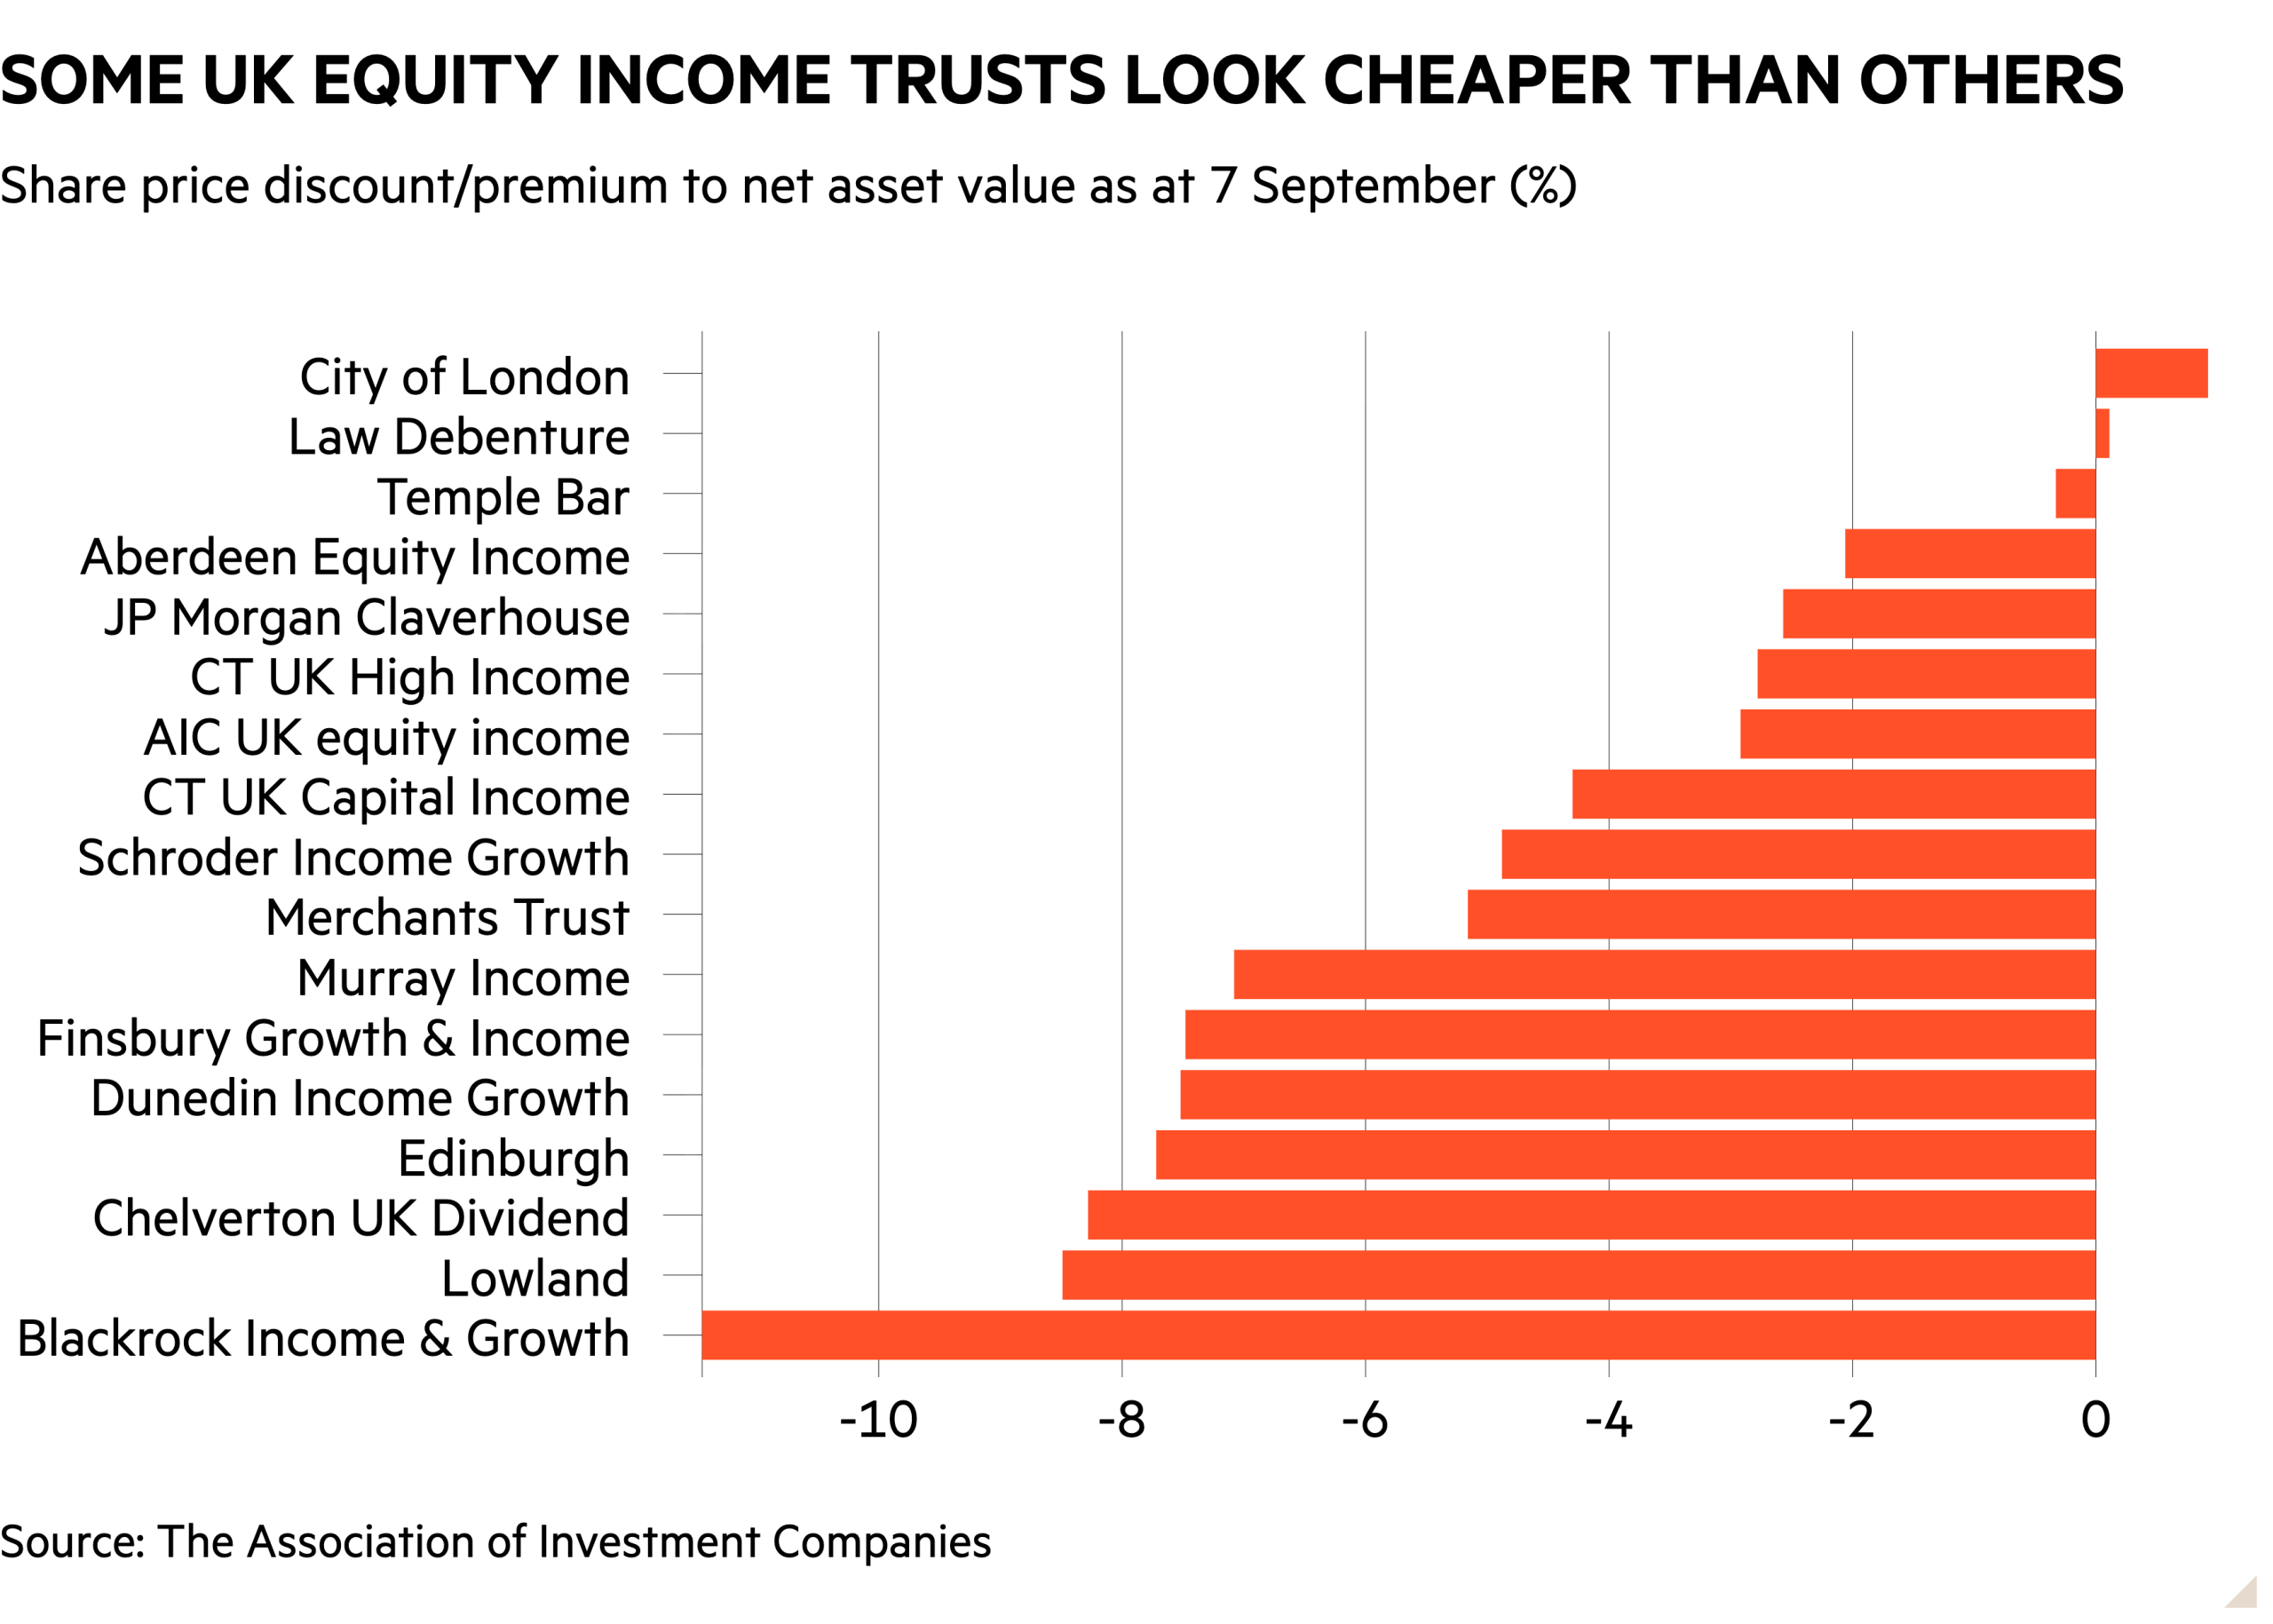
However, this performance and income record tends to come with a price. The three trusts all trade very near their net asset value (NAV), or at a small premium.

Bar chart of Share price discount/premium to net asset value as at 7 September (%) showing Some UK equity income trusts look cheaper than others

Some trusts in the sector look remarkably cheap by comparison. Lowland (LWI) has one of the widest discounts at 8.5 per cent, despite the fact that it has been the second-best-performing trust on a share price basis over one and three years, helped by its value style.

It’s worth noting that Lowland and Law Debenture invest in a number of the same holdings, with 78 per cent of their portfolios overlapping according to Winterflood. This is perhaps to be expected given they are run by the same team at Janus Henderson. However, Law Debenture is unique because it generates a good chunk of its income from the independent professional services business it owns

Dunedin Income Growth (DIG), run by Aberdeen, also looks cheap on a 7.5 per cent discount, and offers the highest yield in the sector at 6 per cent (stripping out the tiny £35mn Chelverton UK Dividend (SDV)). This is inflated by an enhanced dividend policy that sees it pay out 6 per cent of its NAV, partly from capital when necessary.

These insights do not constitute advice and should not be relied upon by users in making any specific investment or other decisions.

A high yield can’t do all the heavy lifting, though. The trust has fallen well behind the FTSE All-Share over the past five years as its quality style has not delivered, so the discount may be more warranted in this case. As James Carthew, head of investment companies research at Quoted Data, notes, “There is a fairly strong correlation between trusts on wide discounts and those with poor returns over three to five years.”

One of the largest trusts in the sector, Edinburgh Investment Trust (EDIN), also has one of the biggest discounts, at 7.7 per cent. Like Dunedin, the trust has a quality tilt, which has caused it to underperform. It also has exposure to software and data stocks that are perceived to be threatened by agentic AI, with technology representing 12 per cent of its portfolio as at the end of August.

For the equity income trusts trading well below their NAV, a continued warming of sentiment towards UK equities could prove a boon. Emma Bird, head of investment trust research at Winterflood, says: “The investment trusts could benefit from this increased demand [for the asset class] in terms of a re-rating of their shares, providing a double whammy of strong NAV performance and discount tightening.”

Of course, when it comes to discounts, what goes down can come back up, but that doesn’t mean it always will. Positive sentiment towards the UK can only do so much: for the trusts whose strategy has struggled, an improvement in NAV performance will be crucial to narrow the discount.

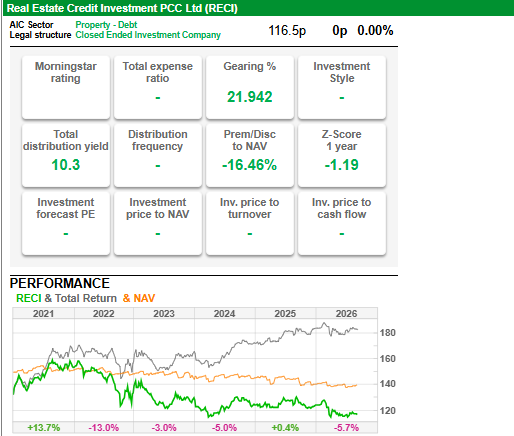
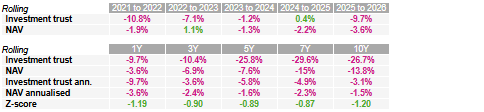
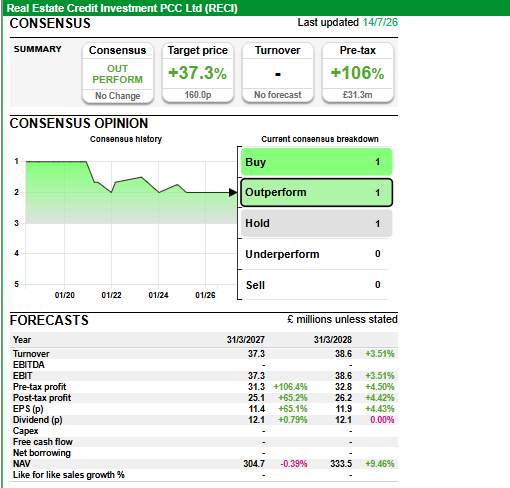
RECI

Remember that you shouldn’t trade based on target prices as they are unlikely to be achieved. The Trust is held in the SNOWBALL as the loans are secured on property and to re-invest the dividends in the higher yielding shares held in the SNOWBALL.

Canada beyond the headlines.

Canada beyond the headlines: the case for energy, financials, and real estate

Last updated: 12th August 2026 |

Author: Cameron MacDonald

  • The Middlefield Canadian Enhanced Income UCITS ETF (MCTP) is positioned across several of the themes discussed in the article, including Canadian energy, financials and real estate.
  • Its active approach aims to identify dividend-paying companies with strong balance sheets, durable cash flows and the capacity to grow distributions.
  • Exposure to disciplined energy producers may allow the portfolio to benefit from stronger commodity prices without relying on aggressive capital expenditure. 
  • Holdings across financials and real estate provide access to resilient bank earnings and the potential benefits of a future interest-rate easing cycle.
  • Canada’s economy may be more resilient than negative headlines around tariffs, unemployment and inflation suggest.
  • Higher energy prices could support Canadian producers, while the country’s major banks continue to grow profits and dividends.
  • Lower interest rates could provide a catalyst for Canadian real estate and REIT valuations.
  • Together, these sectors offer a potentially more diversified alternative to a US market heavily concentrated in technology, although risks remain.

Is Canada’s economy stronger than the headlines suggest?

For much of the last year, the discourse surrounding the Canadian economy has been focused on what’s wrong: US tariffs, a soft labour market, and a war in the Middle East pushing the cost of fuel. However, beyond the headline gloom there is a more constructive narrative. While the US is dominated by a select few technology names, Canada has a more diversified structure across finance, real estate and energy.

On July 15 2026, the Bank of Canada held its policy rate at 2.25% for a fifth consecutive time.[1] While the immediate picture appears less than ideal, business investment intentions have climbed to their highest level since trade tensions began, and export volumes have already risen back above where they stood before the 2024 US election.[2] The one genuine area of concern – inflation rising to 3.2% in May – can be traced directly to gasoline prices tied to the US and Israeli war on Iran, and not a broader loss of price control.[3]

This is further supported by Ottawa’s own economic outlook. While goods exports remain below pre-tariff levels, this is stabilising as firms lean on Canada-United States-Mexico Agreement (CUSMA) exemptions and diversify away from the U.S – a key example is that non-U.S. goods exports are up almost 36% since 2024.[4] [5] Alongside this promising data, the Bank of Canada’s own data shows growth near flat in the first quarter before an estimated rebound to +2.5% in the second, which coincided with a rise in headline inflation, mainly tied directly to gasoline prices rather than a broader issue.[6]

 “RBC Economics summarised it well ‘the economy is bruised, not broken⁷”

Canadian goods exports (month-over-month)

Canada Article

Source: Trading Economics. Data from 31.05.2023 – 31.05.2026. For illustrative purposes only.

Could Canada benefit from higher global energy prices?

This economic adjustment is most visible in energy. As a major net exporter, Canada is one of the few developed economies that could potentially benefit from the war in the Middle East. Producers including Cenovus, Canadian Natural Resources and Suncor have all been flagged as direct beneficiaries of the spike in fuel commodities.[8] Industry estimates cited by BOE Report point to a “massive” uplift in 2026 cash flow compared to 2025, with CEO of Tamarack Valley Energy forecasting it will likely be somewhere in the region of “C$1 billion”.[9] The Montreal Economic Institute frames this as a structural repricing of Canada as a more stable, reliable supplier to allies compromised by Middle East volatility.[10]

Why are Canadian banks continuing to grow profits and dividends?

Financial services companies comprise a large section of Canada’s economy – accounting for about 7.4% of total GDP.[11] The Big Six banks grew their profits in the second quarter compared with the same three-month period a year ago- with TD Bank Group, Royal Bank of Canada (RBC), Bank of Nova Scotia (BNS), BMO Financial Group and National Bank of Canada all hiking their quarterly dividend.[12] RBC alone lifted its payout by 7% and expanded its buyback programme.[13] While trade uncertainty and elevated unemployment remain active risks, the previously delineated data suggests the sector is not (yet) seeing credit deterioration that heavier tariff exposure might suggest.

Could lower interest rates unlock value in Canadian real estate?

Real estate – including Real Estate Investment Trusts (REITs) which sit alongside utilities as some of the markets most rate-sensitive dividend paying assets – stands to directly benefit if ‘the Bank’s’ hold gives way to cuts in interest rates. Kalkine’s analysis notes that a shift towards growth could be a catalyst for the REIT sector,[14] while Nareit’s mid-year update points to REITs outperforming broader equity markets by a “sizeable margin” as the divergence between the two’s valuations have started to converge.[15]

What could this mean for investors?

While these sectors are promising, it does not erase some real challenges – unemployment is sitting near 6.5%, and trade negotiations remain unsolved.[16] But the combination of positive signals surrounding financials, real estate, and energy indicates structural tailwinds. Energy producers are taking cash flow without over committing to new capital intensive projects. Banks are growing earnings and dividends even as rates are held against a soft labour market. Real estate, still the most overtly cyclical of the three, is primed for a catalyst – a genuine easing cycle that could allow borrowing costs, and REIT valuations, to move together once more. For investors looking beyond a tech laden US market, there is a potentially more diversified case worth keeping note of, despite it not being a story of universal strength.

Middlefield Canadian Enhanced Income UCITS ETF (MCTP) is Europe’s first actively managed Canadian equity income ETF. The fund is focused on large-cap, high-quality companies in Energy Production, Pipelines, Financials, and Real Estate sectors. The ETF primarily invests in companies within our key sector weights with a proven track record of growing dividends, providing unique exposure to Canada’s dividend-growth leaders in a UCITS ETF.

The ETF is managed by Middlefield, an independent equity-income manager with over 45 years of experience running award-winning Canadian and UK dividend strategies.

Key risks

  • Past performance is not indicative of future performance.
  • Energy infrastructure companies may be subject to specific industry and sector risks such as commodity price fluctuations and decrease in demand for energy during a recession.
  • The return on investment in energy infrastructure companies may be influenced by fluctuations in energy prices or changes to the US economic situation.
  • The Sub-Fund’s assets will be actively managed by the investment manager who will have discretion to invest assets to achieve the investment objective. There is no guarantee that the Sub-Fund’s investment objective will be achieved based on the investments selected.
  • When you invest in ETFs your capital is fully at risk and may not get back the amount originally invested.
  • Exchange rates can have a positive or negative effect on returns.
  • The value of equities and equity-related securities can be affected by daily stock and currency market movements.
  • Please note this is not an exhaustive list of risks. Other risks may apply and can be found in the Prospectus.

IMPORTANT INFORMATION This document is approved for professional use only.

Disclaimers

This material does not constitute a marketing document. It is not an invitation to invest but to be read for educational purposes only. Past performance and forecasts are not reliable indicators of future results.

The Canadian market provides significant exposure to energy, financials and real estate, offering a more diversified sector composition than the technology-heavy US market. Although economic risks remain, these sectors may benefit from stronger commodity prices, resilient bank earnings and a future interest-rate easing cycle.

« Older posts Newer posts »

© 2026 Passive Income Live

Theme by Anders NorenUp ↑