
2 Stocks To Build Wealth For Decades
Nov 18, 2026
Rida Morwa
Investing Group Leader
Summary
- Compounding turns small, consistent gains into substantial wealth over time, rewarding businesses and investors who build patiently.
- Asset management and real estate offer two distinct paths to compounding, driven by recurring income, reinvestment, and disciplined growth.
- We discuss two picks that demonstrate expanding cash flows and deliver growing dividends along the way.
- Looking for a portfolio of ideas like this one? Members of High Dividend Opportunities get exclusive access to our subscriber-only portfolios.
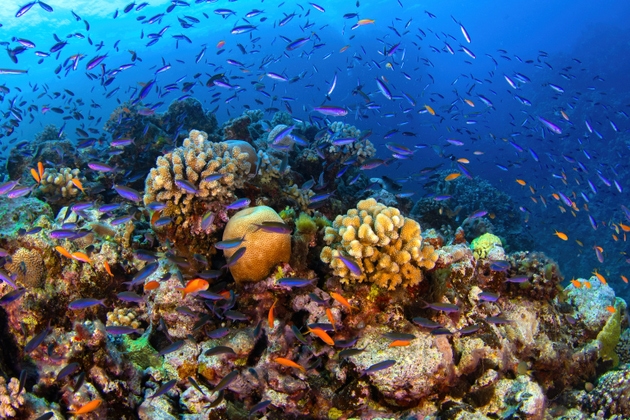
Co-authored with Hidden Opportunities
If you give it some thought, you will recognize that some of nature’s most fascinating ecosystems developed through millions of tiny contributions, repeated over and over, across a very long period of time.
A coral reef is one of the best examples to illustrate this. That beautiful underwater ecosystem people see today began with tiny soft-body organisms called coral polyps. Each one of these polyps is extremely small, and as they grow, they extract calcium carbonate from seawater and secrete this compound to build a hard skeleton around the base of their bodies, anchoring them to the reef. As generations of coral grow and die, these hard skeletons remain and accumulate, expanding the physical structure of the reef to become an enormous underwater ecosystem. The Great Barrier Reef off the coast of Queensland, Australia, is the world’s largest coral reef system and began forming about 6,000 to 8,000 years ago. Coral reefs are a living, constantly evolving ecosystem, where new generations emerge while older coral dies to become a foundation to support future growth.
This is perhaps one of the most beautiful demonstrations of compounding. Small contributions that accumulated consistently over long periods created something extraordinary. The same principle applies to investing. Companies don’t need to deliver massive earnings beats in any single quarter or year to create significant shareholder value. Often, successful businesses are those that consistently reinvest their earnings, steadily expand their operations, and build upon the cash flows generated. Over time, these incremental gains can become increasingly meaningful, creating a powerful engine of wealth creation.
Today, we’ll look at two companies that demonstrate this principle in very different ways. Let’s dive in!
Pick #1: O – Yield 5.6%
Realty Income Corporation (O) is the largest net-lease REIT in the world that owns and operates a portfolio of 15,536 properties, leased to 1,842 clients operating in 96 industries. The company ended Q3 with a weighted-average remaining lease term of 8.5 years, and a portfolio occupancy of 98.8%, with 182 properties available for lease or sale. O’s occupancy level was sequentially flat and marginally up from 98.7% at the end of Q3 2025.
In August, the REIT closed $1 billion in 3.750% convertible senior notes due 2031 and used $33.2 million of the net proceeds to repurchase 3 million shares of common stock. This is an interesting move, as the REIT borrowed at a very advantageous cost to repurchase its 5.7% yielding shares at a time when REIT valuations are weaker. The newly issued convertible notes have an initial conversion price of $72.72/share, but bond holders can convert before May 2031 only if O’s common stock trades above $94.54/share for at least 20 of the final 30 trading days of a calendar quarter. It is also noteworthy that O used $33.2 million of the net proceeds to establish a capped-call structure to protect against potential dilution up to $83.55/share. The REIT plans to use the rest of the proceeds for general corporate purposes. O maintains an investment-grade “A” rated balance sheet with net debt to annualized pro forma Adj. EBITDAre (Earnings Before Interest, Taxes, Depreciation, and Amortization for Real Estate) at 5.4x.
During Q3, O invested $2.2 billion to acquire 119 properties with a weighted average lease term of 9.3 years. This transaction carried an initial weighted average cash yield of 6.8% and brought the YTD acquisition total to $5.5 billion for 365 properties. Management reaffirmed its $10 billion investment volume target for 2026, implying approximately $4.5 billion in additional investments during Q4. This suggests a substantial pipeline of acquisition opportunities heading into year-end, potentially including larger portfolio transactions. Source

O began the third quarter with 188 properties available for lease. During Q3, the REIT experienced 274 lease expirations, re-leased 213 to the same client and 9 to new clients, and disposed of 58 vacant properties, ending the quarter with 182 properties available for lease (or sale). O reported a 103.5% rent recapture rate, meaning the REIT re-leased its properties for rent 3.5% higher compared to what the previous tenants were paying.
U.S. Core Plus Fund, which is an institutional real estate investment fund managed by Realty Income, allowing the REIT to collect fees on third-party capital. During Q3, the fund’s AUM increased to $3.52 billion, up 32% YoY, and the fund acquired 18 properties for $417.8 million, bringing YTD acquisitions to 76 properties worth $1.26 billion. The REIT’s management fee income grew to $3.8 million (up from $3.2 million in Q2). Today, O’s the high-margin and capital-light U.S. Core Plus Fund fee income is about 0.5% of the REIT’s quarterly dividend, but we expect this to rapidly rise in the years ahead.

During Q3, the REIT reported a solid quarter with AFFO per share rising 3.7% YoY to $1.12. Management also raised their 2026 AFFO per share guidance to $4.45 to $4.46/share. In September, the REIT raised its monthly dividend by 0.2% to $0.2715/share ($3.258 annualized), marking 31 years of consecutive payout raises. This calculates to a 5.7% yield and enjoys a comfortable 73.2% payout ratio based on the company’s AFFO guidance.
Pick #2: BAM – Yield 3.9%
Brookfield Asset Management (BAM) is a leading global alternative asset manager that ended its third quarter with $1.3 trillion in assets under management and $682 billion in FBC (Fee-Bearing Capital), up 13% YoY. Credit represents $341 billion, or 50% of BAM’s FBC, implying a substantial allocation to private credit and other credit-related strategies. However, it is important to keep in mind that the company’s credit strategies remain concentrated in opportunistic credit, real asset lending, and asset-backed finance, rather than traditional sponsor-backed direct lending. It is also important to remember that BAM is not a traditional lender but an asset manager. The company is not deploying $341 billion of its own capital into loans; rather, it manages capital on behalf of institutional and individual investors across a variety of credit strategies. Source

A significant part of this platform comes from Oaktree Capital Management, which Brookfield fully acquired in July 2026. Oaktree is particularly well known for its expertise in distressed and opportunistic credit, where it invests in the debt of financially troubled companies, often at deeply discounted valuations. The company typically negotiates favorable terms, securing senior claims and collateral protections, and participating in corporate restructurings to protect investors’ capital while generating attractive returns when these businesses recover. BAM benefits through recurring management fees and performance-based fees. The risk to BAM from its credit strategies is not widespread defaults but a widespread deterioration in this sector, hurting investor confidence and causing a decline in fundraising.

During Q3, BAM raised $25 billion in capital, bringing its YTD total to $123 billion, and deployed $18 billion into a wide range of global projects and companies. Credit remained one of BAM’s largest business segments, with $341 billion in FBC, up 19.2% YoY. During the quarter, the segment attracted $12.2 billion in capital, reflecting continued investor appetite for BAM’s credit strategies. The company also raised $7 billion in its infrastructure segment, deploying it into U.S. semiconductor fabrication, New Zealand energy infrastructure, AI factories in the U.K., and AI computing infrastructure in South Korea. Notably, BAM’s infrastructure segment attracted a record $50 billion in commitments across different strategies over the past year. BAM’s energy and private equity also raised $4.5 billion in capital, deploying this into clean energy and financial services across global markets.
BAM reported a quarterly FRE (Fee-Related Earnings) of $864 million, up 15% YoY, achieving an FRE margin of 54% (vs. 55% over the past twelve months). The company reported $763 million in DE (Distributable Earnings), also up 15% YoY. It is noteworthy that, as of September 30, BAM had $148 billion in uncalled commitments, with $68 billion not currently earning fees. Once these commitments are deployed, BAM is estimating $680 million in additional revenue.

BAM declared a quarterly dividend of $0.5025/share, payable on December 31st to shareholders of record on November 30th. This calculates to a 3.9% annualized yield. BAM has delivered annual dividend raises since its IPO, and we expect this trend to continue in the years ahead.

Note: BAM is a Canadian C-Corp for tax purposes. While the company declares and pays dividends in USD, the payments are subject to a 15% withholding tax (IRAs are exempt).
BAM maintained $2.1 billion in corporate liquidity at the end of Q3, with $2.4 billion in investment assets. The company’s balance sheet carries an A/A- rating, with a weighted-average tenor of 12.1 years and a weighted-average coupon of 5.388%. Notably, BAM has no debt maturities until 2030.
Conclusion
At High Dividend Opportunities, we focus on quality businesses that generate reliable income, grow their cash flows, and use a portion of it to consistently reward shareholders. Our Income Method emphasizes investments that deliver income today while compounding wealth for the years ahead.
Brookfield Asset Management and Realty Income have both built businesses around recurring sources of income and the ability to expand upon what they have already created. While their approaches are different, the underlying principle remains to build, reinvest, and let time do its work.

Leave a Reply