I’ve bought for the portfolio 12264 shares in GRID
Gresham Storage for 9k.
Yielding around 10% and trading at a discount of 50%.
Bought for the yield so I am content if this
isn’t the bottom of the trend.
Investment Trust Dividends
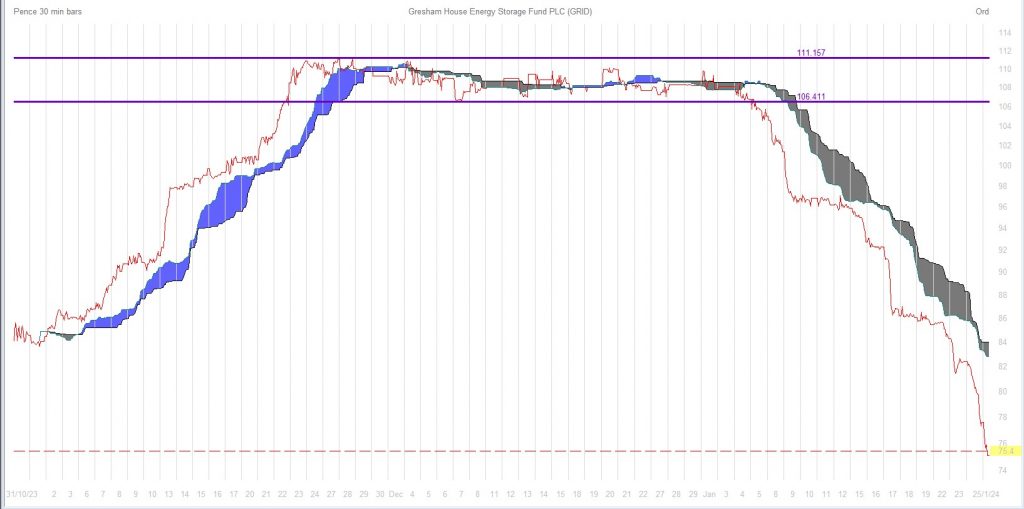
I’ve bought for the portfolio 12264 shares in GRID
Gresham Storage for 9k.
Yielding around 10% and trading at a discount of 50%.
Bought for the yield so I am content if this
isn’t the bottom of the trend.
I’ve sold the portfolio shares in SERE Schroder European
Property for a loss of £55
Total portfolio profit in SERE now £860.00
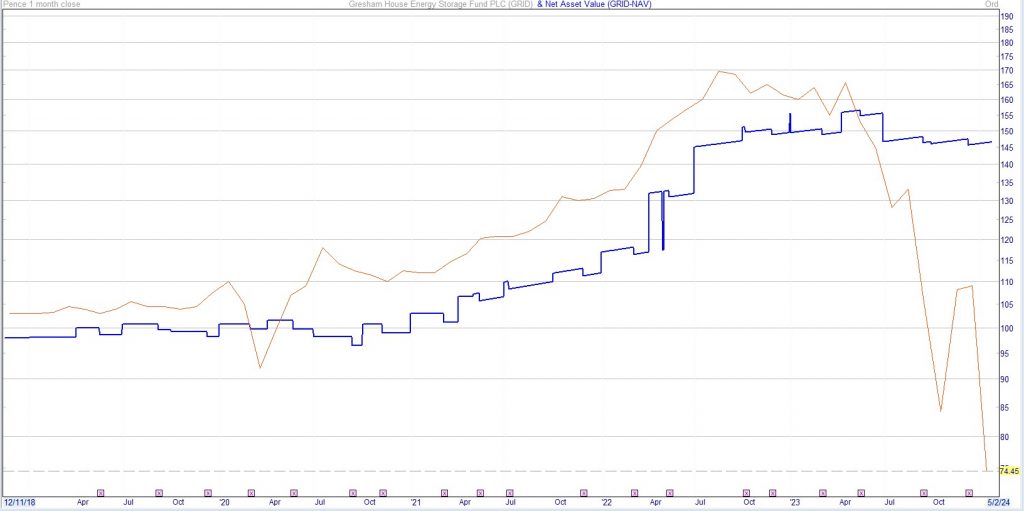
Mr. Market is always right but not always that bright.
With the recent changes to the portfolio, the first quarter fcast, with
two companies still to declare a dividend is £2,299.00
The second quarter target is £2,191.00 which brings the year’s
target to £8764.00 (plus)
A lot of water to flow under a lot of bridges before the target
can become the fcast.
There is currently £115,431.00 invested in the portfolio.
At the end of the ten year plan that figure should grow
to £225,000 invested the value of which is the
unknown. I would guess based on my history of
investing, if the markets are strong at the time
the value will be excess of the total but of
course it could be less if the markets have crashed.
Of course that matters little to u as the plan is to
spend the dividends, with the option to sell a position
if an emergency arises which would be similar to selling ten years
dividends in advance.
With compound interest the most cash is made in the last
years of re-investing so the plan would have kept u out
of the lifestyling disaster.
If the plan falls behind the options will be to
increase the time scale
or
add new fuel to the fire.
The plan fails by the month not the year.
Current dividends received £1,406.14 which is not
indicative for the year but should be ahead of the
fcast at the first quarter.
I have tidied up the Snowball portfolio by buying 989
shares in SERE for £700.00.
There is one more position RECI to be added to then
the decision will be to either re-invest the dividends back
into the Snowball or open a new position.
By then the decision may have been made for me.

Investors had a tough time working out how to make money in 2023.
Uncertainty over the global economy and continuing geopolitical tensions meant that for many the prospect of stock market investing proved very much hit and miss.
Nonetheless, the temptation to take money out of the stock market and put it into high interest savings accounts was strong, particularly with some of the best fixed rate savings deals paying more than 6 per cent.
But those rates are gone now and the top one-year fixed rate deal in
This is Money’s independent best buy savings tables pays 5.3 per cent, with rates on a downward trajectory. pays 5.3 per cent, with rates on a downward trajectory.
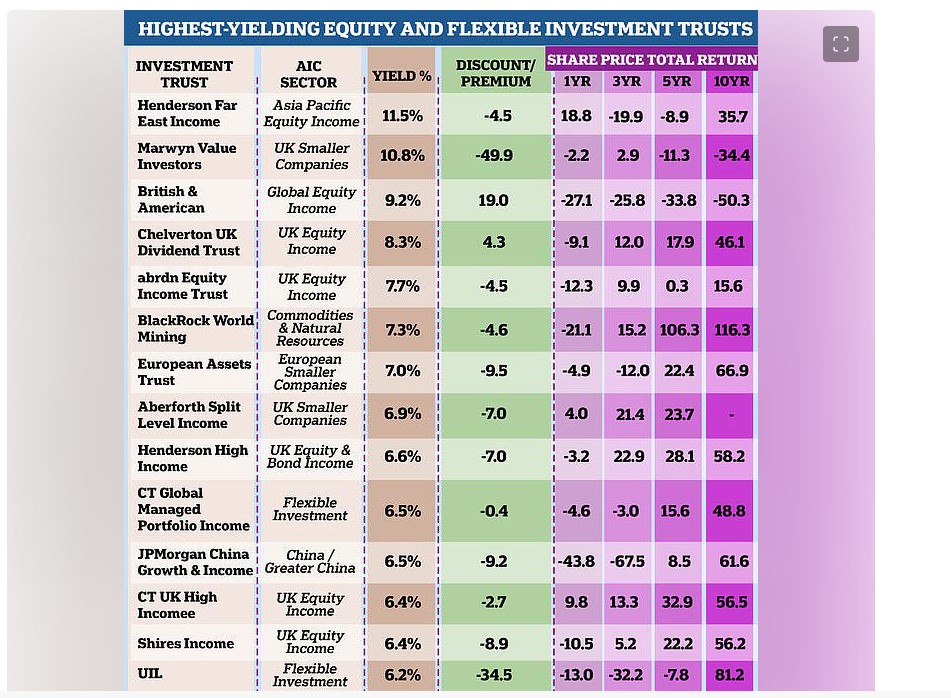
Looking for income?: 48 investment trusts have a dividend yield of over 4% according to new research from the Association of Investment Companies © Provided by This Is Money
Meanwhile, looking at the bigger picture, investing in the stock market has been proven to be the best path to accumulating long-term wealth.
Enter investment trusts – and as savings rates dip, these are looking more attractive.
There are 48 which invest mostly in equities and have a dividend yield of at least 4 per cent, delivering both potential growth and income to investors, research from the Association of Investment Companies shows.
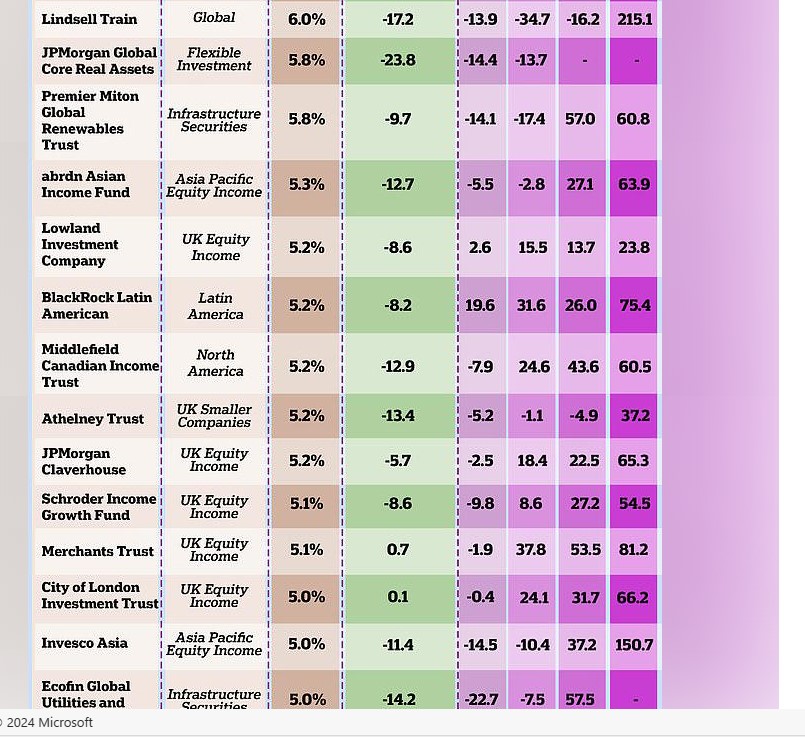
A total of 28 yield 5 per cent or more, so they could deliver an income in excess of interest rates if they start to fall this year.
There are 28 investment companies which have a dividend yield of 5% or more© Provided by This Is Money
Fourteen of the trusts on the 28-strong list are from the UK Equity Income sector, accounting for nearly a third of the highest yielding investment trusts.
The trust with the highest dividend yield is Henderson Far East Income. It invests in Asia Pacific equities and yields 11.5 per cent. Managed by Janus Henderson, it is trading on a 4.5 per cent discount to the value of its net asset value.
Next on the list is Marwyn Value Investors which has a yield of 10.8 per cent and sits in the UK Smaller Companies sector. Managed by Marwyn Investment Management, some of the trust’s holdings include luxury goods companies, such as Le Chameau and software companies like AdvancedAdvT Limited.
Another trust in the top three high-yielders is British & American, which invests in global equities and yields 9.2 per cent.
As UK inflation unexpectedly rose again for the first time in 10 months to 4 per cent, the Bank of England may cut rates later than previously expected.
Some investment trusts have a focus on providing a generous income to investors and the structure of investment companies is a big benefit when it comes to this.
They allow investment managers to hold back up to 15 per cent of the dividends they receive each year from the companies they invest in and build a revenue reserve to smooth payouts in leaner years.
Eight of the highest yielding investment trusts are what the AIC calls dividend heroes, which means they have raised their dividends for at least 20 years in a row.
The highest yielding of these dividend giants is abrdn Equity Income Trust, which has raised its dividend for 23 years and offers a 7.7 per cent yield.
There are a further 13 trusts which have increased their dividend for ten years in a row.
Investment trusts are a popular way for investors to get exposure to stock markets for all kinds of reasons.
They are easy to buy and sell, especially through an online investment platform.
They are managed by an investment manager steeped in market knowledge, hold a range of stocks (diversifying risk) and are not too greedy when it comes to charges.
Investment companies also have structural benefits which help them maintain and grow their dividends year after year. But even with all these compelling factors, there is no guarantee that they will guarantee positive returns year in year out.
Annabel Brodie-Smith, communications director of the AIC says: ‘For investors seeking income, this list of high yielding equity investment trusts is a good place to start.
These investment trusts offer access to equities in a wide range of regions and sectors from the UK and across the globe including commodities, infrastructure and biotechnology.
‘More than a third of these 48 investment trusts have raised their dividends every year for the past ten years, and eight have raised their dividends for 20 years or more.’
Marwyn Value Investors Limited
INTERIM DIVIDEND TO ORDINARY SHAREHOLDERS
The Company is pleased to announce that an interim dividend of 2.265p per Ordinary Share will be paid on 23 February 2024, pursuant to the Company’s ordinary share distribution policy.
The payment of the interim dividend to eligible holders of Ordinary Shares will be effected through CREST or by BACS in the case of holders of depository interests relating to the Ordinary Shares, or by BACS in the case of Ordinary Shares held in certificated form.
Timetable for February Interim Dividend
| Ex-date | 1 February 2024 |
| Record date | 2 February 2024 |
| Payment of the Interim Dividend | 23 February 2024 |
| AEW UK REIT PLC – NAV Update and Dividend ▼ |
AEW UK REIT plc
NAV Update and Dividend Declaration
AEW UK REIT plc (LSE: AEWU) (“AEWU” or the “Company”), which directly owns a value-focused portfolio of 34 UK commercial property assets, announces its unaudited Net Asset Value (“NAV”) as at 31 December 2023 and interim dividend for the three-month period ended 31 December 2023.
Highlights
· NAV of £164.02 million or 103.53 pence per share as at 31 December 2023 (30 September 2023: £167.93 million or 106.00 pence per share).
· NAV total return of -0.44% for the quarter (30 September 2023 quarter: 0.91%).
· 1.59% like-for-like valuation decrease for the quarter (30 September 2023 quarter: 0.70% increase).
· EPRA earnings per share (“EPRA EPS”) for the quarter of 1.83 pence (30 September 2023 quarter: 1.84 pence).
· Earnings constrained by 0.28 pence per share due to two tenants entering administration: Wilko at Union Street, Bristol, and CJ Services at Sarus Court, Runcorn.
· Interim dividend of 2.00 pence per share for the three months ended 31 December 2023, paid for 33 consecutive quarters and in line with the targeted annual dividend of 8.00 pence per share.
· Loan to NAV ratio at the quarter end was 36.58% (30 September 2023: 35.73%). Significant headroom remains on all loan covenants.
· Company continues to benefit from a low fixed cost of debt of 2.959% until May 2027.
· Disposal of Commercial Road, Portsmouth, for £3.90 million.
· £253,656 of additional income secured from three settled rent reviews, as well as a turnover top-up rent.
Laura Elkin, Portfolio Manager, AEW UK REIT, commented:
“We are pleased to report relatively stable earnings for the third consecutive quarter, as the Company’s programme of investing capital in high yielding assets in core urban locations, combined with asset management transactions, continues to sustain income streams and mitigate void costs. Earnings have been maintained by several key rent reviews settled during the quarter, most notably at both of the Company’s more recently acquired assets in Bath. Upcoming lease events, in particular at Central Six Retail Park in Coventry, should enhance earnings going forward.
EPRA earnings per share have been negatively impacted by 0.28 pence due to two tenants entering administration during the period, without which the Company’s dividend would have been fully covered by earnings this quarter. The Company’s portfolio saw a like-for-like valuation decrease of 1.59% during the quarter, symptomatic of subdued deal flow in the UK commercial property investment market. Despite our recent asset management achievements, we remain cognisant of the economic backdrop and its cumulative effect on occupational markets.
The Company has committed to pay its market-leading dividend of 2.00 pence per share this quarter, which we have now paid for 33 consecutive quarters. This has been funded largely by EPRA earnings, which continues to be supplemented by profit crystallised on the NAV accretive sale of assets in prior quarters.
Valuation movement
As at 31 December 2023, the Company owned investment properties with a total fair value of £212.04 million, as assessed by the Company’s independent valuer, Knight Frank. The like-for-like valuation decrease for the quarter of £3.42 million (1.59%) is broken down as follows by sector:
| Sector | Valuation 31 December 2023 | Like-for-like valuation movement for the quarter | ||
| £ million | % of portfolio | £ million | % | |
| Industrial | 77.52 | 36.56 | (0.81) | (1.03) |
| Retail Warehouses | 45.95 | 21.67 | (0.30) | (0.65) |
| High Street Retail | 33.85 | 15.97 | (0.41) | (1.20) |
| Other | 29.12 | 13.73 | (1.25) | (6.14) |
| Office | 25.60 | 12.07 | (0.65) | (2.48) |
| Total | 212.04 | 100.00 | (3.42) | (1.59)* |
* This is the overall weighted average like-for-like valuation decrease of the portfolio.
Portfolio Manager’s Review
Although the Company’s portfolio saw a like-for-like valuation decrease of 1.59% during the quarter, this was largely driven by two of the Company’s leisure assets, Circuit nightclub in Cardiff and Odeon cinema in Southend, which saw relatively larger valuation falls this quarter as a consequence of the increasing trading pressures associated with the cost-of-living crisis and rises in the price of energy and goods. On 15 January Rekom, the UK holding company of our tenant in Cardiff, announced that it had filed notice of intention to appoint administrators to a number of its companies. Given the recent timing of this announcement, the impact on the Company’s asset in Cardiff is yet unknown, however Rekom constituted only 1.6% of the Company’s annual contracted rent as at 31 December 2023.
Our industrial holdings, which comprise circa 37% of the portfolio weighting, generally saw yield softening across the board. Valuation declines, however, were mitigated by ERV growth, a biproduct of the strength of the occupational market in this sector. The Company’s industrial reversionary yield profile as at 31 December 2023 was 9.39%, compared with an initial yield of 7.82%.
Equally critical to the earnings performance has been a range of asset management transactions, with the Company settling several rent reviews during the quarter, most significantly at both of its assets in Bath. At Northgate House, the Company settled Bath Northgate House Centre Limited’s (The Regus Group) outstanding 2022 rent review at £491,400 per annum, an increase of £96,811 per annum (circa 25%). At Cambridge House, following arbitration, the Company settled Novia Financial plc’s outstanding 2021 rent review at £362,400 per annum, an increase of £44,775 per annum (circa 14%).
Both rent reviews add evidence to the strong reversionary potential of the Company’s portfolio. This was further demonstrated by the Company agreeing a £195,505 annual turnover top-up rent for the year to 28 September 2023 for Next in Bromley, in addition to the base rent of £350,000 per annum. This is £85,505 (circa 78%) higher than what was forecast when the property was purchased in November 2022.
Earnings are expected to be bolstered by several upcoming lettings, most notably at Central Six Retail Park, Coventry, where agreements for leases have been signed with: The Food Warehouse (trading as Iceland); Whitecross Dental Ltd (trading as MyDentist); and The Salvation Army Trading Company Ltd. In combination, these lettings are expected to deliver an additional £535,000 of annual contracted rent roll within the next two quarters.
Prospective lettings at three void units: the former Wilko at Union Street, Bristol; the former Mecca Bingo at The Railway Centre, Dewsbury; and the former Sports Direct at Barnstaple Retail Park are advancing well. The re-letting of these units are expected to have completed during the first half of this calendar year, further improving income streams and mitigating the incurrence of void costs, albeit with associated tenant incentives suppressing earnings potential over the short term.
Net Asset Value
The Company’s unaudited NAV at 31 December 2023 was £164.02 million, or 103.53 pence per share. This reflects a decrease of 2.33% compared with the NAV per share at 30 September 2023. The Company’s NAV total return, which includes the interim dividend of 2.00 pence per share for the period from 1 July 2023 to 30 September 2023, was -0.44% for the three-month period ended 31 December 2023.
| Pence per share | £ million | |
| NAV at 1 October 2023 | 106.00 | 167.93 |
| Portfolio acquisition and disposal costs | (0.05) | (0.08) |
| Capital expenditure | (0.05) | (0.09) |
| Valuation change in property portfolio | (2.19) | (3.46) |
| Income earned for the period | 3.42 | 5.42 |
| Expenses and net finance costs for the period | (1.60) | (2.53) |
| Interim dividend paid | (2.00) | (3.17) |
| NAV at 31 December 2023 | 103.53 | 164.02 |
The NAV attributable to the ordinary shares has been calculated under International Financial Reporting Standards. It incorporates the independent portfolio valuation at 31 December 2023 and income for the period, but does not include a provision for the interim dividend declared for the three-month period to 31 December 2023.
Share price and Discount
The closing ordinary share price at 31 December 2023 was 101.0p, an increase of 2.64% compared with the share price of 98.4p at 30 September 2023. The closing share price represents a discount to the NAV per share of 2.44%. The Company’s share price total return, which includes the interim dividend of 2.00 pence per share for the period from 1 July 2023 to 30 September 2023, was 4.67% for the three-month period ended 31 December 2023.
Dividend
Dividend declaration
The Company today announces an interim dividend of 2.00 pence per share for the period from 1 October 2023 to 31 December 2023. The dividend payment will be made on 1 March 2024 to shareholders on the register as at 2 February 2024. The ex-dividend date will be 1 February 2024. The Company operates a Dividend Reinvestment Plan (“DRIP”), which is managed by its registrar, Link Group. For shareholders who wish to receive their dividend in the form of shares, the deadline to elect for the DRIP is 13 February 2024.
The dividend of 2.00 pence per share will be designated 2.00 pence per share as an interim property income distribution (“PID”) and 0.00 pence per share as an interim ordinary dividend (“non-PID”).
The Company has now paid a 2.00 pence quarterly dividend for 33 consecutive quarters, providing high levels of income consistency to our shareholders.
Dividend outlook
It remains the Company’s intention to continue to pay dividends in line with its dividend policy and this will be kept under review. In determining future dividend payments, regard will be given to the circumstances prevailing at the relevant time, as well as the Company’s requirement, as a UK REIT, to distribute at least 90% of its distributable income annually.
© 2026 Passive Income Live
Theme by Anders Noren — Up ↑