Possibly the best risk-adjusted yield in UK equities
After calling the bottom of a three-year downtrend, analyst Edmond Jackson’s share tip has returned 20% in seven months. Here’s what he’d do with them now.
16th October 2026
by Edmond Jackson from interactive investor
Yesterday, I attended a Capital Markets event for Greencoat UK Wind
for the £2.5 billion renewable infrastructure investment trust that is a leader in wind farms.
The purpose was to elucidate how this UK-listed company will apply its strong cash flow in support of durable long-term returns, having generated £1.1 billion since flotation in 2013. A similar amount of self-generated capital is anticipated over the next five years alone.
- Invest with ii: SIPP Account | Stocks & Shares ISA | See all Investment Accounts
Care is needed with well-choreographed City presentations. In a twist on the late comedian Eric Morecambe’s quip in the Grieg piano concerto sketch, “They’re playing all the right notes and in precisely the right order.”
Even so, it bolstered my sense of how applying a “buy” stance at 96p in March (Stockwatch: why I like these two renewable infrastructure funds), when pricing offered an 11.2% yield with cover over 1.2x, was spot-on, and this share offers a good chance of continuing to evolve a bullish “bowl” chart having declined from around 190p in 2022:
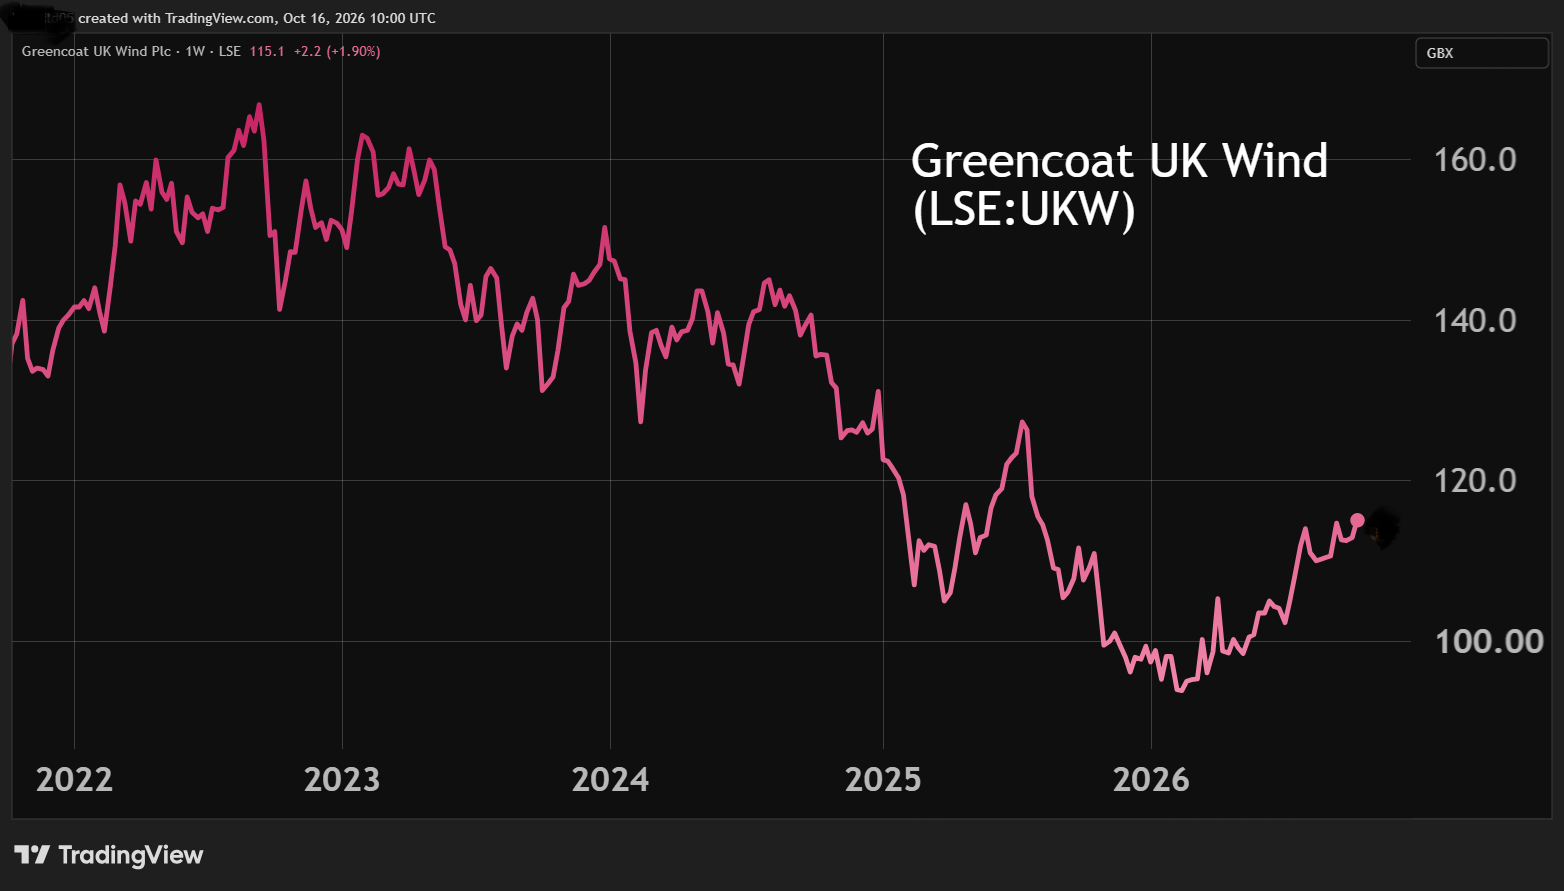
Source: TradingView. Past performance is not a guide to future performance.
Last August, I wobbled – albeit maintaining “buy” – having realised the extent of subsidies not apparent from the accounts. However, that also was with the Reform Party riding high, which supposedly would cut net-zero spending. Interestingly, its waning in the polls has coincided with an uptrend in renewables shares but is not the whole story.
When I alighted on renewables last April, it was in a classic sense of mean-reversion due. Shares looked to have fallen too far amid disillusioned selling, and a market value 0.72x net asset value (NAV) also implied probability of upside. Yesterday’s event was an enabler to appreciate why a current 9.6% yield at 115p is less risky than it seems.
Organic investment and broad tailwinds
Political risk cannot be eliminated, and wind remains prone to weather variations, yet to me the dominating tailwind is electrification. Adoption of electric vehicles (EVs), also the steady migration away from gas and oil for heating, positions a wind operator well in the long run, and in the short term it benefits from high energy prices because of global conflicts.
Reinvestment is vital to sustain shareholder returns but management also sees this as logical for growth rather than, say, prioritising acquisitions.
Yesterday substantiated two key themes: “life-extension” to the assets and “repowering”, which involves upgrading older turbines with far more efficient and powerful models. Both strategic initiatives should benefit NAV while also de-risking yield.
A £100 million boost to cash flow by 2030 was entertained from life-extensions alone. At questions, I elicited a 15% accretion to NAV with regard to the Willow wind farm being showcased and, yes, this was said to be representative of the group portfolio.
Cash flow is to be approximately equally applied for new construction, life extension and repowering. The 30 June interim cash flow statement showed a 22% rise in net cash generated from operations to £244 million with zilch investment then, applied as £114 million on dividends, £47 million finance costs and £30 million on repaying loans.
The right strategy in an overall financial context?
While the presentation focused on actions, we should consider how Greencoat had £1,621 million net debt as of 30 June, its finance costs swiping 27% of operating profit. Net gearing was 56% and in terms of credit risk measures, “moderate risk” requires caution be taken.
Against this, the last six years’ financial record initially seems bumpy, although the oddity of £45.4 million negative revenue last year relates to a £446 million “movement in fair value of assets” under IFRS 13, taken above the line. Otherwise, investment income had been dead-stable at £395 million.
Management embarking on this organic investment programme can therefore seem potentially tight given that financing aspects (dividends, modest buybacks, interest paid and loan repayments) took 79% of first-half net cash flow. Bear in mind, any extended period of low winds might compromise this investment and/or dividends without further recourse to debt. End-June cash was £69 million.
Yesterday also brought news of the acquisition of a remaining 20% stake in a portfolio of UK wind farms for £10.5 million, funded from net cash generation. This being incremental, related to the existing portfolio, rather than any radical acquisitive move. Speaking with management elicited the standard “we look at all opportunities”, but in a debt and dividends context I cannot envisage acquisitions being a plank of corporate development.
Until we see financial proof from this programme it is hard to quantify what extent of growth it can add to shareholder returns, besides enhancing security. When I promptly cross-checked the claim as to 15% NAV accretion via Google AI, for what that is worth it suggested 5% would be an industry norm.
Strong management is a definite advantage
Perhaps they can outperform anyway. Amid informal discussion with renewables analysts and institutional investors, I found consensus in how Greencoat is regarded as the strongest in the sector. The presentation had concluded with a board-type discussion, including the non-executive directors, with Steve Packwood, one of UK Wind’s key managers with Matt Ridley, describing it to me as “certainly keeping us on our toes”.
I got a sense of how, if this operation was an industrial plc – which effectively it is – rather than badged as an infrastructure fund, its share rating would be better.
The last director dealings were in May and June at around 101.5p when the chair of three years bought £50,800 worth and a non-executive director of seven years bought £30,500 worth, hence meaningful rather than token purchases.
Greencoat UK Wind – financial summary
Year-end 30 Dec
| 2020 | 2021 | 2022 | 2023 | 2024 | 2025 | |
| Turnover (£m) | 155 | 423 | 1,025 | 234 | 61.7 | -45.4 |
| Operating margin (%) | 81.3 | 93.0 | 96.2 | 82.8 | 38.3 | 0.0 |
| Operating profit (£m) | 126 | 394 | 987 | 194 | 23.6 | -74.3 |
| Net profit (£m) | 104 | 363 | 954 | 126 | -55.4 | -193 |
| Reported earnings/share (p) | 6.5 | 18.3 | 41.2 | 5.4 | -2.4 | -8.7 |
| Normalised earnings/share (p) | 6.5 | 18.3 | 41.2 | 5.4 | -2.4 | -8.7 |
| Operating cashflow/share (p) | 7.7 | 12.2 | 23.6 | 15.5 | 17.1 | 16.5 |
| Capital expenditure/share (p) | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| Free cashflow/share (p) | 7.7 | 12.2 | 23.6 | 15.5 | 17.1 | 16.5 |
| Dividend/share (p) | 7.1 | 7.2 | 7.7 | 10.0 | 10.0 | 10.4 |
| Return on capital (%) | 3.8 | 9.7 | 20.5 | 3.8 | 0.5 | -1.7 |
| Cash (£m) | 7.9 | 4.8 | 19.8 | 21.8 | 5.8 | 14.2 |
| Net debt (£m) | 1,092 | 945 | 1,081 | 1,768 | 1,754 | 1,706 |
| Net assets/share (p) | 122 | 134 | 167 | 164 | 151 | 133 |
Source: company accounts.
Latest consensus anticipates around £93 million net profit this year, rising to £259 million in 2027 for normalised earnings per share (EPS) of 11.6p, hence a 15-month forward price/earnings (PE) ratio of 9.9x.
Dividend growth is tipped to continue slightly ahead of inflation (although time will tell) with a rise from around 3.5% in recent years to 4% based on an 11.1p dividend in respect of 2027. That would imply a near full payout of earnings, but from the above table you can see a consistently strong cash flow record, hence, barring calamity, the dividend is well-propped.
Is this really the best risk-adjusted yield in UK equities?
I concede that my tease as to the “best possible, double-digit yield” lacks quantitative rigour and testing. I am taking a political view: the right-of-centre vote in British politics is divided between Reform, which is rather losing credibility, and the Conservatives, which are currently somewhat resurgent. That leaves the prospect of Labour propped possibly by the Lib Dems or Green Party. A left-of-centre, climate conscious government is the best scenario for renewable shares.
Current energy policy is most helpful: accelerating electrification to bring down its price relative to gas implies a tipping point, enhancing organic growth. Admittedly, it is hard to predict power prices according to adoption of EVs and heat pumps, but electricity demand in aggregate looks set to rise.
My initial “buy” at 96p related to a sense of market capitulation values in the renewables sector. As I get to know UK Wind in more detail – the presentation being helpful – at 115p I am more comfortable reiterating this, despite a conventional sense that a near double-digit yield flags high risk.
Yesterday’s City event is being rolled over into a 27 October live presentation for individual investors – see today’s RNS announcement – with scope for your own questions.
Edmond Jackson is a freelance contributor and not a direct employee of interactive investor.
Leave a Reply