Investment Trust Dividends

Author: admin (Page 30 of 463)

Across the pond

5 Monthly Payers (up to 18.2%) Make “High-Yield Stocks” Look Broke
Brett Owens, Chief Investment Strategist
Updated: July 24, 2026

Why sit around and wait all quarter long for a dividend payment?

Monthly divvies are where the retirement party is at! These income “cheat codes” arrive alongside our bills and recurring expenses. What a concept!

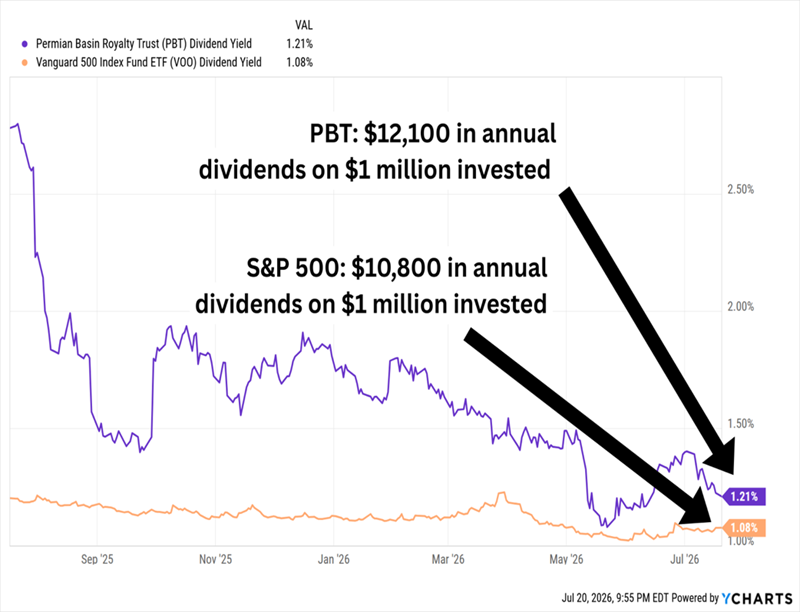
But be careful because some monthly payers don’t pay enough to matter. Take Permian Basin Royalty Trust (PBT), which pays monthly but these divvies add up to just 1.2% annually. Gee, thanks.

$1M Invested in Either Would Pay Under the US Poverty Line
We need monthly payers that are committed to maximizing not just the frequency of shareholder rewards, but the size of the payout. And we need to shoot high—we shouldn’t settle for anything less than what it would take to retire on dividends alone.

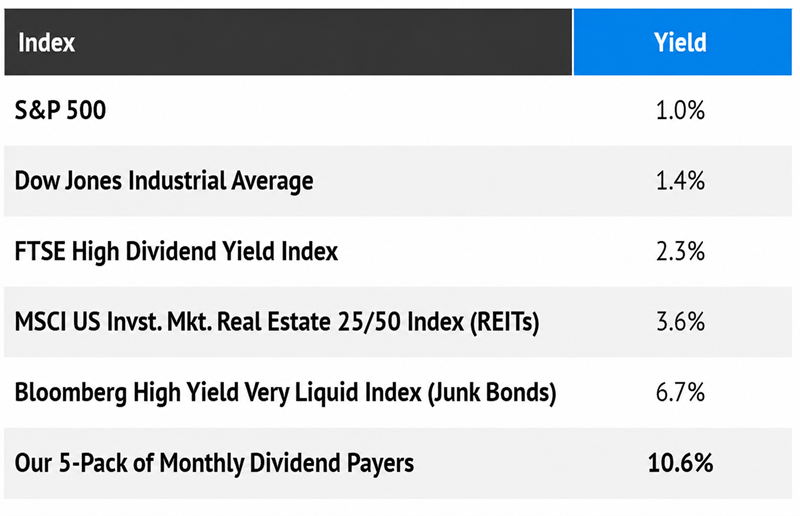
Fortunately for us, many monthly dividend stocks fall within the high-yield acronyms: real estate investment trusts (REITs), business development companies (BDCs) and the like.

Today, for instance, I’ve put together a five-pack of monthly dividends that shell out an average of 10.6% annually. That means even half a million bucks evenly invested across them would generate a hefty “salary” of $53,000.
Let’s take a look.

Healthpeak Properties (DOC)
Dividend Yield: 5.4%

I’ll start with Healthpeak Properties (DOC), a healthcare REIT whose roughly 690 properties include outpatient medical facilities and laboratories, which are leased out to biopharma firms, health systems, physician groups, medical device manufacturers and more.

Healthpeak also deals in senior housing, albeit not as directly as it did just a few months ago. In March, DOC spun off that part of the business with an initial public offering of Janus Living (JAN). It wasn’t a full exit, however. Healthpeak not only retained more than 80% of the newly formed REIT, but it also is Janus’s external manager.

A couple months later, DOC received a much-needed jolt after reporting better-than-expected earnings and upgrading its funds from operations (FFO) outlook. Among the reasons for management’s optimism: The senior housing environment is improving, Janus appears primed to aggressively invest, and a weak laboratories market showed small signs that it’s starting to inflect.

And just this week, Healthpeak announced a $2.1 billion joint venture with Brookfield Asset Management (BAM) that will help DOC to pay down nearer-term debt (though it could be a short-term weight on earnings, too).

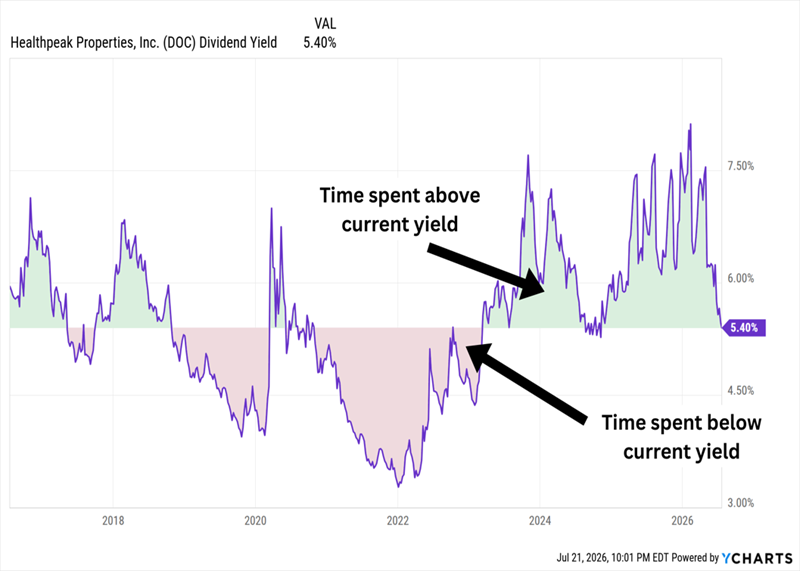
Healthpeak’s stock has delivered a year-to-date total return of almost 45% thanks to its summer ramp-up. It’s a welcome development for shareholders that have suffered through a decade-plus downtrend. However, new money is now buying a yield that’s well below historical highs and closer to a longer-term middle ground, while the P/FFO has wafted to just above 13—not wildly overpriced, but not discount territory either.

DOC’s Yield Has Dropped to Three-Year Lows
Itau Unibanco Holding (ITUB)
Dividend Yield: 6.2%

Most international companies pay dividends just once or twice a year, and some will even do a lopsided interim-and-final system. That’s practically useless for income planning.

Itaú Unibanco Holding (ITUB) isn’t exactly a conventional payer itself, but it at least doles out something each and every month.

Itaú Unibanco is the largest bank by assets in both Brazil and all of Latin America. It offers consumer banking products like credit cards and loans, but also commercial banking, advisory, real estate lending, life insurance and more. And while it’s headquartered in Brazil, it has operations across the Americas and Europe.

The company has printed bigger top and bottom lines every year since 2020, and it’s coming off a record-breaking first quarter in which it posted a $2.5 billion profit and a return on equity of around 25%. The company is also one of the region’s leaders in digital assets, giving it another potential growth avenue.

ITUB’s distributions are tied to performance, so Itaú Unibanco has increasingly been sharing the wealth with its stockholders. But while it pays much more frequently than most, it still has an odd system.

Itaú Unibanco: Generous but Complex
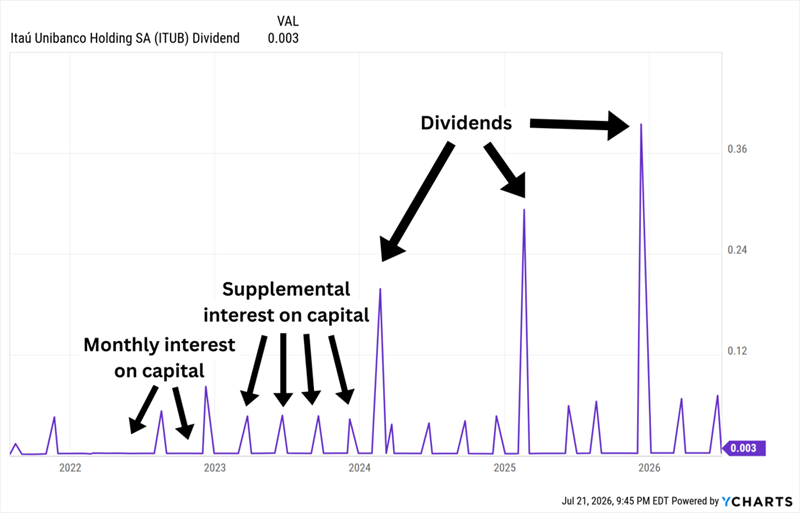
I’ve written several times about companies with regular-and-supplemental dividend programs. Itaú goes a step farther. The company distributes small monthly payments of “interest on capital” (IOC), but it will also make larger additional IOC payments throughout the year as able, then an actual dividend—usually its biggest payment—once a year.

The monthly payment only comes out to less than half a percent’s worth of yield; the real money is in those larger IOC distributions and the dividend. So while the dividends are a nice sweetener for investors who like ITUB for its growth potential, it’s not an ideal situation for retirement planners reliant on regular income.

Gladstone Investment (GAIN)
Dividend Yield: 9.1%

Let’s shift to business development companies, starting with one that has a regular-and-supplemental system like ITUB (but with a much more substantial baseline of income).

For the unfamiliar: BDCs were created by Congress in 1980 to spur investment in small businesses. Traditional banks often shunned smaller companies, either charging extremely high rates to compensate for the risk or outright refusing to lend to them. Enter BDCs, which provide equity, debt and other financing to small businesses that otherwise might not be able to raise capital.

Gladstone Investment (GAIN), for instance, provides financing to lower-middle-market companies that generate EBITDA (earnings before interest, taxes, depreciation and amortization) of between $4 million and $15 million annually, have attractive fundamentals and are run by strong management teams.

GAIN runs a small portfolio of just 29 investment companies right now, largely clustered in the business/consumer services, consumer products and manufacturing industries. Its investments include Phoenix Door Systems (industrial doors), ImageWorks Display (retail display shelving) and Old World Christmas (holiday-geared retail).

Gladstone Investment also stands out for its deal mix. Like with most BDCs, the majority of Gladstone’s financing is debt-based, and currently, all of that debt is floating-rate in nature. But GAIN is happier than most to deal in equity. Gladstone says the average BDC’s equity exposure is between 5% and 10%; its target is closer to 25%. This shields GAIN from interest-rate declines but puts it behind the 8-ball when rates climb.

There’s plenty to like from an operational standpoint. Net asset value has grown by nearly 30% between its fiscal Q1 and its recently reported fiscal Q4. Return on equity is consistently in the double digits and above peers.

The dividend is best described as “good with the potential for greatness.” GAIN’s monthly dividend comes out to a little less than 6%, which is high compared to the average stock and far better than what ITUB offers, but low relative to the BDC space. However, Gladstone Investment also pays supplemental distributions when it locks in gains from its equity investments.

If Only GAIN’s Gains Were a Bit More Predictable
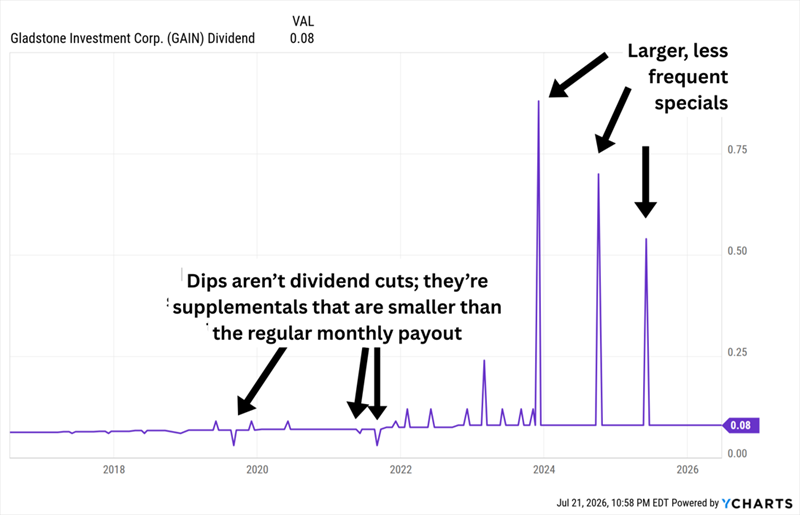
Right now, for instance, Gladstone Investment has gone roughly a year since its last supplemental. It might pay one later this year. It might do so in early 2027. It might be even longer; it’s hard to tell.

Still, it’s a decent income baseline with the potential for more, and it’s paid out by one of the industry’s better names. Pricing could be better, though, with GAIN shares currently trading right around the BDC’s net asset value.

PennantPark Floating Rate Capital (PFLT)
Dividend Yield: 14.0%

PennantPark Floating Rate Capital (PFLT) is another BDC that provides financing primarily via floating-rate senior secured loans—mostly first lien—but also through some equity and joint venture investments. Its target companies generate $10 million to $50 million in annual EBITDA.

This “value-added” BDC lends its expertise in specific industries, hence its portfolio focus on five categories: healthcare, consumer, business services, government services and software/technology.

Earlier this year, I wrote that PennantPark Floating Rate’s dividend has routinely outstripped its net investment income (NII), and did so again to close out 2025. The company insisted then that it could keep covering the payout.

But PFLT’s Actions Spoke Louder Than Words
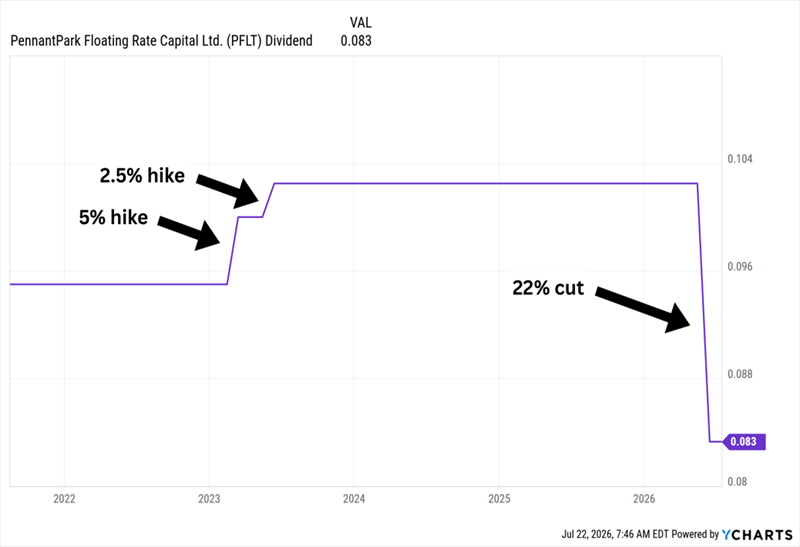
PFLT adjusted its monthly dividend program from 10.25 cents per share to an 8-cent regular, as well as supplemental dividends (50% of excess earnings). The first two supplemental dividends since the reduction were 0.33 cents apiece.

But not all dividend cuts are created equally. In the case of PFLT, its dividend cut is more a reflection of lower base rates than any underlying portfolio issues. In fact, the company’s credit quality is high relative to the sector, and sponsor investment activity is improving. Moreover, PFLT continues to trade for a song, priced at a 32% discount to NAV.

Invesco Mortgage Capital (IVR)
Dividend Yield: 18.2%

It’s hard to find better yields than in the mortgage REIT (mREIT) space, where double-digit payouts are the norm.

Mortgage REITs borrow at short-term rates, purchase mortgages paying long-term rates, then pocket the spread. Short-term rates are usually lower than long-term rates. But the ideal scenario is that short-term rates are also declining while long-term rates hold steady or also decline. In that scenario, mREITs’ existing mortgages, which were issued when rates were higher, will yield more than newly issued ones (and thus be worth more). On the flip side, rising rates weigh on the value of existing mortgages.

Invesco Mortgage Capital (IVR), for instance, owns “agency” mortgage-backed securities (MBS) from entities like Fannie Mae and Freddie Mac. These securities feel interest-rate pressure too, but it’s not as great because their MBSs are backed by the agencies, and thus they have virtually no default risk. I’ll also note that rising interest rates reduce the risk of prepayment, mostly because mortgage holders are less likely to refinance.

While Invesco Mortgage Capital yields a mouth-watering 18%, mortgage REITs historically have been prone to unstable dividends, and IVR is no different.

But Its Most Recent “Cut” Is Good News for Investors
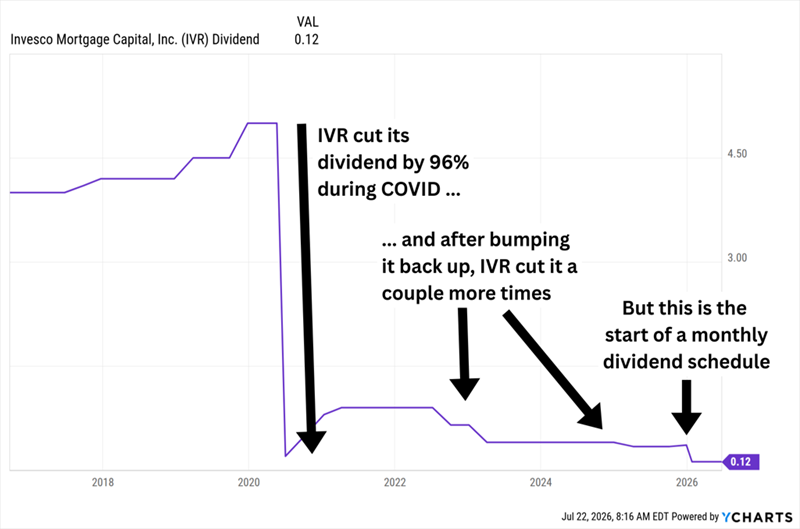
Near the end of 2025, IVR announced a modest 6% dividend hike to 36 cents per share to be paid in January. But in January, the company announced it would start to issue monthly dividends of 12 cents per share (so, the same amount each quarter).

Invesco Mortgage Capital has mostly underperformed its peers since COVID, but it has behaved much better over the past year or so. Dividend coverage, per its “earnings available per distribution” (EAD), is fine for now, too. But despite an effectively flat year-to-date performance (even accounting for its massive payout), shares trade at a thin discount to its shrinking book value.
Your Snowball

If you trade TR the value of your retirement portfolio is the known unknown as the final value will be decided by Mr. Market.

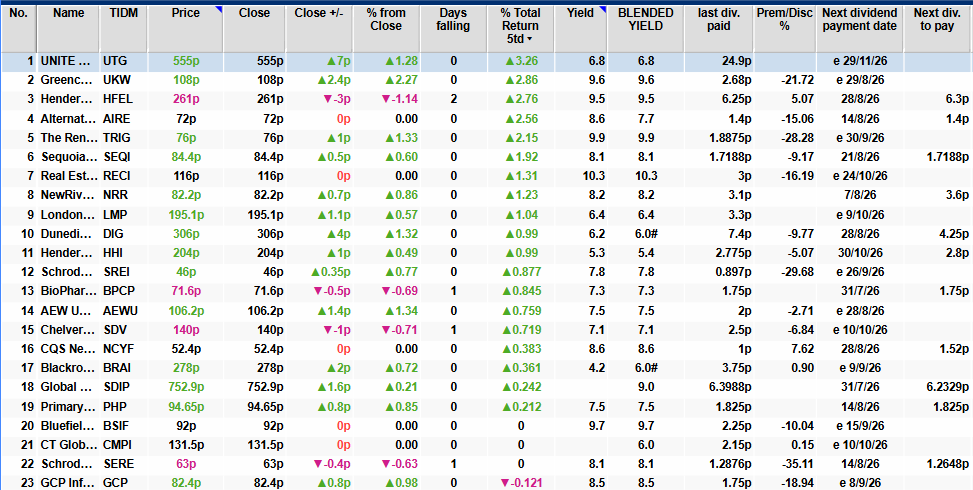
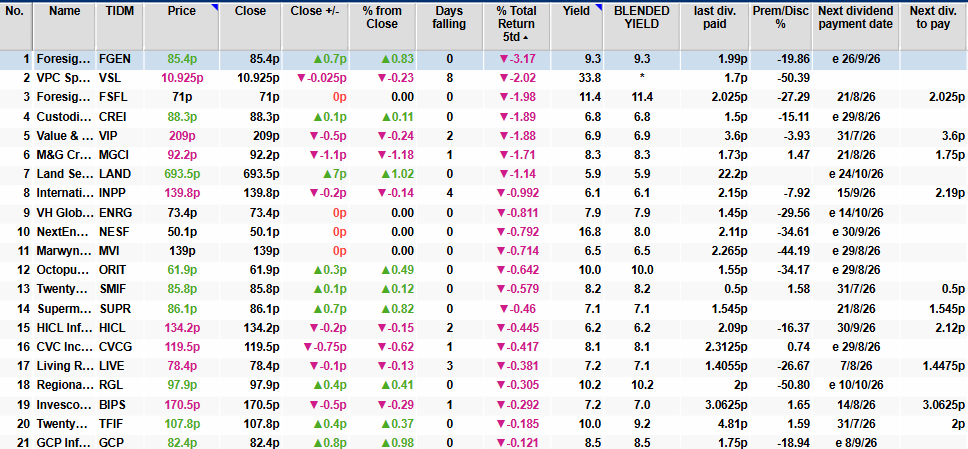
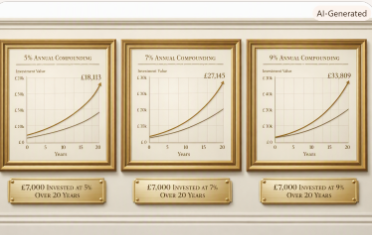
If you trade dividend income you can plot out your retirement income, especially as the Investment Trust/CEF’s have been supplemented with ETF’s.

The actual figures are not important but the chart plot is.

REIT Across the pond

REIT Rebound: 3 Top REITs Averaging 9.8% FWD Yield

Jul 23, 2026 IIPR, EPR, NLCP

Steven Cress, Quant Team

SA Quant Strategist

Summary

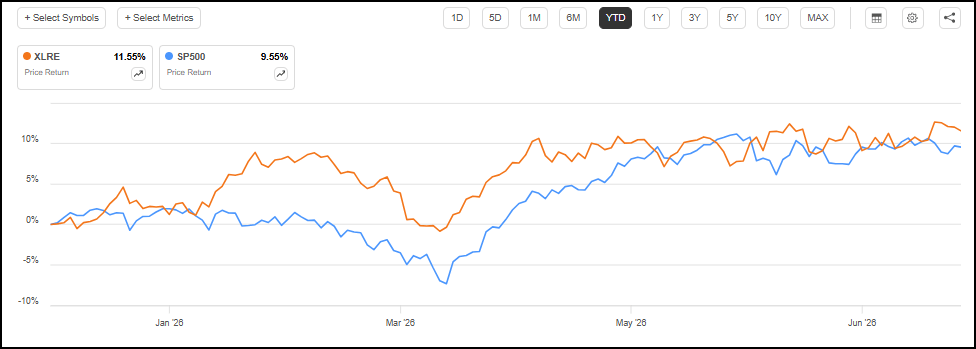
  • REITs are staging a comeback in 2026, with the real estate sector (XLRE) outperforming broad equities, potentially signaling stronger full‑year returns.
  • Given recent market volatility, REITs can be a smart addition to portfolios, offering steady income today alongside meaningful long‑term capital appreciation potential.
  • SA Quant’s proprietary REIT factor model has identified three REIT Strong Buys delivering an average forward yield of nearly 9.8%, pairing high income potential with solid dividend safety grades.
  • I am Steven Cress, Head of Quantitative Strategies at Seeking Alpha. I manage the quant ratings and factor grades on stocks and ETFs in Seeking Alpha Premium. I also lead Quant Growth and Income, which is a model portfolio for dividend investors interested in capital appreciation and income.
Reit"s concept is shown by businessman
8vFanI/iStock via Getty Images

Why 2026 Could Be the Year REITs Rebound

2026 is shaping up to be a brighter year for REITs than 2025. The real estate sector (XLRE) has outperformed broad equities so far this year, and that early strength has historically been a good indicator for full-year performance.

State Street Real Estate Select Sector SPDR ETF (XLRE) vs. The S&P 500 YTD

XLRE vs. S&P 500
SA Premium

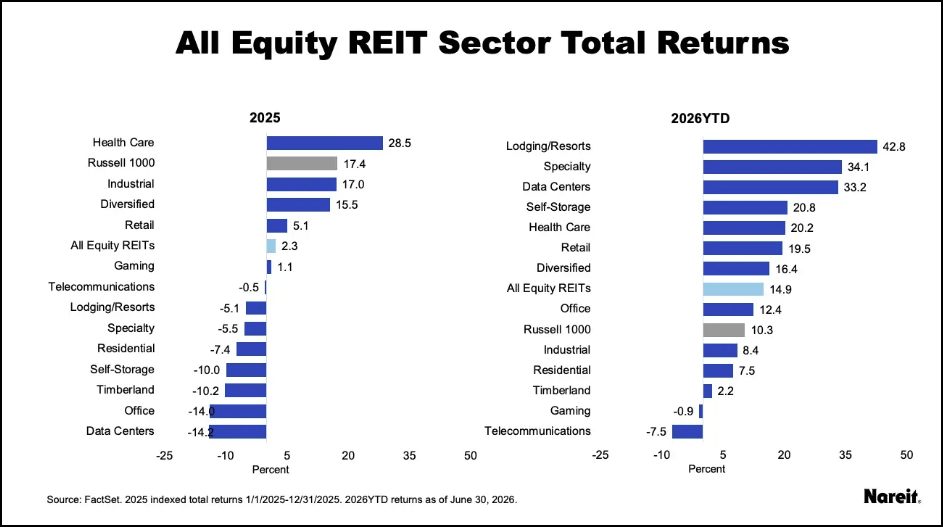
Last year, REITs lagged as higher-for-longer rates and valuation pressure weighed on returns, even though fundamentals remained solid. In 2025, the broad equity market outperformed REITs, but by mid 2026, REITs had reversed that gap and were ahead of the Russell 1000, with gains broadening across most property sectors. That strength reflects both supportive operating trends and the shifting landscape of the REIT sector tied to long-term shifts in the economy.

REIT Sector Performance
Nareit

Source Link

Macro tailwinds could also portend continued strength for the sector. Recent inflation data has cooled, which could lower expectations for additional Fed tightening and help stabilize rate expectations that are paramount for real estate valuations. June CPI declined 0.4% month over month, core CPI was flat and running at 2.6% year over year, and June PPI also came in softer than expected, reinforcing the idea that inflation pressures may be easing rather than reaccelerating.

With that macro pressure easing, the sector is getting more support from fundamentals too. Industrial REITs continue to benefit from reshoring-related demand, while retail, senior housing, hotels, and data centers have been cited as areas where demand is outpacing new supply, giving landlords more pricing power.

Outside of appreciation potential, REITs can be a useful portfolio tool in the current volatile market because their income stream can help steady overall cash flows. Their dividends may offer a more reliable return profile than many equities, especially as investors rotate between inflation concerns, rate-cut expectations, and growth-stock swings. In that role, REITs can provide both income and a measure of stability while markets digest a still-uncertain macro backdrop

How I Chose My Top 3 REITs Averaging 9.8% FWD Yield

When I write dividend-focused articles, I tend to focus on companies with excellent dividend safety and growth grades. However, for this exercise, I targeted REITs using Seeking Alpha’s Top Real Estate Stock Screener, filtering for Strong Buys with yields above 5% and dividend safety that’s better or broadly in line with the sector. I placed less emphasis on dividend growth because the goal here was to identify names that could offer a sizable income stream today, even if near-term payout growth is not especially compelling. Let’s take a closer look at the names below.

1. Innovative Industrial Properties, Inc. (IIPR)

  • Industry: Industrial REITs
  • Market Capitalization: $1.81B
  • Quant Sector Ranking (as of 7/23/2026): 15 out of 168
  • Quant Industry Ranking (as of 7/23/2026): 3 out of 13
  • Quant Rating: Strong Buy
  • FWD Yield: 12.20%

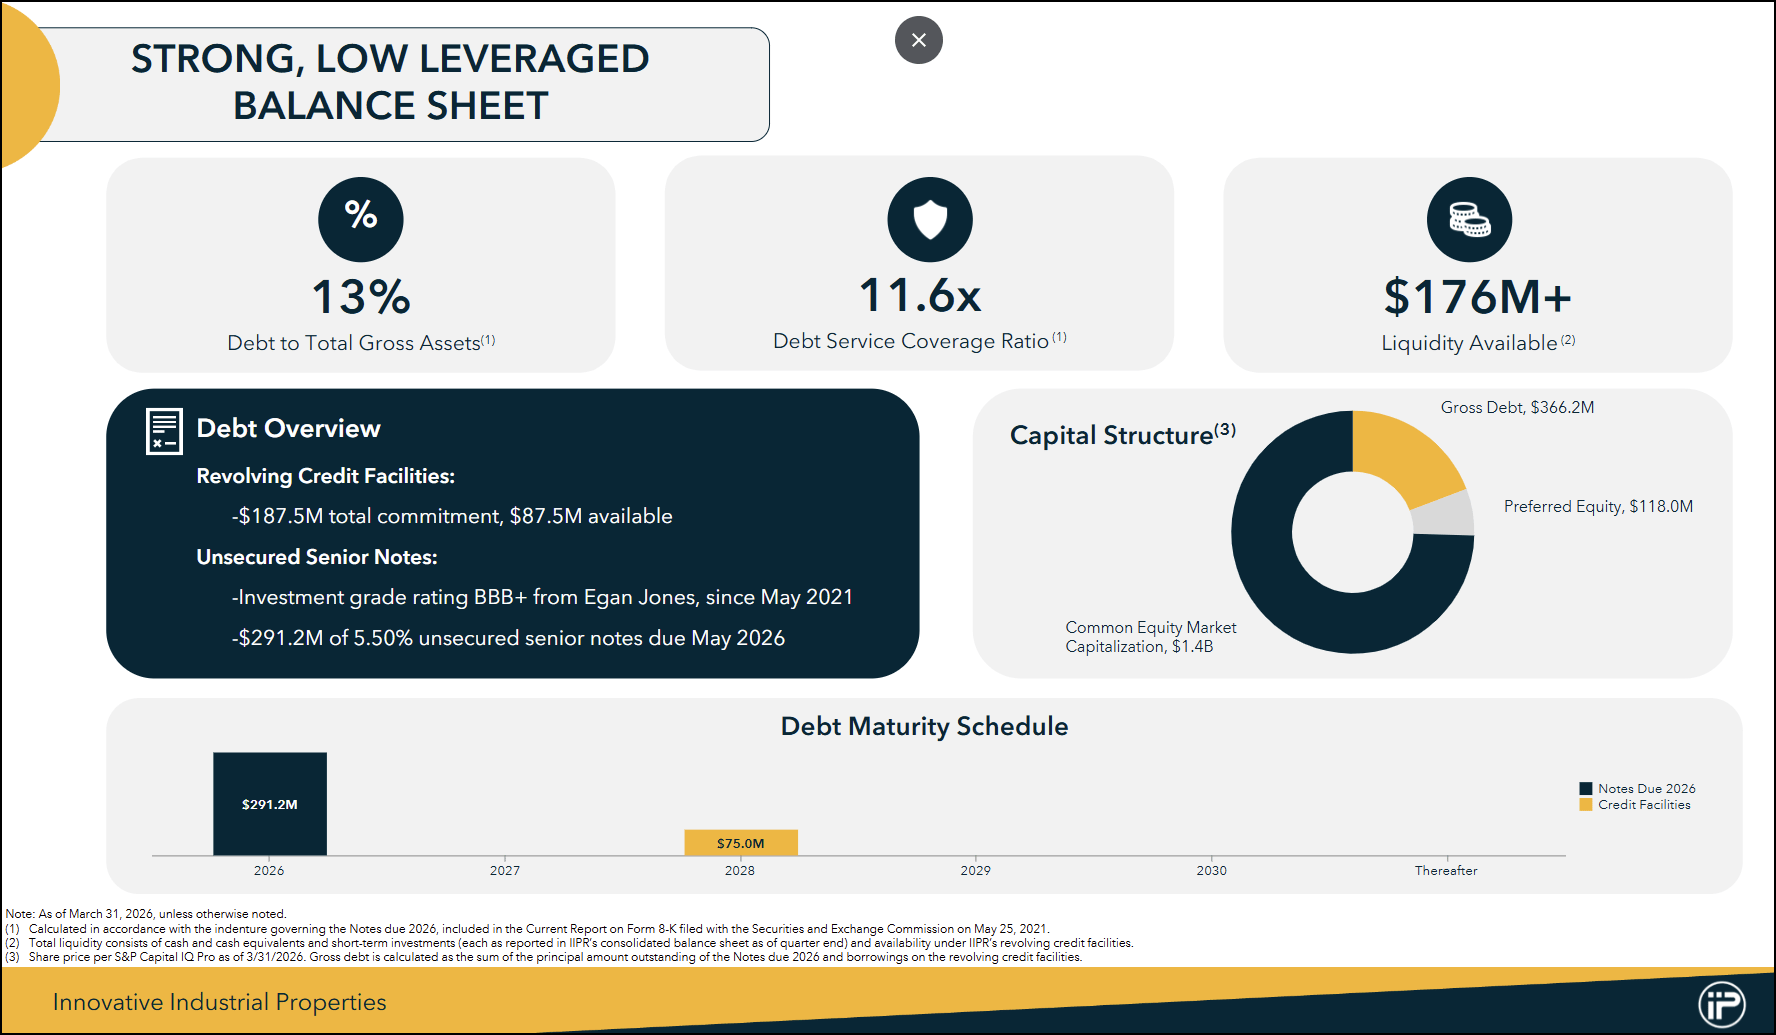
Innovative Industrial Properties (IIPR) is the No. 3 Quant-ranked Industrial REIT that owns and leases specialized facilities to state‑licensed cannabis operators, with a growing foothold in life‑science real estate. Its recent earnings call showed revenue and cash flow holding steady while growth is driven by signing new tenants on formerly defaulted properties, progressing dozens of lease agreements, and investing in the IQHQ life‑science project, all supported by solid liquidity and modest debt.

IIPR Investor Presentation

Source Link

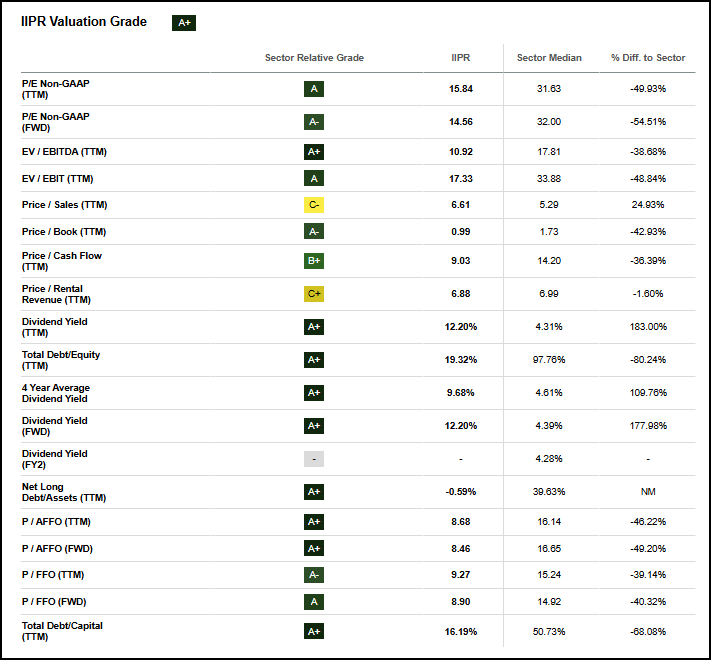
IIPR AFFO growth 5Y CAGR is 77% above the sector median, accompanied by stellar profitability. The company offers an AFFO margin that’s 94% above the REIT sector median, alongside a net income margin of nearly 46%. The company especially stands out in terms of its valuation where it offers both trailing and forward price/AFFO ratios that are 46% and 49% below the sector median, respectively.

IIPR Valuation Grade

IIPR Valuation Grade
SA Premium

The company is particularly attractive for its dividend profile. Currently yielding 12.20%, well above the sector average, IIPR also has solid dividend safety, supported by an FFO interest coverage ratio of 9x compared to the sector’s 3x. IIPR’s offers a potent combination of excellent fundamentals alongside stable income, making it hard to overlook for REIT investors.

2. EPR Properties (EPR)

  • Industry: Other Specialized REITs
  • Market Capitalization: $4.75B
  • Quant Sector Ranking (as of 7/23/2026): 17 out of 167
  • Quant Industry Ranking (as of 7/23/2026): 1 out of 11
  • Quant Rating: Strong Buy
  • FWD Yield: 6.00%

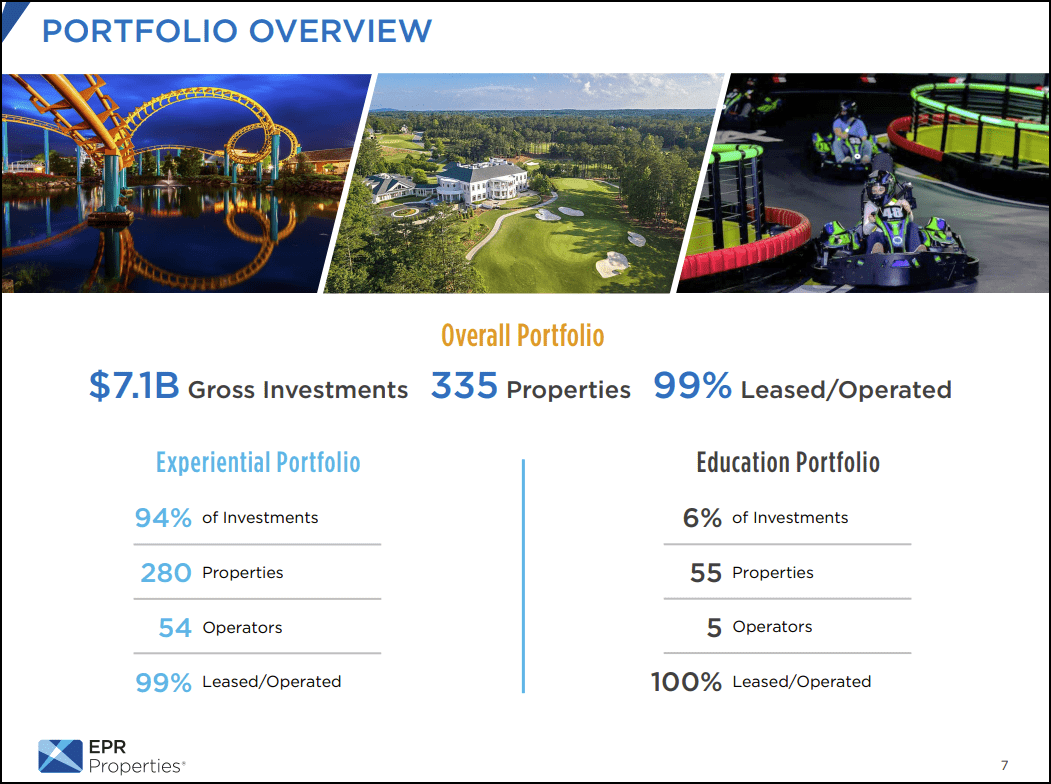
EPR Properties is a specialty REIT that owns experiential real estate, including movie theaters, education assets, and recreation venues such as ski resorts and water parks, largely under long-term net leases. The company was one of the inaugural holdings in the Quant Growth & Income portfolio and has stood out in this volatile market, returning about 10.3% since the portfolio’s launch on June 3. The company has invested $7.1 billion across 335 properties and maintains a 99% leased or operated rate.

EPR Q1 2026 Investor Presentation

Source Link: EPR Q1 2026 Investor Presentation

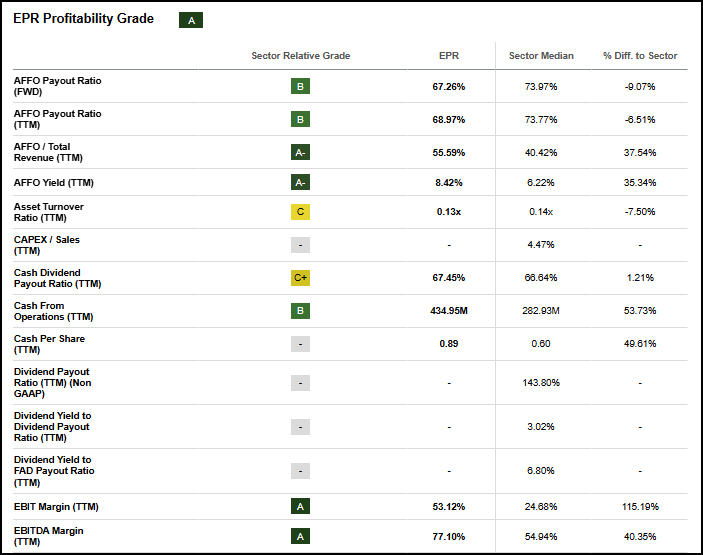
EPR’s growth profile has rapidly improved to an ‘B+’ after sitting at a ‘C’ just six months ago. Highlights include Its forward AFFO growth of 5.40% that exceeds the sector median by nearly 85%. The company also showcases a TTM dividend growth rate of 4% vs. just 2% for the broader REIT sector. ERP’s triple‑net lease structure has helped fortify its profitability by shifting property‑level costs (taxes, insurance, and utilities) to tenants. This protects margins even in a higher‑rate, higher‑inflation environment.

EPR Profitability Grade

EPR Profitability Grade
SA Premium

EPR offers a forward dividend yield in the 6% range, which is comfortably above the broader REIT sector. This sizable dividend is supported by its forward AFFO yield is close to 9%, creating a cushion that supports the current payout while still leaving room for the company to reinvest in future growth.

3. NewLake Capital Partners, Inc. (NLCP)

  • Industry: Industrial REITs
  • Market Capitalization: $324.33M
  • Quant Sector Ranking (as of 7/23/2026): 6 out of 167
  • Quant Industry Ranking (as of 7/23/2026): 1 out of 13
  • Quant Rating: Strong Buy
  • FWD Yield: 11.10%

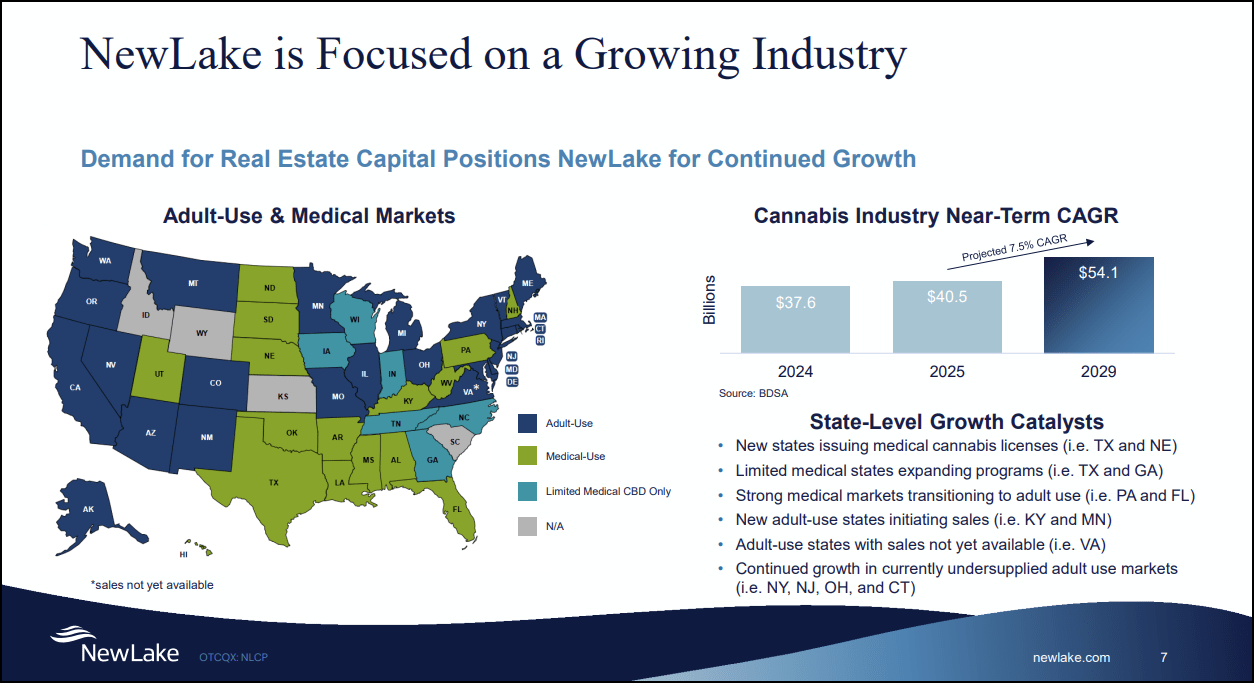
NewLake Capital Partners is another cannabis-adjacent REIT provides real estate capital to state‑licensed cannabis operators. The company operates a triple-net lease model that involves sale‑leaseback deals on cultivation facilities and dispensaries. The REIT buys properties and leases them back to operators, giving tenants growth capital while retaining long‑term ownership of the underlying real estate. NLCP is benefiting from a rapidly expanding U.S. cannabis footprint. Rising rising state adoption and a projected mid single‑digit industry CAGR create a long runway for NewLake.

NLCP Investor Presentation

Source Link: NLCP Investor Presentation

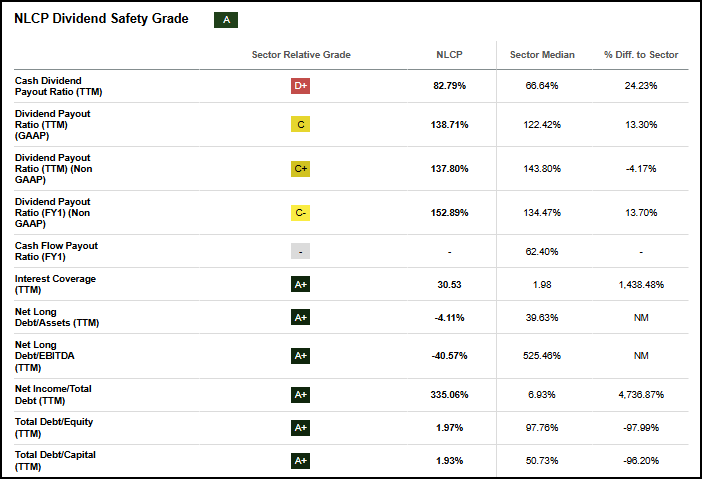
NLCP’s forward dividend yield sits around 11% and exceeds the sector median by more than 150%. Its dividend profile is further supported by strong coverage metrics, including an interest coverage ratio of roughly 30x, which underscores both payout safety and balance‑sheet strength.

NLCP Dividend Safety Grade

NLCP Dividend Safety Grade
SA Premium

NewLake’s growth story is increasingly tied to a more accommodative regulatory environment, dovetailed by its conservative balance sheet. A potential federal rescheduling of medical cannabis, potential 280E tax relief, and a coming ban on intoxicating hemp products could strengthen tenant finances, creating more opportunities for NewLake to deploy capital into cultivation and dispensary properties. The stock trades at a hefty discount across key REIT valuation metrics like its FWD Price/AFFO, which sits 51% below the sector median. With the cannabis industry on the cusp of multiple growth catalysts, now could be an opportune time to consider adding this high‑yielding value name to a diversified income portfolio.

Concluding Summary

REITs are finally getting some tailwind in 2026, with the sector outperforming broad equities as inflation has been leveling and interest‑rate expectations stabilize. In this environment, income seekers can find attractive opportunities in select high‑yield names that combine strong payouts with solid fundamentals and balance‑sheet strength. SA Quant has identified Innovative Industrial Properties (IIPR), EPR Properties (EPR), and NewLake Capital Partners (NLCP) as three REITs offering a near average 9.8% forward yield alongside strong factor grades and robust dividend safety.

MotleyFool Canada

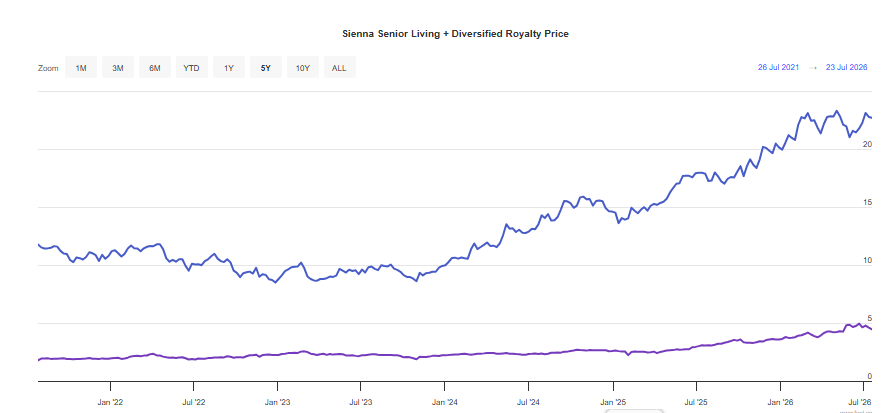
How I’d Structure My TFSA With $14,000 for Consistent Monthly Income

Turn a $14,000 TFSA into about $60 a month in tax-free income by pairing a senior-housing operator with a consumer-brand royalty collector.

Posted by Amy Legate-Wolf

Published July 23

DIV SIA

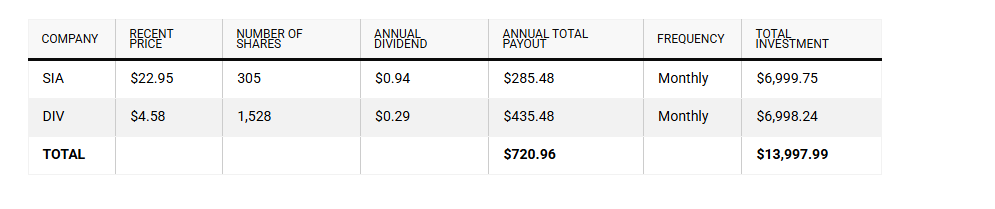
  • Split $14,000 between Sienna Senior Living and Diversified Royalty to target about $721 yearly income, paid monthly.
  • Sienna’s dividend looks better covered, with improving occupancy and an AFFO payout ratio around 68.5%.
  • Diversified Royalty pays a higher yield but had a payout ratio above 100% last quarter, so monitor coverage and diversify.

One $14,000 Tax-Free Savings Account (TFSA) balance could trigger more than 120 tax-free deposits over the next decade, without selling a single share. How? At current prices, two monthly dividend stocks could produce about $60 every month, creating a small retirement paycheque that keeps showing up while the portfolio remains invested.

That income won’t replace a salary, but it can buy new shares, cover a bill, or grow into something far more useful over time. The key is building the payments around businesses supported by different sources of cash flow rather than chasing one enormous yield.

Once invested inside a TFSA, dividends and capital gains can grow without Canadian tax. That gives monthly payments more money to compound, which leads me to Sienna Senior Living (TSX:SIA) and Diversified Royalty (TSX:DIV).Z

SIA

SIA stock owns and operates retirement residences and long-term-care homes across Canada. Demand should continue growing as the population ages, while government funding and resident fees create recurring revenue from services people can’t simply postpone.

* Returns as of July 6th, 2026

The company’s retirement same-property occupancy reached 94.7% during the first quarter, while its adjusted funds-from-operations (AFFO) payout ratio improved to 68.5%. That coverage supports SIA stock’s monthly dividend of $0.078 per share, equal to $0.936 annually.

SIA stock therefore provides a relatively defensive starting point, but healthcare exposure alone won’t create a balanced income plan. The second holding adds royalties collected from a much broader group of consumer businesses.

DIV

Diversified Royalty earns cash by owning trademarks and other rights used by brands including Mr. Lube, BarBurrito, and AIR MILES. Those partners pay royalties based on sales or fixed agreements, allowing Diversified Royalty to collect cash without operating every restaurant, tutoring centre, or automotive shop itself.

First-quarter revenue rose 11.8% to $17.5 million, while distributable cash increased to $12 million. The first-quarter payout ratio reached 101.1%, partly due to seasonal weakness among certain partners. Investors should watch that figure closely, although management aims to pay a stable monthly dividend and grow it as cash flow allows.

The $14,000 income plan

With that $14,000, I’d divide the money equally, giving SIA stock’s healthcare operations and Diversified Royalty’s consumer brands the same starting weight. Using recent prices, the portfolio could generate approximately $720.96 annually, or $60.08 per month.

Of course, SIA stock faces staffing expenses, government regulation, development costs, and substantial debt. Diversified Royalty depends on its partners remaining healthy enough to make their payments, while its first-quarter payout exceeded distributable cash.

Those risks make both holdings better suited to one portion of a broader collection of monthly dividend stocks. Reinvesting the income can also reduce the temptation to treat each deposit as guaranteed spending money.

Bottom line

SIA stock brings senior-housing demand and strong distribution coverage, while Diversified Royalty supplies a higher yield backed by several consumer brands. Holding both could keep monthly cash moving into a TFSA today, then let reinvestment turn that modest paycheque into a much larger source of retirement income.

Is your plan to buy an annuity ?

Story by Laura Purkess

i paper

A big concern I hear from those who want to gift money is the fear of leaving themselves short in later life. But that is exactly what annuities are there for, and now is actually a great time to buy one.

Annuities were unpopular for many years because low interest rates meant they offered relatively poor returns, but higher interest rates over the past few years have meant they offer vastly better value.

The average annuity rate was 7.62 per cent as of March 2026, according to insurer Standard Life. That means a healthy 65-year-old with a £100,000 pension pot can lock in a guaranteed annual income of up to £7,620.

With £300,000, you could generate £22,860 income annually – with the full new state pension, that’s an annual income of almost £35,000 a year.

What’s your timetable to retire with secure income to fund your retirement ?

Are you on track with investing for your age?

Wednesday, July 22, 2026

Sarah Coles

Head of Personal Finance

If you’re waiting for the perfect moment to do anything in life, there’s a risk you’ll never get around to it. And when it comes to saving and investing, you’ll pay a real price for the delay. So, it can help to know when other people have taken the plunge, and just how they’re doing, to see whether we’re on track, or if we need to get cracking. Here are the ages that are financial landmarks among AJ Bell customers.

First year of life: Junior ISA accounts are most commonly opened

The most popular time to open an AJ Bell Junior ISA (JISA) is in the first year of a child’s life. It’s a great idea for when you have a newborn, so anyone who wants to celebrate the birth can do so with a gift into the JISA that they’ll appreciate far more than a new rattle or babygrow.

However, people aren’t just using them for one-off payments. The first year of a child’s life is also the most popular time to set up a regular direct debit into the account. If this is a bit of a stretch in the expensive early years, talk to grandparents and the wider family. They may be able to make manageable monthly payments that will keep building a valuable nest egg for when they’re 18.

Age 25 to 26: The most Stocks and shares ISAs are opened

The fact that the most common age to open a Stocks and shares ISA overall is 18 is a testament to the success of the Junior ISA, and how many people have already become investors before they leave childhood.

Excluding maturing JISAs, the most popular age to open an AJ Bell Stocks and shares ISA is either 25 or 26. By this age, people will have started work and have a few years under their belt. They’ll have got to grips with their expenses and are likely to have been in a workplace pension for a few years. They don’t necessarily have vast sums of cash to put away if they’re at the start of their career, but making a start investing this early can make an enormous difference to the rest of their life. If you reach this age and investments aren’t on your radar at all, it’s worth at least investigating what it has to offer.

Age 27: When Lifetime ISAs are most frequently used for property purchases

This is the most common age to use an AJ Bell Lifetime ISA to buy a property (measured as people making penalty-free withdrawals). Given that, overall, the average age to buy a first property is 34 in the UK, there’s a decent chance the government bonus has played a vital role in helping people build the deposits they need to get onto the property ladder.

You can pay up to £4,000 a year into a LISA and the government will top it up by 25%. The LISA will eventually be replaced by a new scheme for first-time buyers, but the date of the replacement, and the size of the government top up on the new scheme haven’t been confirmed. Meanwhile, the government has emphasised anyone opening a LISA before it’s replaced will be able to pay into it and get the bonus as usual for as long as they want, so there’s still enormous benefit in taking advantage of the LISA. For anyone under the age of 27, it may be worth getting started at a younger age, while you still can.

Age 33: Most likely age to make contributions

ISA customers who are age 33 have the highest percentage making an ISA contribution than any other age group on the platform. Some people will be on higher incomes or have made investment a key priority early in life, so will have been making the most of their ISAs for years. However, others will have waited until they were on a firmer financial footing before they made a start.

If you haven’t started investing, it’s a decent time to take stock. You may have other pressing priorities, or a gap in income which means now isn’t the time for you. Otherwise, this may well be an opportunity to start your investment journey.

Age 39: Most likely to open a Lifetime ISA

This is the oldest you can be when you open a Lifetime ISA, although once it’s open, you can keep paying into it until the age of 50. It’s also the age when people are most likely to open an AJ Bell LISA. The rush at 39 might be from some people keeping their options open, just in case they want to use a LISA later.

However, there’s more to it than that, because this is the age when people are most likely to start regular payments into an AJ Bell LISA too. It’s a flexible option for retirement savings, especially for basic rate taxpayers who work for themselves or who have already taken advantage of any employer contributions to their pension. It can also be helpful for anyone who has maxed out their pension contributions. If you want to take advantage of the LISA, it’s worth doing so sooner rather than later, while you still can.

Age 56: Most likely to max out their Stocks and shares ISA

Age 56 is the most common age to max out an AJ Bell Stocks and shares ISA.** One key driver is likely to be from people who have taken the tax-free cash from a pension, who want to keep it invested tax-efficiently.

If you want investments to grow within a tax-efficient environment, then there’s no need to take the cash at 55, because a pension is a great home for your money. By leaving your cash where it is, you also give the pot chance to grow, so you can eventually withdraw a bigger sum.

However, some people have taken tax-free cash because of a lack of reassurance from the government that they’re not going to tinker with the rules. While this is a decision which should be carefully thought through, if you’re going to do this, then a Stocks and shares ISA is a sensible home for your money.

The fact this is a key time for maxing out is also partly down to the fact many people will be empty nesters. Their offspring may have moved out or started working and contributing to the household, so they may have more money to work with and more opportunities to save. It means they can concentrate on building as much for retirement as they can, as soon as they can, in a mixture of pensions and ISAs.

If you’ve reached the empty nest period, it’s worth using a pensions calculator and factoring in additional savings and investments. If you have a shortfall, you can consider whether you can afford to put more aside for the future, to make up for lost time.

Age 63: Average age of a SIPP millionaire

This is the average age of AJ Bell SIPP millionaires, but if you haven’t quite got there, there’s no need to panic. It was always bound to be the age when people have built as much as possible in their pension and start spending it down. However, it’s a handy reminder that a commitment to pension investing from an early age, sticking with it whenever possible, and investing strategically, can help build a really substantial pot for the kind of retirement you always wanted.

Age 70: Average age of an ISA millionaire

This is the most common age of AJ Bell ISA millionaires. This isn’t going to be a target for everyone, but it’s a great demonstration of the power of compounding over time. By investing consistently over the decades, ISA millionaires haven’t had to take enormous risks or trade on a daily basis. They’re evidence of how successful a ‘get rich slow’ plan can be.

*Based on existing customers on the AJ Bell platform, as of 29 June 2026
**Refers to tax years since 2017/18, when the ISA allowance has been set at £20,000

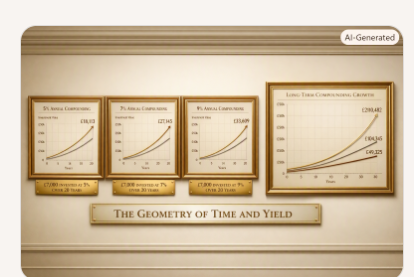
The SNOWBALL currently earns income of 11k per year.

If you re-invest the dividends at a blended yield of 7% it will double every ten years.

So in twenty years, from now, your snowball should be yielding 44% per year. Better if Mr. Market allows you to re-invest at a higher yield as you can shorten the journey. You may not be a millionaire but you should be able to spend like one. GL

« Older posts Newer posts »

© 2026 Passive Income Live

Theme by Anders Noren — Up ↑