Investment Trust Dividends

Category: Uncategorized (Page 62 of 458)

Yield shield across the pond

Yield Shield: Outpacing VIG By 48% With 3 All-Weather Income Leaders

May 04, 2026, 3:55 PM ETVIG, THG, FDX, NJR

SA Quant Strategist

Summary

  • A resurgence in inflation driven by energy price spikes from geopolitical tensions has created an environment where passive dividend benchmarks are struggling to maintain real purchasing power.
  • A diversified mix across the Financial, Industrial, and Utilities sectors provides a defensive “Yield Shield,” built to combat inflation and volatility.
  • By combining “Strong Buy” Quant ratings with elite Dividend Safety, this trifecta of all-weather leaders offers a 48% income premium over VIG, proving that investors can withstand volatility.
  • I am Steven Cress, Head of Quantitative Strategies at Seeking Alpha. I manage the quant ratings and factor grades on stocks and ETFs in Seeking Alpha Premium. I also lead Alpha Picks, which selects the two most attractive stocks to buy each month, and also determines when to sell them.
African American businessman counting coins to protect income and invest
AndreyPopov/iStock via Getty Images

Building a Yield Shield

The first four months of 2026 have delivered an important reminder to income investors: Safety will require an active mindset more often than not. Ending the first quarter, sticky inflation has become a concern once again—bolstered by a 12% spike in energy prices ignited by the U.S. involvement in the Iran War.

For those parked in standard dividend appreciation benchmark ETFs, the results have been less than ideal. While the broad market has remained resilient—with the S&P 500 rising 10.4% in April for its biggest monthly gain since November 2020—income investors searching for yield in traditionally “safe” ETFs have struggled to keep pace with the recent reemergence of inflation.

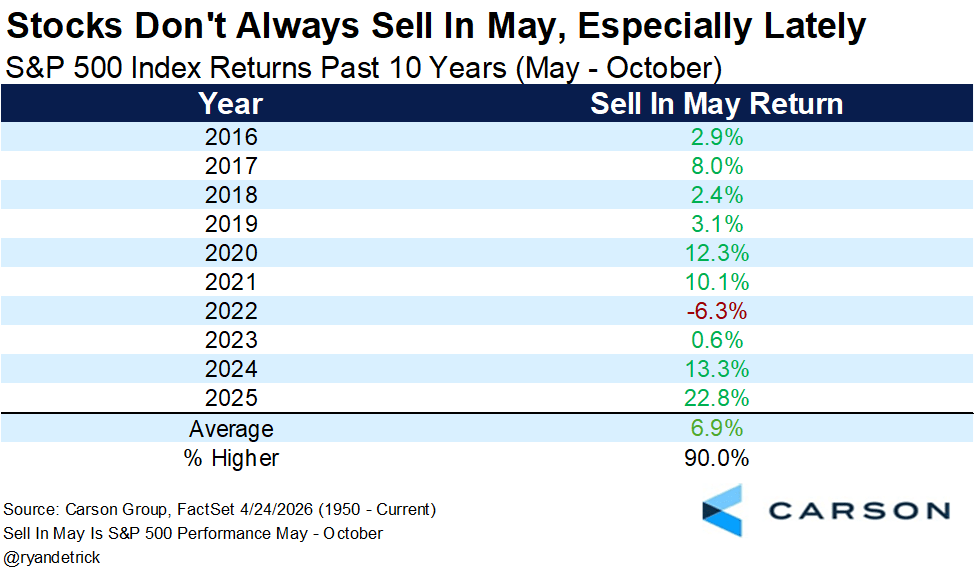
As the calendar turns over and we hit the month of May, financial pundits across the media are likely to dust off their favorite annual warning, “Sell in May and go away.” After all, it’s a midterm year, right?

Recent history writes a different story, though. While the next six months do typically produce weaker gains, it has rarely been negative. In fact, since 2016, only 2022 saw negative performance in May-October.
Carson Group

Skeptics would be right to point out that 2022, the last midterm year, was also fraught with inflation worries. But 2026 is not 2022. The “noise” may continue to echo across Wall Street this summer, which is why investors should be looking for an “all-weather” diversified solution.

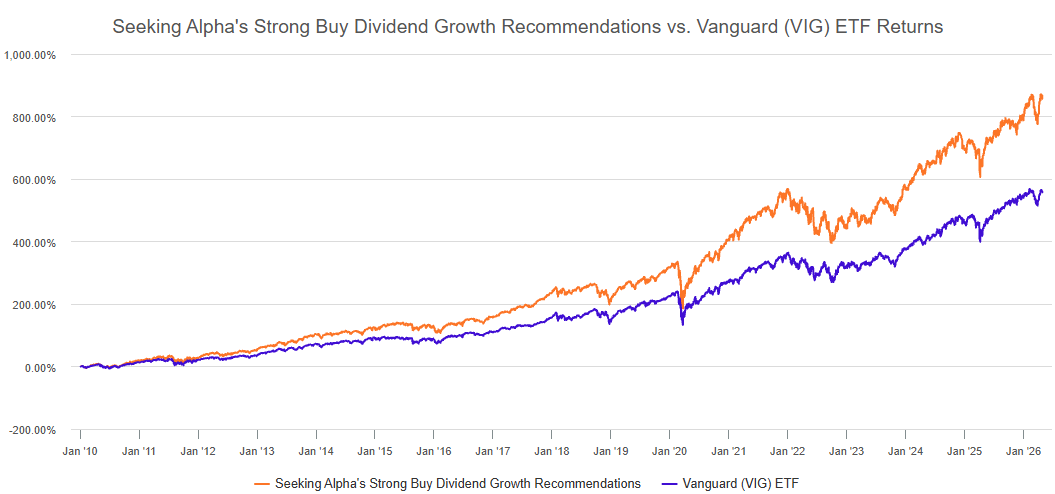
Investors can find signals in Seeking Alpha’s Quant Model, which has consistently outperformed the Vanguard Dividend Appreciation ETF (VIG) over the past decade. The historical chart below illustrates the effectiveness of this quantitative approach and sets the table for the three-pillar strategy we’re discussing today.
Seeking Alpha

Three Sector Pillars

Today, we are looking at a trifecta of income leaders across the Financial, Industrial, and Utilities sectors. Three companies that together can capitalize on sticky inflation, withstand geopolitical shocks, and provide a safe yield cushion.

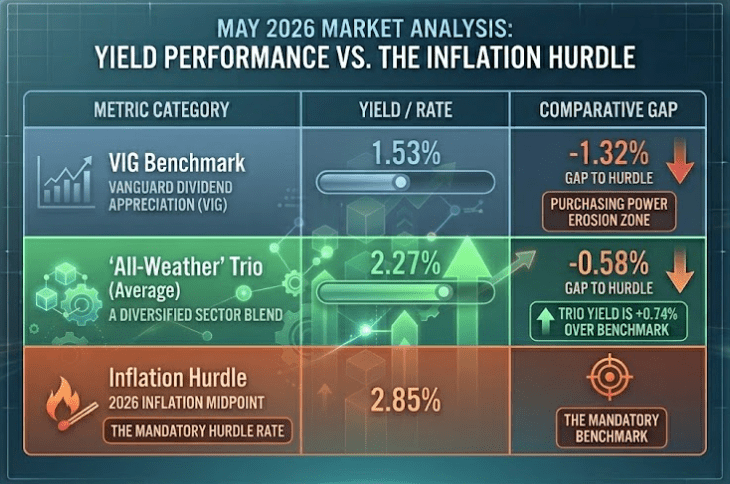
To see why this targeted approach is necessary, let’s compare our selected three stocks to VIG using the Trailing Twelve Month [TTM] Yield.

And to better understand the inflation gap, we have averaged the Pre-War inflation of 2.4% (February) and the Post-War inflation of 3.3% (March) to settle on a “Hurdle Rate” of 2.85%. This smoothes out the “war premium” volatility and provides a baseline for what income investors should be seeking.
Seeking Alpha

VIG’s passive income is no longer within striking distance of the cost of living in the current economic climate. Our All-Weather Trio represents a 48% income premium over the benchmark (when taking the simple average of the trio’s Dividend Yields [TTM] compared to that of VIG), more sector diversification, and a positive spread against pre-war inflation.

If you are looking to outright beat post-war inflation, our Quant Model has highlighted some top dividend stocks yielding over 6%.

Top Dividend Stocks: All-Weather

To select the best “all-weather” dividend stocks to feature in this article, I used the Seeking Alpha Stock Screener and chose the pre-selected Top Quant Dividend Stocks and filtered for Quant Strong Buys. I then selected stocks that exhibited strong Profitability Factor Grades, high Dividend Safety Grades, and ensured the selections created a sector-diverse group.

The dividend safety grade leverages a sophisticated data-driven approach to offer a reliable assessment of a company’s ability to keep paying its dividends and avoid dividend cuts. Our own Quant System backtesting helped avert 98.1% of Dividend Cuts By Owning Stocks With Dividend Safety Grades from A+ to B-.

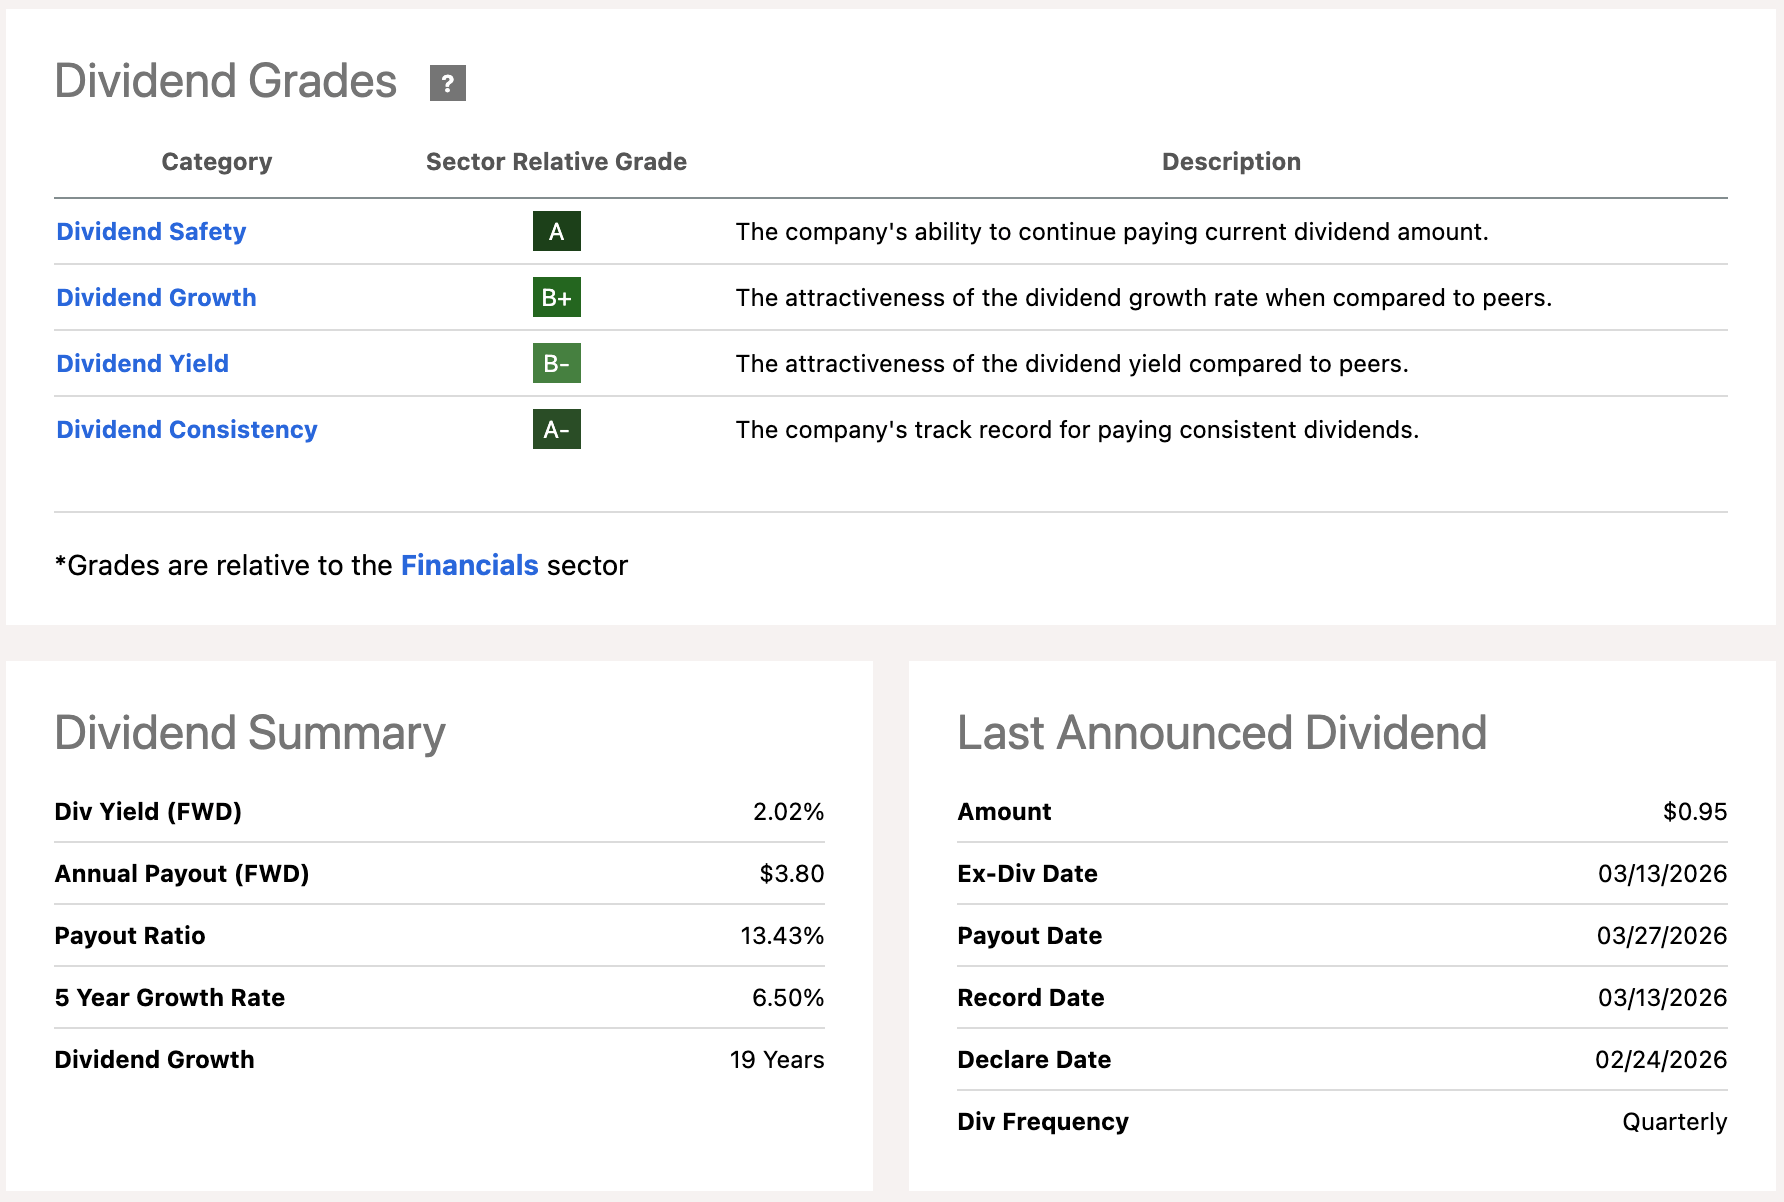
1. The Hanover Insurance Group, Inc. (THG)

  • Market Capitalization: $6.65B
  • Quant Rating: Strong Buy
  • Sector: Financials
  • Industry: Property and Casualty Insurance
  • Quant Sector Ranking (as of 4/28/2026): 12 out of 684
  • Quant Industry Ranking (as of 4/28/2026): 3 out of 54
  • Dividend Yield (FWD): 2.03%

The Financial Fortress

Among my top dividend stock picks for volatile markets in March, the Hanover Insurance Group provides coverage for business, personal, and specialty lines across the U.S.

A diversified portfolio with pricing power has allowed THG to perform across a volatile economic cycle. Insurance is one of the few sectors where the rising costs for consumers can directly translate into widening margins, offering a potential inflation buffer.

On its recent Q1 earnings call, CEO John “Jack” C. Roche said the company “achieved record first quarter performance, including an operating return on equity of 20.3% and operating earnings per share of $5.25…”
Seeking Alpha

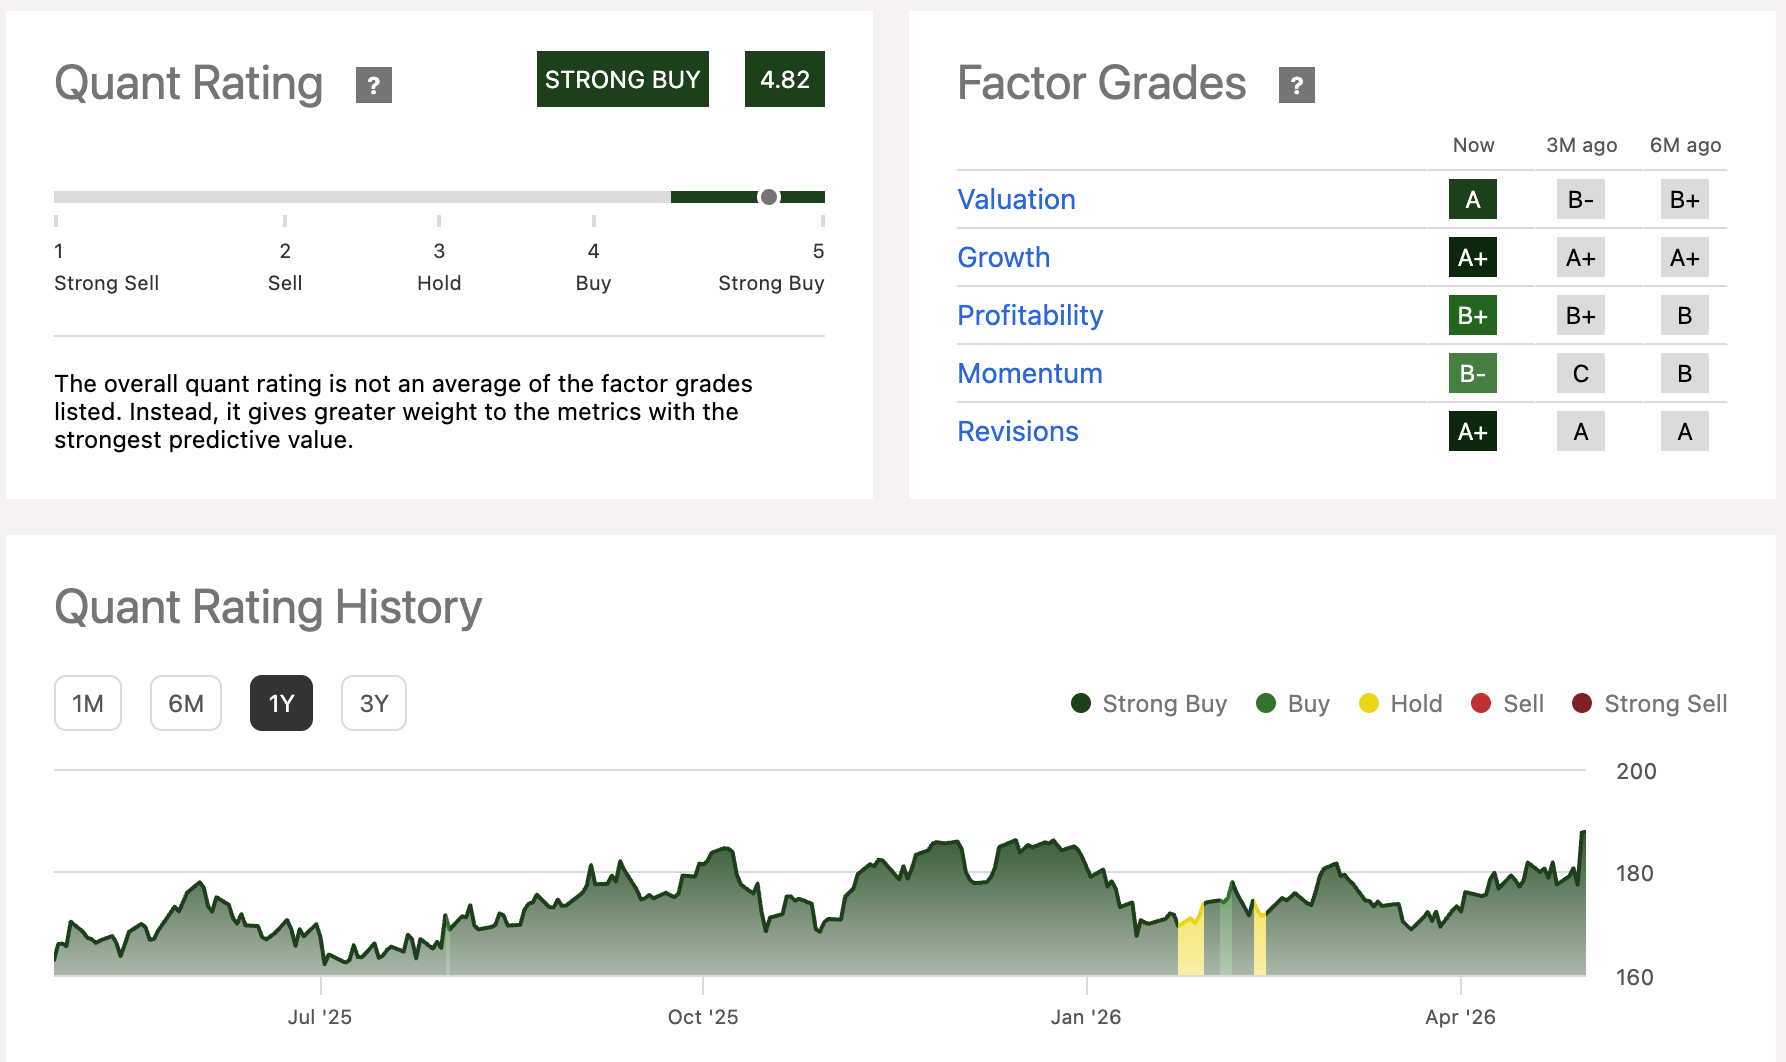
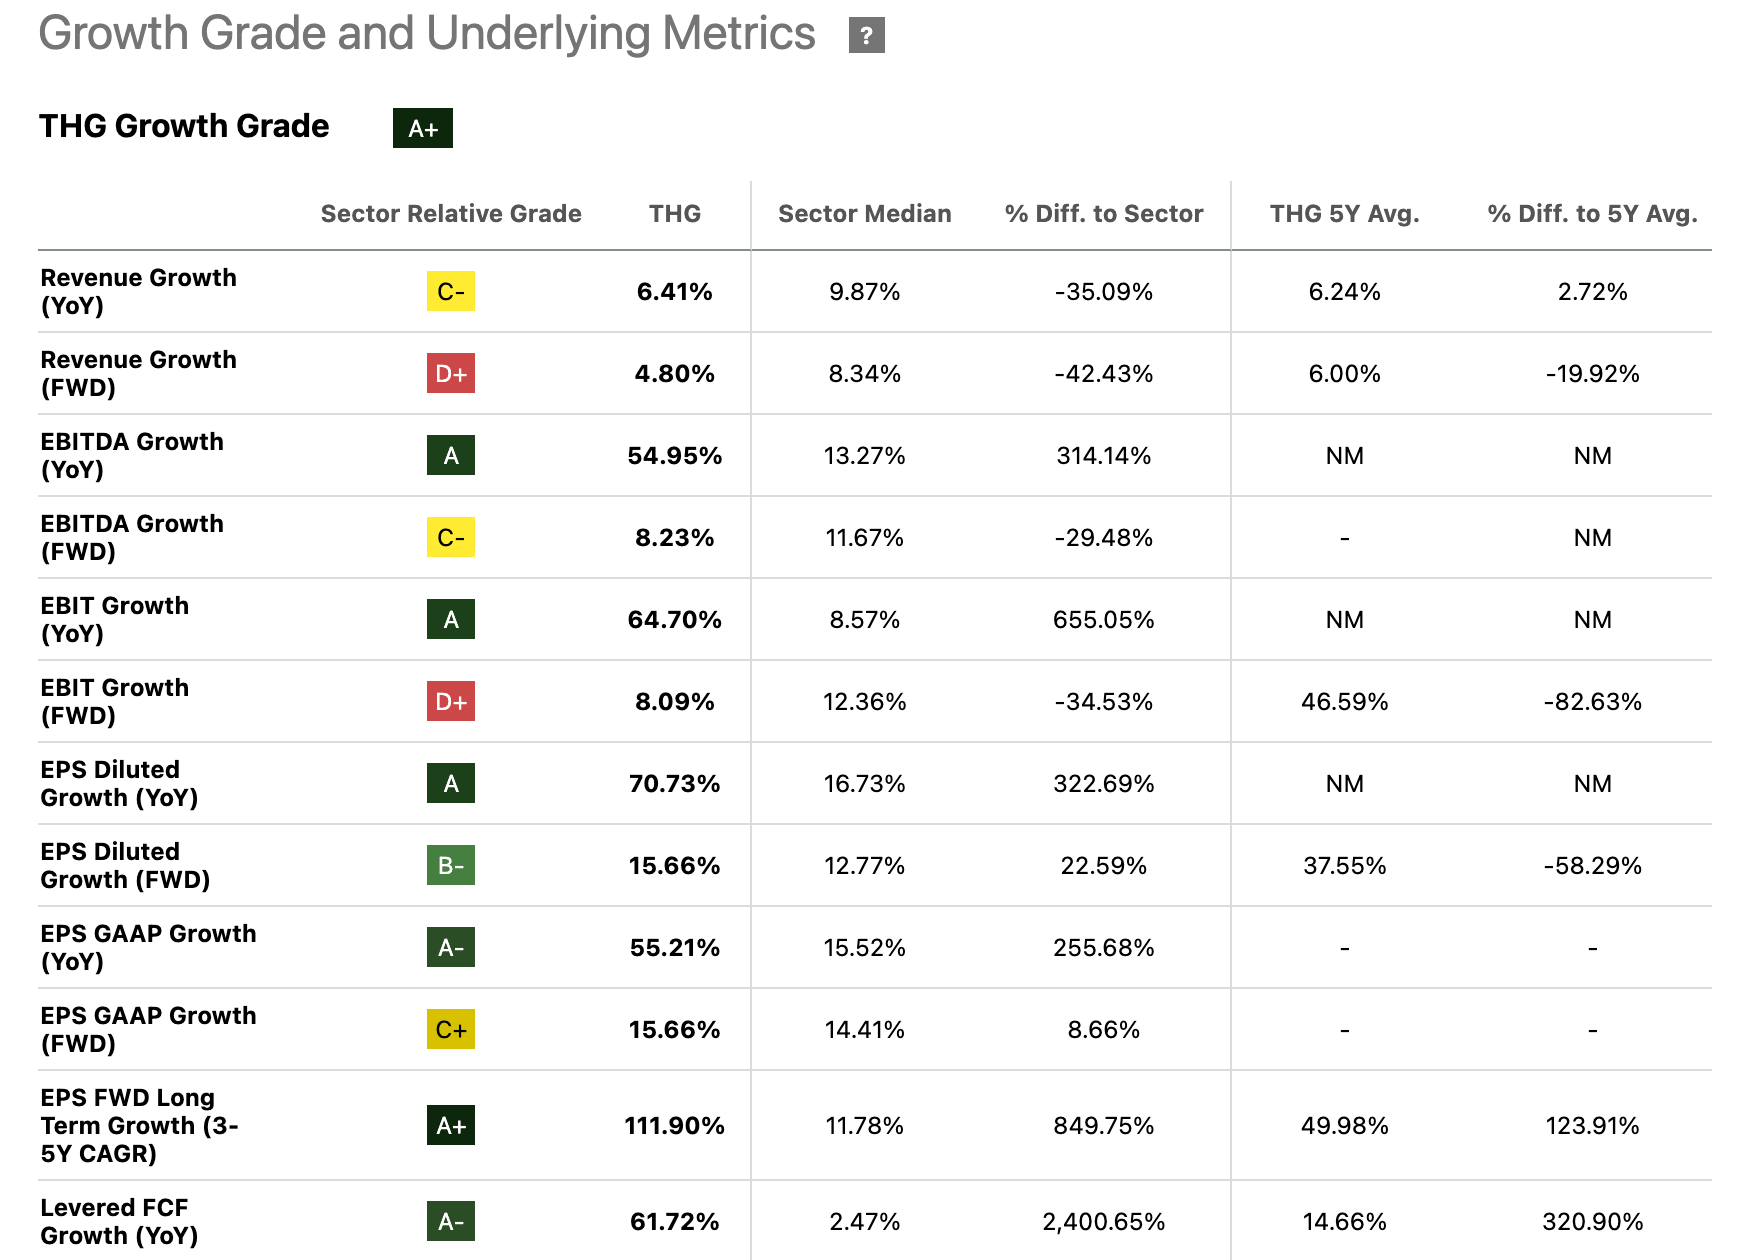
This recent financial success is a pillar of its ‘A+’ Growth Grade and is fueled by management’s expectations that its first quarter growth will continue to accelerate. This is illustrated below by its ‘A+’ grade in EPS FWD Long-Term Growth.
THG Quant Growth Grade
Seeking Alpha

Dividend Grade Scorecard

THG Dividend Scorecard
Seeking Alpha

THG’s Dividend Consistency Grade of an ‘A-‘ is backed by its two-decade track record of dividend payments, outpacing this reliable sector’s median of 15.7 years by over 27%. This should give investors prioritizing quality and reliability an appealing opportunity to capitalize on this uncertain inflationary climate.

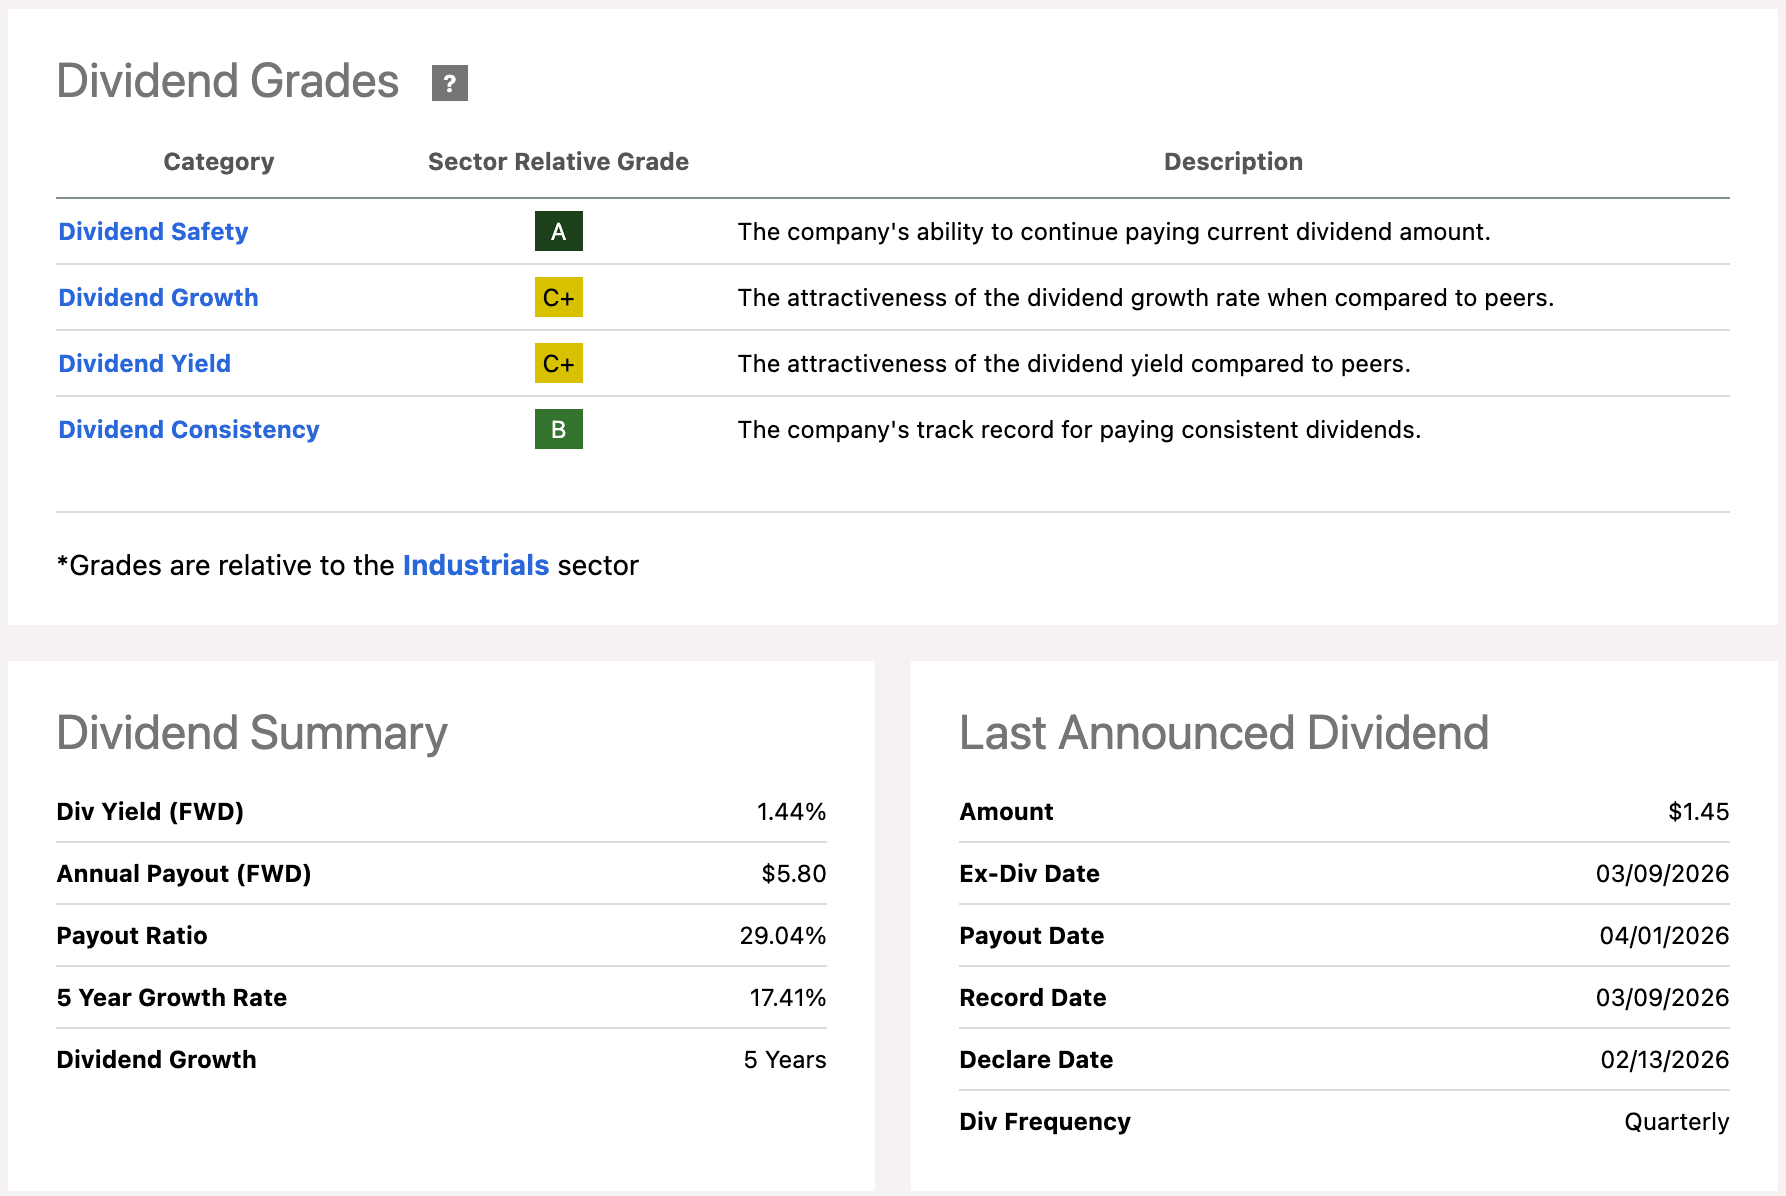
2. FedEx Corporation (FDX)

  • Market Capitalization: $93.93B
  • Quant Rating: Strong Buy
  • Sector: Industrials
  • Industry: Air Freight and Logistics
  • Quant Sector Ranking (as of 5/1/2026): 3 out of 611
  • Quant Industry Ranking (as of 5/1/2026): 1 out of 13
  • Dividend Yield (FWD): 1.47%

The Industrial Engine

When global energy markets are the catalyst for increased volatility, the industrial sector may not be the first place you look for value as it often feels the burden of rising energy costs quickly. But FedEx has proven to be an exception to that thinking.

The world’s largest express package provider was able to create internal efficiencies this year, unlocking tremendous value. Our Quant System currently rates FDX a Strong Buy, backed by an ‘A+’ Profitability Grade and an ‘A’ Momentum Grade that has improved consistently over the past year.
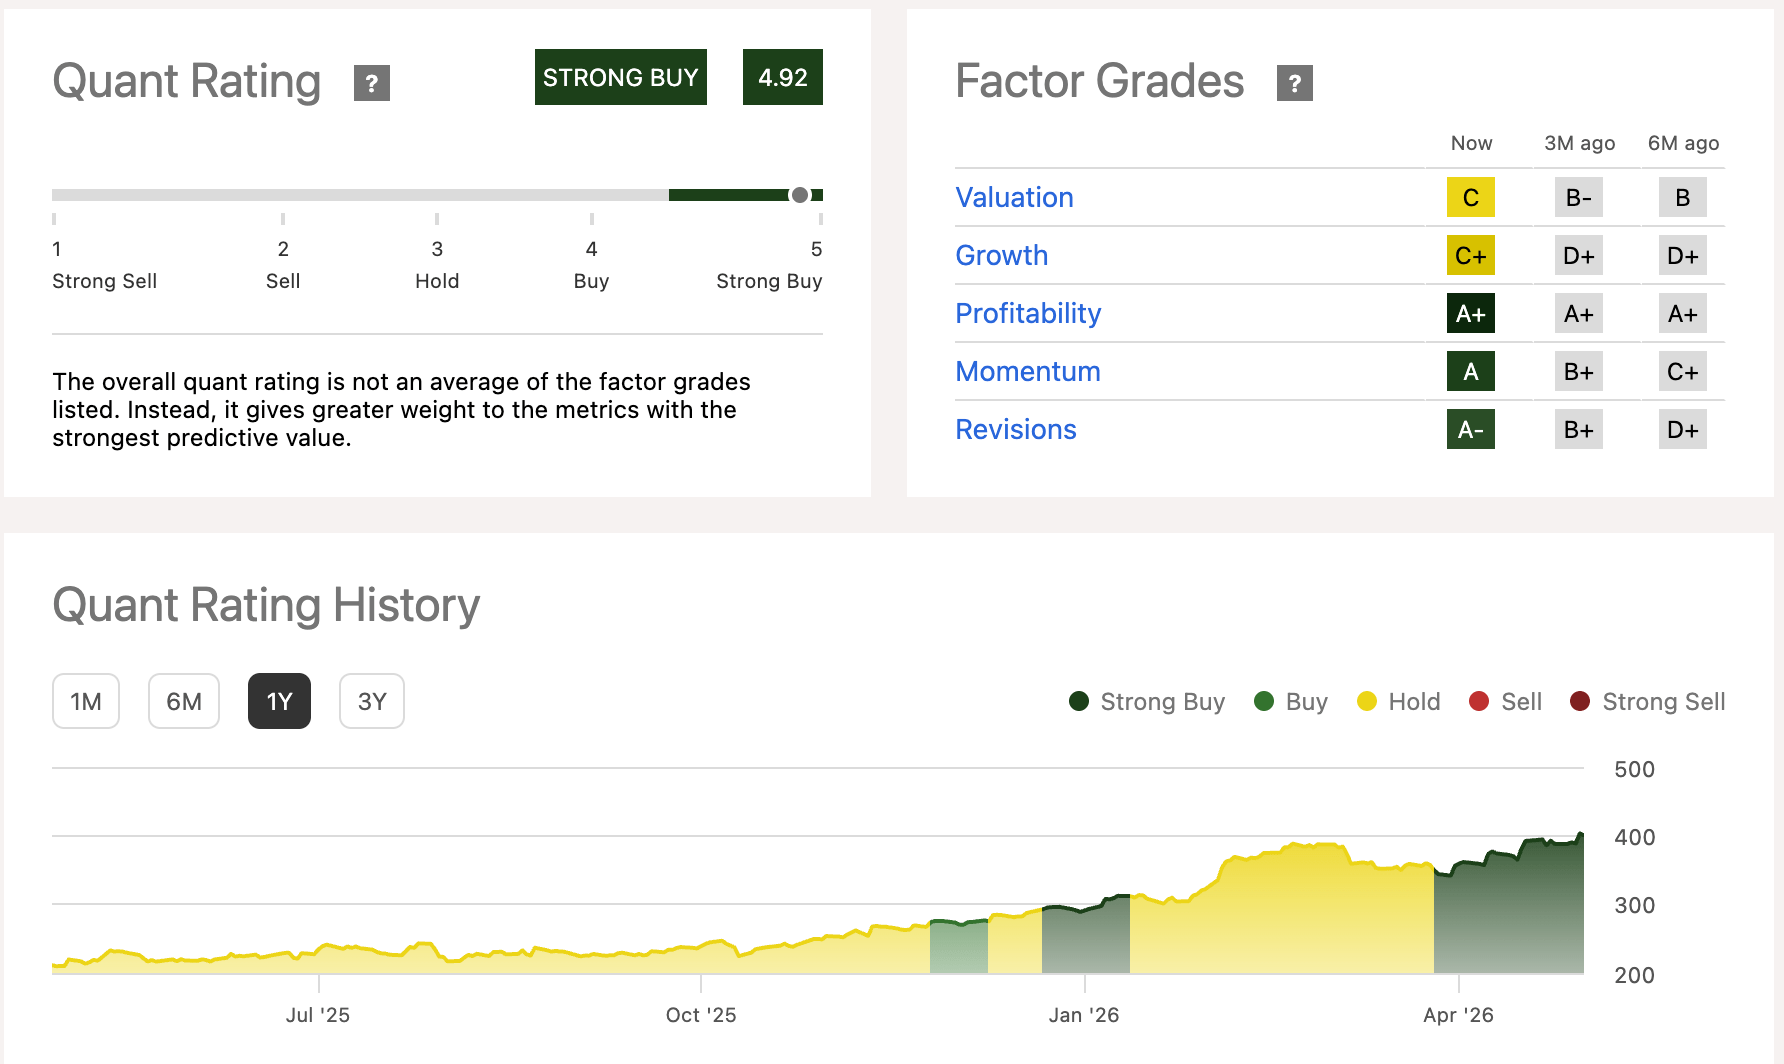
FDX Quant Scorecard
Seeking Alpha

FedEx showed remarkable revenue growth of 8% in FYQ3, with a 5% increase in U.S. domestic package volumes driven by significant account acquisitions resulting in increased market share. This is coupled with the tremendous success of its “DRIVE” program, which met its cost-savings target in FY2025, saving $2.2B.
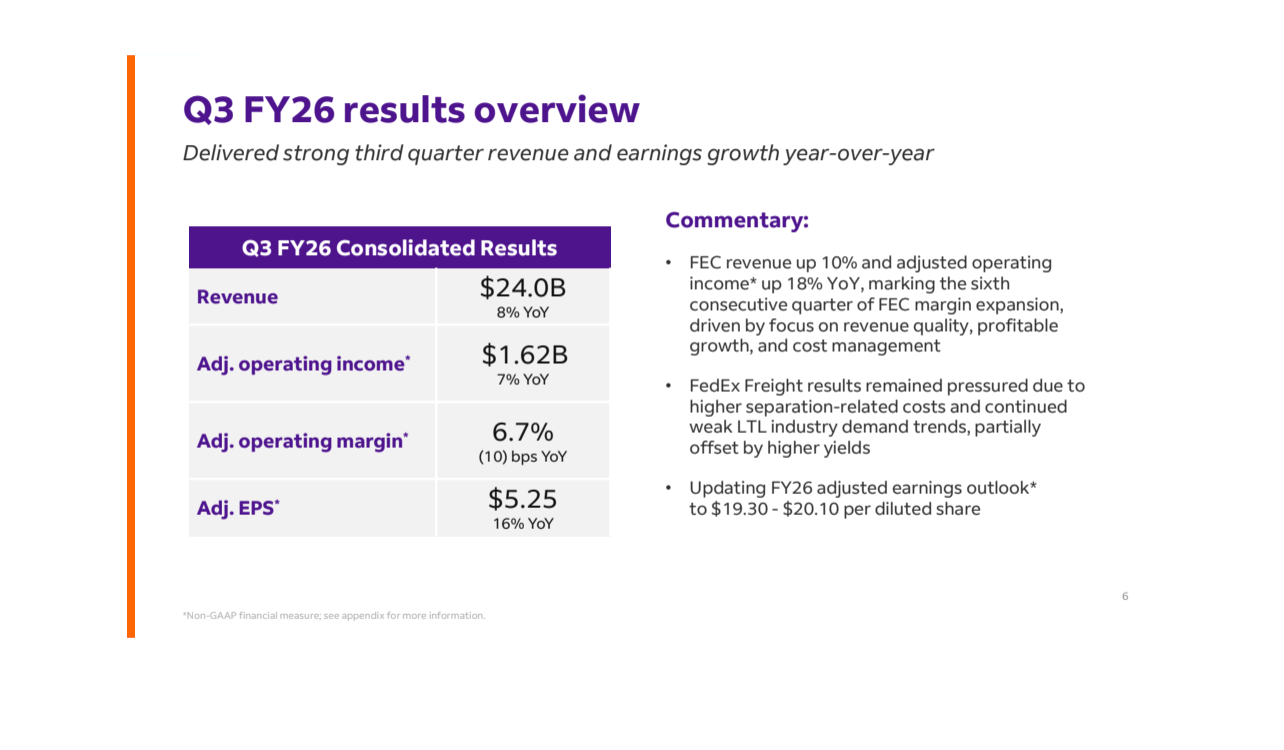
FDX Revenue Q3
FedEx FY2026 Q3 Earnings Presentation

Dividend Grade Scorecard

FDX Dividend Scorecard
Seeking Alpha

FedEx’s strong Quant Profitability Grade is a primary driver behind its ‘A’ Dividend Safety Grade. Led by its Cash From Operations (TTM) at $8.18B, a figure that trounces the sector median of $416.86M. At about 20x that of its Industrial peers, FedEx’s cash position provides a significant cushion to weather the temporary rise in energy costs while maintaining long-term strategic initiatives.

3. New Jersey Resources Corporation (NJR)

  • Market Capitalization: $5.65B
  • Quant Rating: Strong Buy
  • Sector: Utilities
  • Industry: Gas Utilities
  • Quant Sector Ranking (as of 5/4/2026): 7 out of 113
  • Quant Industry Ranking (as of 5/4/2026): 1 out of 13
  • Dividend Yield (FWD): 3.39%

The Utility Anchor

The final pillar of this VIG-beating trio provides the foundation for our all-weather grouping. New Jersey Resources Corporation (NJR) offers a non-discretionary staple of the utilities industry, securing stable and reliable cash flows that benefit from a supportive regulatory environment. NJR is comprised of five business units:

  • New Jersey Natural Gas
  • NJR Clean Energy Ventures
  • NJR Energy
  • Storage & Transportation
  • NJR Home Services
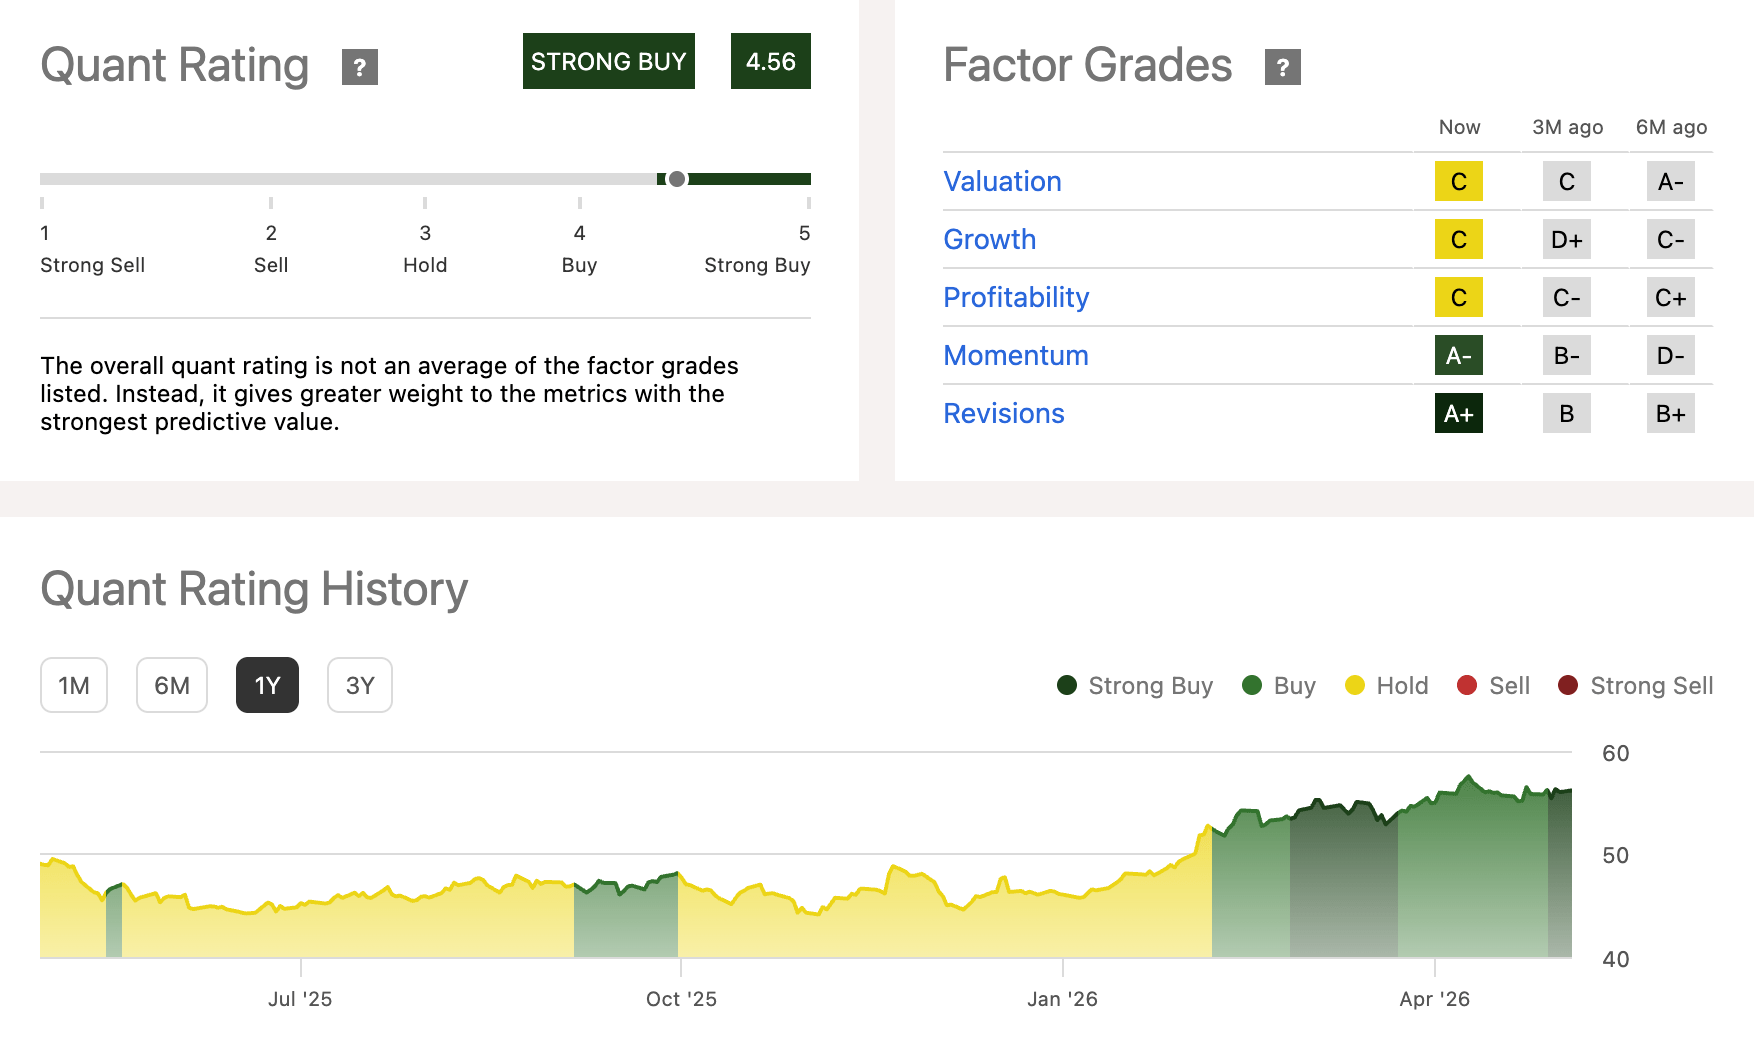
NJR Quant Scorecard
Seeking Alpha

Our Quant System currently highlights NJR’s rapid Momentum Grade increase – currently an ‘A-’, when only six months ago it was rated a ’D-’. Investors should consider capturing this momentum heading into the summer. As shown below, NJR’s 3M and 6M Price Performance both have strong ‘A’ ratings and beat the sector median by more than double. This recent uptrend has also led to six upward revisions to year-end EPS guidance.
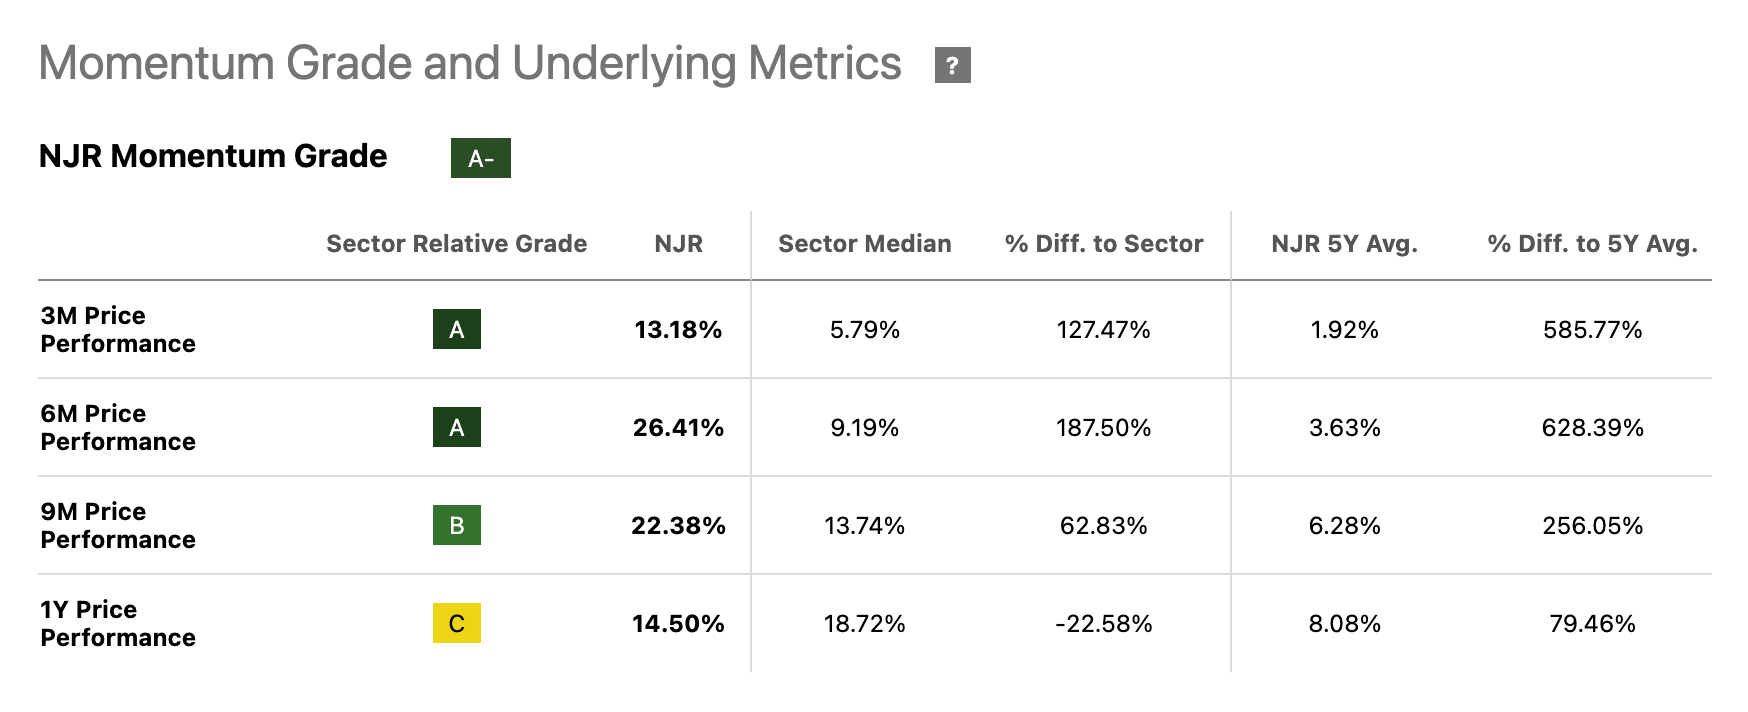
NJR Quant Momemntum Grades
Seeking Alpha

Before diving into the dividend grades, I want to address NJR’s low-rated Cash Per Share (TTM) metric. Unlike tech firms that hoard cash to buffer against volatile economic environments, utilities like NJR “hoard” active infrastructure. In this sector, cash not invested is an asset not being utilized for future growth.

Because returns are regulated, cash flows are only generated when infrastructure is active and in the ground. Income investors shouldn’t be concerned about a lean cash balance sheet because this process requires significant, continuous capital investment and is largely a byproduct of putting its capital to work. You don’t have to look very far to find proof of a healthy business model. Just take a look at its dividend payout history…

Dividend Grade Scorecard
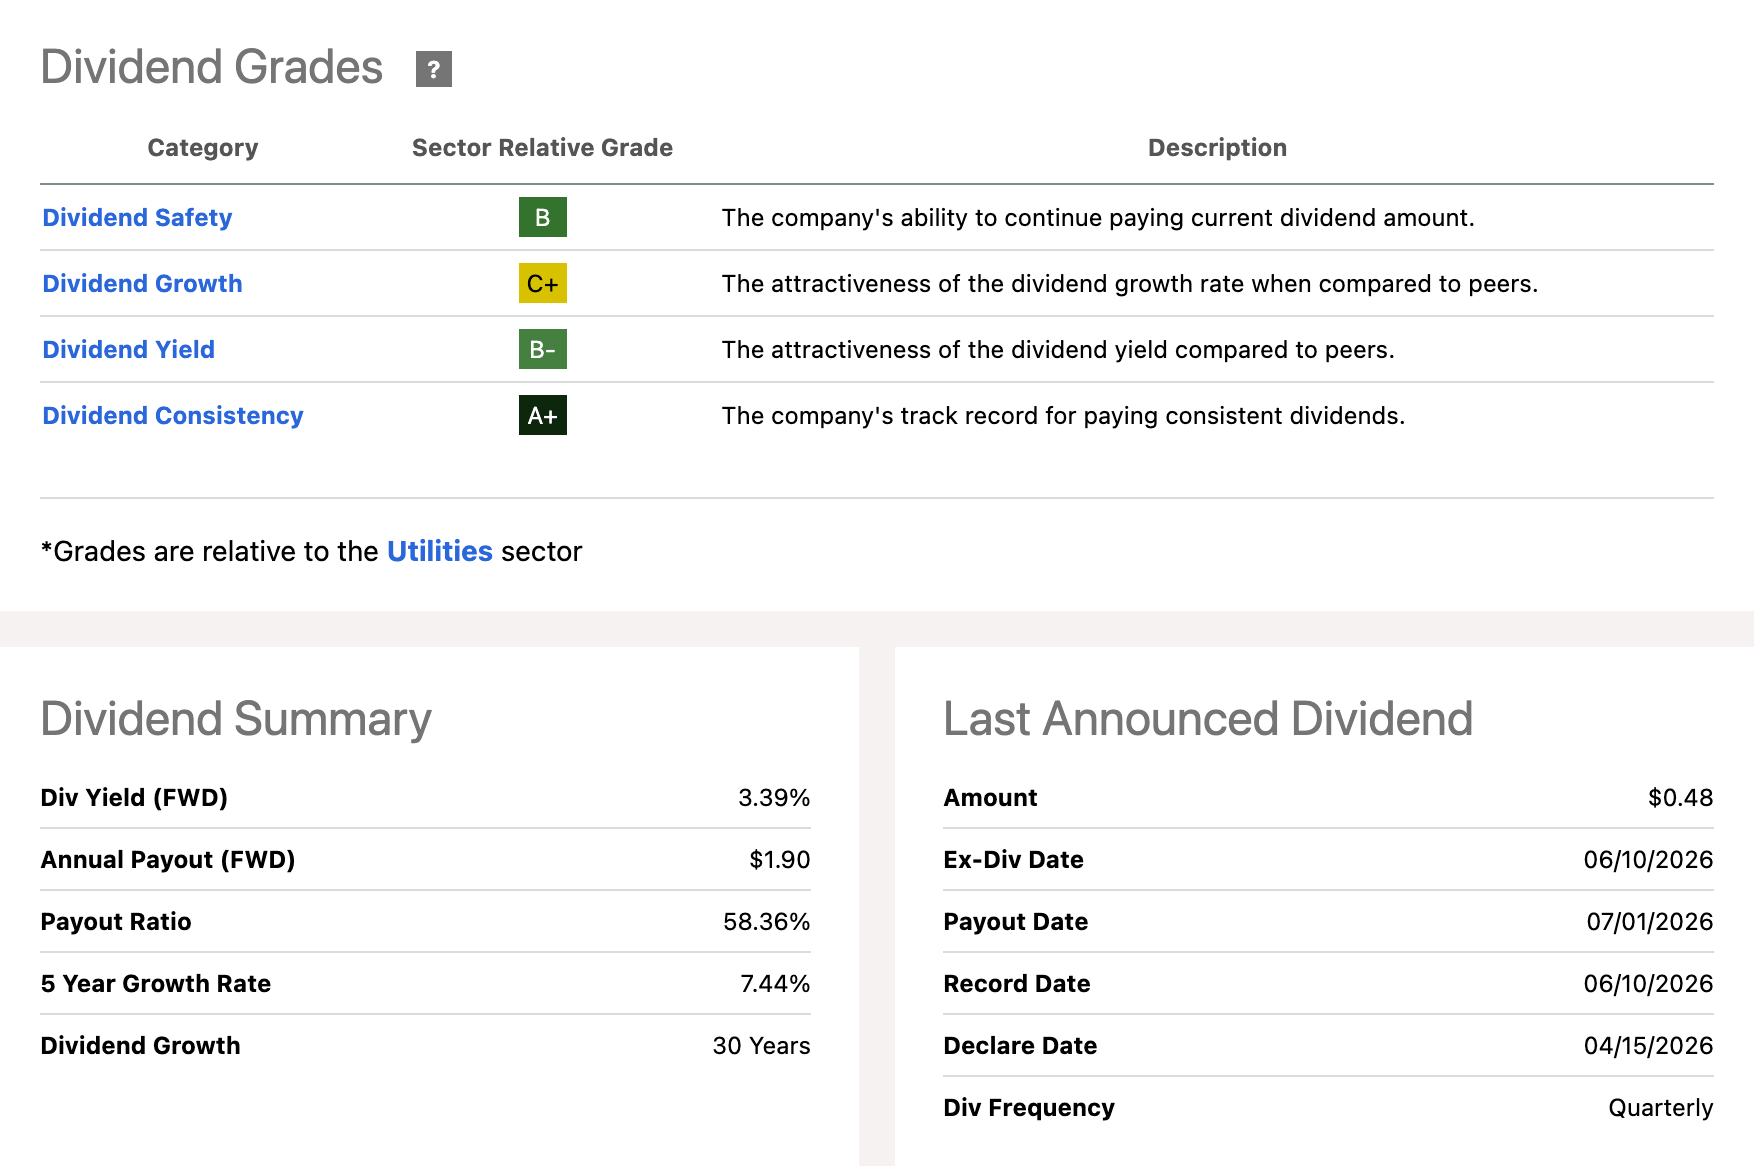
NJR Dividend Scorecard
Seeking Alpha

NJR’s reliable track record is underpinned by its strong dividend consistency grade, highlighted by an eye-popping 36 consecutive years of payments—including 30 straight years of growth. This reliability is matched by its strong income potential, with NJR’s Dividend Yield [FWD] standing at 3.39%, topping the sector median by 8.30%.

Looking Ahead: All-Weather Protection

This year has so far presented investors with curveball after curveball. However, you don’t have to sacrifice returns for safety, nor do you have to risk your portfolio for growth. You simply need a balanced, “quantamental” approach to income investing—one that finds the sweet spot of an all-weather portfolio.

While we hope inflation doesn’t stick around, income investors must be prepared for any scenario that comes down the pike later this year. If the first four months are any roadmap, more surprises are likely on the horizon, and this trio of all-weather stocks is ready to shield you from them.

More on my IG service

  • I am Steven Cress, Head of Quantitative Strategies at Seeking Alpha. I manage the quant ratings and factor grades on stocks and ETFs in Seeking Alpha Premium. I also lead Alpha Picks, which selects the two most attractive stocks to buy each month, and also determines when to sell them.

This article was written by

Steven Cress, Quant Team

Analyst’s Disclosure: I/we have no stock, option or similar derivative position in any of the companies mentioned, and no plans to initiate any such positions within the next 72 hours. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it. I have no business relationship with any company whose stock is mentioned in this article

Seeking Alpha’s Disclosure: Past performance is no guarantee of future results. No recommendation or advice is being given that any particular security, portfolio, transaction or investment strategy is suitable for any specific person. The author is not advising you personally concerning the nature, potential, value or suitability of any particular security or other matter. You alone are solely responsible for determining whether any investment, security or strategy, or any product or service, is appropriate or suitable for you based on your investment objectives and personal and financial situation. Steven Cress is the Head of Quantitative Strategy at Seeking Alpha. Any views or opinions expressed herein may not reflect those of Seeking Alpha as a whole. Seeking Alpha is not a licensed securities dealer, broker or US investment adviser or investment bank.
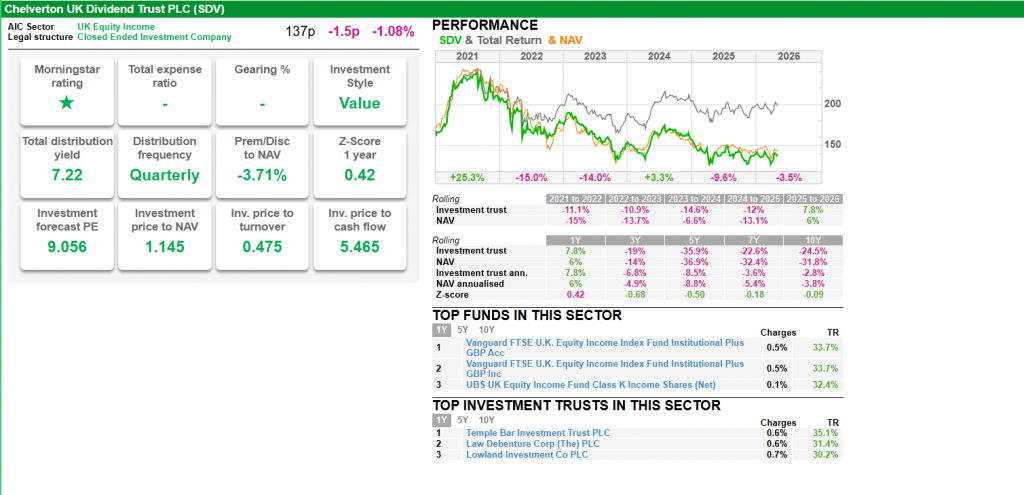
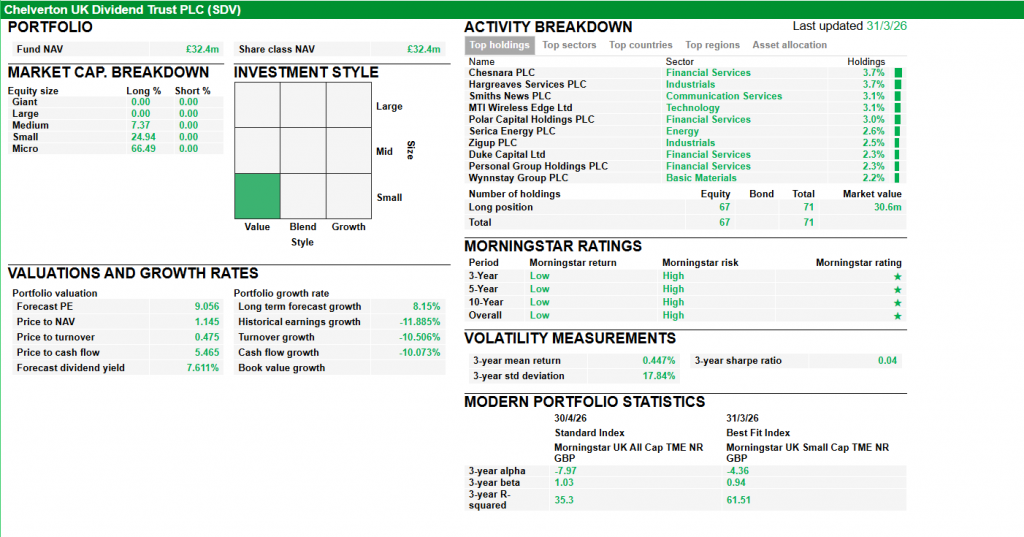
SDV

Higher risk because of it’s tiny market cap.

Could be one way to having a holding in the companies shown above.

SNOWBALL Research SDV

Chelverton UK Dividend Trust PLC

Half-Yearly Financial Report

For the Six Months ended 31 October 2025

Investment Objective and Policy

The Company’s investment policy is that:

•  the Company will invest in equities in order to achieve its investment objectives, which are to provide both income and capital growth, predominantly through investment in mid and smaller capitalised UK companies admitted to the Official List of the UK Listing Authority and traded on the London Stock Exchange Main Market, on AIM or AQSE or traded on other qualifying UK marketplaces.

•  the Company will not invest in preference shares, loan stock or notes, convertible securities or fixed interest securities or any similar securities convertible into shares; nor will it invest in the securities of other investment trusts or in unquoted companies. The Company may retain investments in companies which cease to be listed after the initial investment was made, so long as the total is non-material in the context of the overall portfolio; however, the Company may not increase its exposure to such investments.

Financial Highlights

 31 October30 April
Capital                                                                                                                        20252025%  change
Total gross assets (£’000)32,71830,3287.88
Total net assets (£’000)                                                                                        32,56829,8679.04
 
Net asset value per Ordinary share                                                                    145.07p   133.04p9.04
Mid-market price per Ordinary share                                                                  131.00p6.54%128.50p1.95
Discount                                                                                                                   (9.70%)(3.41%)
 
 
 Six months toSix months to
 31 October31 October
Revenue                                                                                                                    20252024% change
Return per Ordinary share                                                                                          3.57p6.41p(44.31)
Dividends declared per Ordinary share*                                                                 5.00p6.50p(23.08)
Total return
Total return on Group net assets**1                                                                          13.32%(23.82%)

* Dividend per Ordinary share includes the first interim paid and second interim declared for each of the periods to 31 October 2025 and 2024 and will differ from the amounts disclosed within the statement of changes in net equity.

** Adding back dividends distributed in the period.

1 These are alternative performance measures (‘APM’) (see APM glossary for further information).

Interim Management Report

This half-yearly report covers the six months to 31 October 2025. The net asset value per Ordinary share as of 31 October 2025 was 145.07 up from 133.04p as of 30 April 2025, an increase of 9.0% during the period. As at the 28 November 2025 the NAV per share has decreased to 143.69p.

Since the beginning of the Company’s financial year, the Ordinary share price has increased from 128.5p to 134.0p as of 31 October 2025, an increase of 4.3%. Since the period end the shares have slightly decreased in price to 133.0p and as at 28 November 2025 the shares traded on a discount of 7.4%.

Dividend

As previously indicated, the Board has resolved to use revenue reserves to supplement the income from the underlying portfolio in order to pay a dividend of 10.0p per share for the next three years, subject to market conditions at the time but assuming no increase in underlying portfolio income. In line with this intention, the first interim dividend for the current year of 2.50p per Ordinary share was paid on 10th October 2025. The Board has declared a second interim dividend of 2.50p per Ordinary share payable on 8 January 2026 to shareholders on the register on 12 December 2025, making a total for the half year of 5.0p per Ordinary share.

It is anticipated that the Company will maintain the level of dividend for the third and fourth quarter at

2.5p making a total core dividend declared of 10.00p for the year.

Portfolio

In the last 6 months we have repositioned our portfolio following the ZDP redemption at the end of April 2025. We increased investment in ten of our existing holdings (2024:16), B&M Europe, Chesnara, Conduit Re, Foresight Group Holdings, Gateley Plc, ITV, Polar Capital, Serica Energy, Vesuvius and Zigup.

During the period we also added nine new names to the portfolio (2024: 9). These were British Land Co – real estate investment and development; Bytes Technology Group – IT solutions and services; Hilton Food Group – meat and fish packaging; Hollywood Bowl – leisure; Man Group – investment manager; Next 15 Group – consultancy; Primary Health Properties – healthcare REIT; Taylor Wimpey – housebuilder; and Tristel – hospital disinfection products.

Funds were raised from the outright sale of two of our holdings Bakkavor Group and Epwin Group, both of which were the subject of takeovers.

The following holdings were reduced on yield grounds: Arbuthnot Banking Group, Coral Products, DSW Capital, Kier Group, LendInvest, M.P. Evans Group, One Health Group, Orchard Funding Group, Palace Capital, Personal Group, Ramsdens Holdings, Sancus Lending Group, Smiths News and Stelrad Group.

From a performance perspective there was no real theme to the biggest movers in the period, with our top contributors and detractors largely reflecting individual company circumstances. On the downside Hilton Foods suffered due to an operational issue at its Greek smoked salmon facility, which impacted exports into the US. STV Group suffered from a slowdown in demand for its Studios business and B&M Europe shares fell reflecting a weak trading update, followed by a second update highlighting increased freight costs. On the positive side Serica Energy shares rose over 70% in the period, reflecting accretive M&A activity alongside expectations of a more hospitable regulatory environment for UK North Sea assets. Johnson Matthey reacted well to the disposal of its Catalyst Technologies business at an attractive price, Polar Capital benefitted from strong asset performance leading to increased AuM and Chesnara shares re-rated along with the wider Life Insurance sector as interest rates fell.

Outlook

The past six months have been a volatile period as markets tried to absorb the combined impacts of US trade tariffs, differing trajectories of interest rate cuts across western economies and the ever-evolving effect of the adoption of new technologies. From a UK perspective, a level of political uncertainty rarely seen under a government with such a large majority is adding to the general sense of unease, not helped by the long wait for this year’s “Autumn” Budget. The result of this has been a collapse in both corporate and consumer confidence, delays in business investment and a historically high household savings ratio.

There has undoubtedly been a sense of pessimism amongst investors around UK domestic equities, and UK small and midcap stocks in particular, however it’s not all doom and gloom. The most significant hurdles for the UK economy over the past couple of years have been the intertwined issues of high interest rates and high inflation, both of which we believe are now set to start moving in the right direction.

The Budget has been calmly received, as much of it had already been leaked, and the bond markets have been reassured by the level of headroom created. Unfortunately, there were no initiatives for advancing development and growth which of course would help GDP growth, higher government revenue and a consequent reduction of deficit financing. Our companies will have to manage another significant rise in the minimum wage of 4.1% and even higher increases for younger people.

Inflation is set to fall over the next year as several one-off factors in 2025 fall out of the calculation (national living wage and national insurance increase, energy price rises etc), which should allow the Bank of England to continue its current path of interest rate cuts into next year. We have already seen mortgage rates fall significantly from their peak and banks remain incredibly well capitalised.

As we have commented before, the strength of UK corporate balance sheets is neatly evidence by the scale of buy-back activity currently being undertaken, while consumer balance sheets have been bolstered by wage increases and increased savings. This means the raw material for growth is readily available, what is lacking is the confidence to deploy it.

As we look past the recent budget, a more stable economic environment combined with reducing interest rates and strong corporate balance sheets has the potential to be a powerful combination both for the UK economy at large and UK small and midcap equities.

In the meantime, we continue to be impressed by the resilience of cash flows within our underlying portfolio and the adaptability of our investee companies to the difficult macro environment. Dividend payments remain strong and we are confident that our management teams are positioning businesses to benefit from an uptick in demand when it happens.

Chelverton Asset Management Limited

4 December 2025

The SNOWBALL has avoided owning SDV as there ZDP’s had first call on any cash in a market crash. Having redeemed the ZDP’s they fill several requirements to be included in the SNOWBALL.

Bull Case

A yield of 7.5%, fcast dividend for the next couple of years, investing in Smaller Companies, where research shows they outperform as Elephants can’t run. Diversification away from Renewables whilst maintaining a higher dividend yield.

Bear Case

Trades at a small discount to NAV

From the commentary inflation is not going to fall but rise

BSIF

Calling Time on BSIF

The Oak Bloke May 5

Feeling Blue on Bluefields

(This article was released on YouTube on May 4th, May the fifth be with you who didn’t tune in)

Bought BSIF Bluefield Solar at 68.2p and May 1st sold at 83.8p. Thanks for being man’s best friend, Bluey.

But it’s time to give you the shoe-y Bluey. Bwooah! May the fourth is not with you Bluey, sorry. Don’t write in or call the RSPCA, no actual dogs were harmed in the making of this article. Not even in a galaxy, far, far, away.

And you can thank Ed Milli for the boot, Bluey. That tinker.

Tinkering with contractual agreements. A deal’s a deal. But not for Milli. The UK government who were elected on a mandate of GROWTH. Deal breaking is a terrible way to support deal making. Ah well. Its supporters will be happy and broad shoulders can bear the burden. Will renewables investors nursing heavy capital losses now bear new income losses too? Exactly. It’s true that voters were promised lower bills due to green energy? Short term – that’s what they’ll get.

But it makes UK renewables uninvestable in my opinion, due to Milli’s measures taken to reduce bills:

  1. Milli has removed 75% of the Renewables Obligation
  2. Hiked the Electricity Generator Levy to 55% on revenues above £82/MWh. While oil and gas giants get “investment allowances” to offset their windfall taxes, perversely renewable generators have been hammered with a high headline rate that doesn’t offer the same generous loopholes for reinvestment as fossil fuels.
  3. Milli is “strongly encouraging” legacy renewable generators to move off their lucrative old market-linked contracts and onto fixed-price Contracts for Difference (CfD). It’s being framed as a “voluntary” move to de-link from gas and electricity prices, but the subtext is clear: renewables generators who don’t “volunteer” may face even harsher tax treatment or grid-access deprioritisation. It’s effectively a retrospective raid on the profits of projects built a decade ago.
  4. In an embarrassing admission in April 2026, Ofgem and the government admitted they’ve “over-allocated” grid capacity to battery storage, leading to a regulatory freeze. New rules are being fast-tracked to limit or cancel new battery projects unless they already have revenue support. After telling the industry that storage was the “backbone” of the transition, they are now pulling the rug out from under developers who spent millions on planning and land rights, claiming the system is “overwhelmed.”
  5. Blunders and resets. The newly formed NESO (National Energy System Operator) has been forced to “reset” timelines, effectively telling shovel-ready solar and wind farms to get back in line because the previous administration’s “zombie projects” (projects that exist only on paper) weren’t cleared out properly.
  6. What else does he plan to do too?

Good luck to readers continuing to invest and tempted in this area (I’m sure I’ll get some robust rebuttals on this and some harrumphing) but I’ve decided it’s not for me.

Could the sale of BSIF still yield upside? Yes of course, and it’s got an attractive yield. Or had. Could it be harder to sell the portfolio to a new buyer given Milli’s tinkering? I think so. How can international investors invest into the UK when the rules are akin to those of a Banana Republic. I’m happy to take the 22.9% gain.

Current yield 10.6% so still a hold but maybe time for re-investing the dividends outside of Renewables.

Change to the SNOWBALL

I’ve always wondered if you can improve your Snowball by dividend washing, where you buy a share just before it’s xd date and sell just after.

With most shares the price is marked down by the dividend or more but sometimes it’s not.

The market could dump on u if you before too early before the xd date.

You are liable to lose some capital on the transaction, although if you are lucky, you could earn the dividend and make a capital gain. The aim of the SNOWBALL is to increase the yearly income buy buying shares and re-investing the dividends, whilst retaining the capital and slowly increasing the seed capital invested. As the intention is never to kill the golden goose by selling any golden eggs, it’s not the primary aim of the SNOWBALL

I have sold £200 of TRIG, after allowing for costs at break even, as I needed the funds to buy 1k of GCP, ahead of their xd date this week.

Dealing costs of buying 1320 shares in GCP, including the spread £15.28.

The SNOWBALL has 5k of shares in GCP, so I intend to use this position to do some dividend washing.

The parameters is too restrict the loss of capital to £500 and to re-invest the dividends back into the SNOWBALL. A by product of any dividend washing it makes it easier to achieve this year’s fcast.

If you now jump forward ten years, if the earned dividends are £500 and re-invested at 7%, the income will be 1k per year for the rest of your Snowball, against the loss of capital and the income from any capital loss

The biggest danger to the plan is if you buy a clunker, so the plan is not too hold the new position for very long. The amount for dividend washing may be increased to 10k, subject to the outcome of the first few trades.

The earned dividend for GCP will be £118.00

Only a concept at this stage, as more pondering needs to happen.

XD Dates this week

Thursday 7 May

Artemis UK Future Leaders PLC ex-dividend date
Chenavari Toro Income Fund ltd ex-dividend date
CT Healthcare Trust PLC ex-dividend date
CVC Income & Growth EURO Ltd ex-dividend date
CVC Income & Growth GBP Ltd ex-dividend date
Dunedin Income Growth Investment Trust PLC ex-dividend date
GCP Asset Backed Income Fund Ltd ex-dividend date
GCP Infrastructure Investments Ltd ex-dividend date
Marwyn Value Investors Ltd ex-dividend date
North American Income Trust PLC ex-dividend date
Picton Property Income Ltd ex-dividend date
Supermarket Income REIT PLC ex-dividend date

If you buy SUPR before Thursday, you will receive 5 dividends in just over a calendar year. The current dividend 1.545p equates to a yield of 7.25%.

The enhanced yield equates to a yield of around 9%.

If interest rates rise, as fcasted, the price may fall but you could use that as an opportunity to re-invest your dividends back into the share, buying more shares and earning more dividends, as you wait for interest rates to start falling again.

Across the pond

10% Dividends (at a 10% Discount) From This “Hated” Stock Rally

Michael Foster, Investment Strategist
Updated: May 4, 2026

This has got to be the most “hidden” (maybe hated?) stock-market run I’ve ever seen.

The headlines are all doom and gloom (I think you’ll agree), but behind it all, the stock market is on a roll—returning 31% in just the last year. That’s more than triple the market’s long-term average yearly return of around 10%.

Where does that leave those of us who look to stocks for growth and income? Is there more runway ahead, or is it too late to buy in?

In my opinion, this 31% gain is setting the table for more, and we’ll get into exactly why in a moment. The setup we’ll break down is doubly attractive for investors in closed-end funds (CEFs), where we can get a discount on what we’d pay if we bought stocks through an ETF or directly on the market.

9%+ Yielding CEFs Give Us a Discount No Matter What the Market Is Doing

Our discount opportunity on CEFs exists in part because the CEF market is tiny, containing only about 400 funds. And CEF buyers tend to be individual, conservative investors.

That second point is key because these investors buy and sell predictably—and they always leave a “discount window” open for us somewhere. Plus, with CEFs, we can forget about the 1% dividend your typical index fund pays. CEFs often yield 9% and more, which means we’re getting the bulk of our return in cash.

I bring CEFs up now because I want to take on today’s stock-market setup—and our plan to buy into it—in two tracks.

First, we’re going to look at why this stock-market run is justified and not at all a bubble. Simply put, this means that a 31% gain in the rearview does not preclude a similar rise looking ahead.

For the second track, we’re going to move from the general to the specific, with a CEF seemingly purpose built to get us into this rise at a discount and a 10.3% dividend, too.

Track 1: An Economy Rolling Through Gloom

Before we go further, I know my bullishness on the economy might seem a little out of step right now, with the Strait of Hormuz closed, cutting off vital resources like oil and fertilizer; rising fear of job losses; and consumer sentiment that hit record lows in April.

Let me counter that gloomy narrative by starting where we always need to start when we’re talking about stocks: earnings.

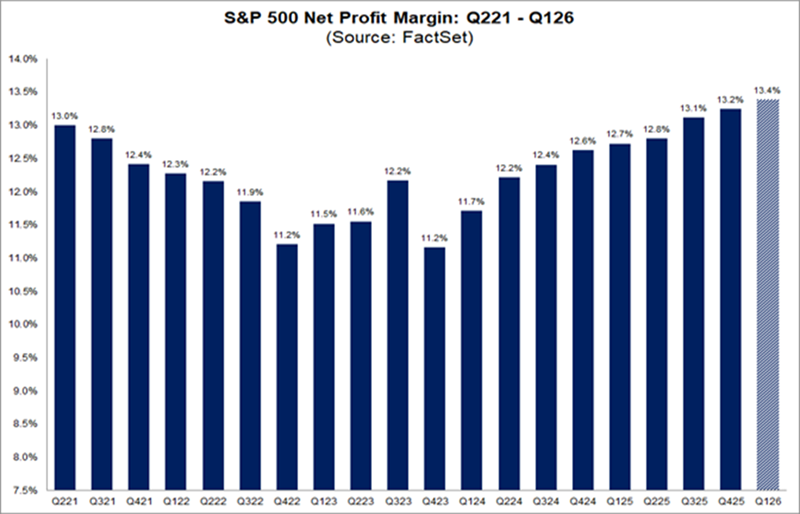
And thanks in large part to tech breakthroughs (AI, in other words) productivity is jumping, and those gains are showing up in strong corporate earnings growth. As of the end of 2025, profit margins had hit levels unseen in years, with more gains forecast:


Source: FactSet

And contrary to popular opinion, these productivity—and profit—gains are not coming at the expense of jobs. As I discussed last week, we’re starting to see data telling us that AI is, in fact, creating jobs. Over time, the resulting employment gains are likely to create opportunities for workers and companies to earn and spend, unlocking even more value from the stock market.

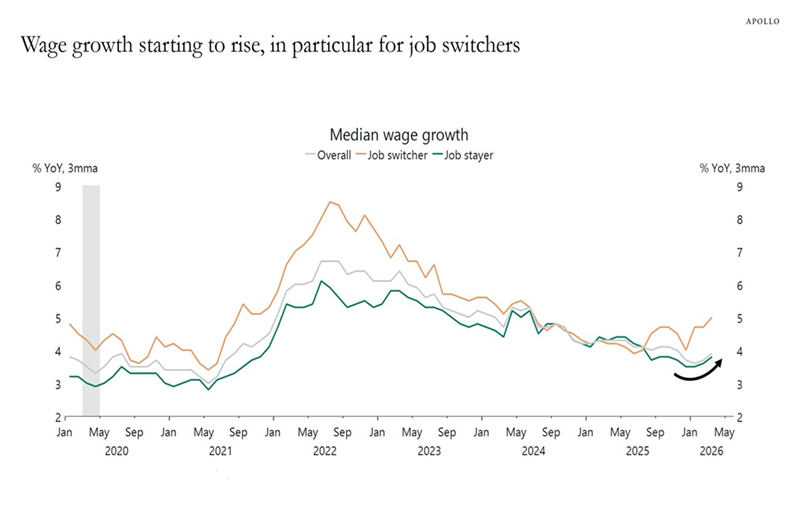
Here’s another report that backs this up (and pushes back on the whole “AI job apocalypse” narrative):


Source: Apollo Global Management

The chart above tells us a specific story: Workers moving from one job to another are likely to see their income rise—and significantly. This shows that companies are putting more emphasis on hiring, and are willing to pay for top talent. That’s another clear sign of a strong US economy.

Track 2: Our Bargain “Backdoor” On This Market Run

With all that said, it’s still easy to feel as if we’ve missed the bulk of the market’s upside. But with profits growing, and more money flowing through the economy, more gains are likely. And with a discounted CEF, as mentioned, we can do even better.

That’s because with CEFs we’re getting most of our return in cash, and we’re getting these funds for less than their portfolios are worth.

Consider a CEF called the Liberty All-Star Equity Fund (USA).

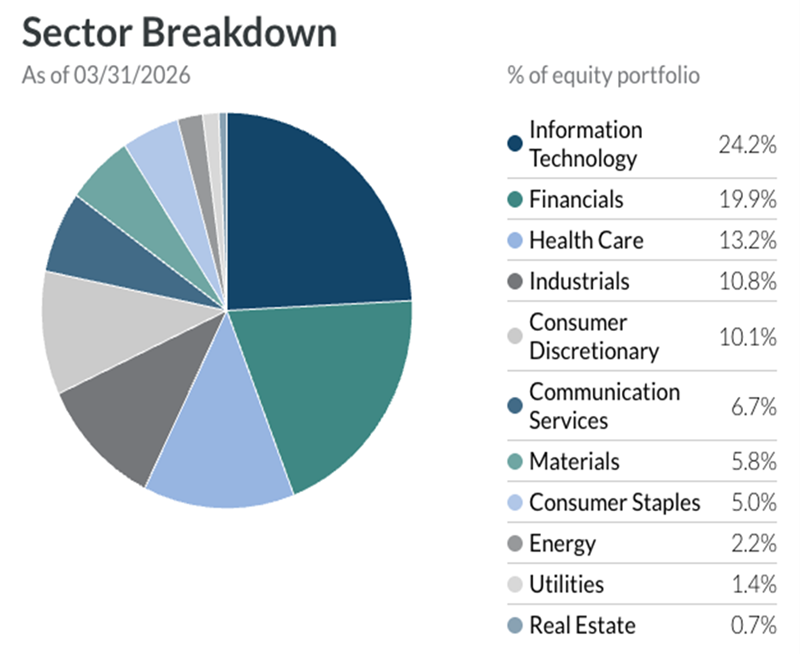
With a 10.3% yield, this fund pays nearly 10X what the average S&P 500 index fund does, while its large-cap focus means we get access to many of the same stocks: NVIDIA (NVDA), Microsoft (MSFT), Alphabet (GOOGL), Amazon.com (AMZN), Visa (V) and Charles Schwab (SCHW) are all main holdings, and USA is diversified in a way similar to the S&P 500 itself:


Source: Liberty All-Star Funds

USA takes the returns on these holdings and “converts” them into an income stream for us. It manages that 10.3% payout by linking the dividend to net asset value (NAV, or the value of the fund’s underlying portfolio) and committing to paying out roughly 8% of NAV as dividends every year, in four quarterly installments of 2%.

That does mean the payout floats a bit, but we’re okay with that, since this 8% “NAV peg” has resulted in a payout that’s been pretty consistent over the last three years:

USA Delivers Steady Dividends in Choppy Markets

Source: Income Calendar

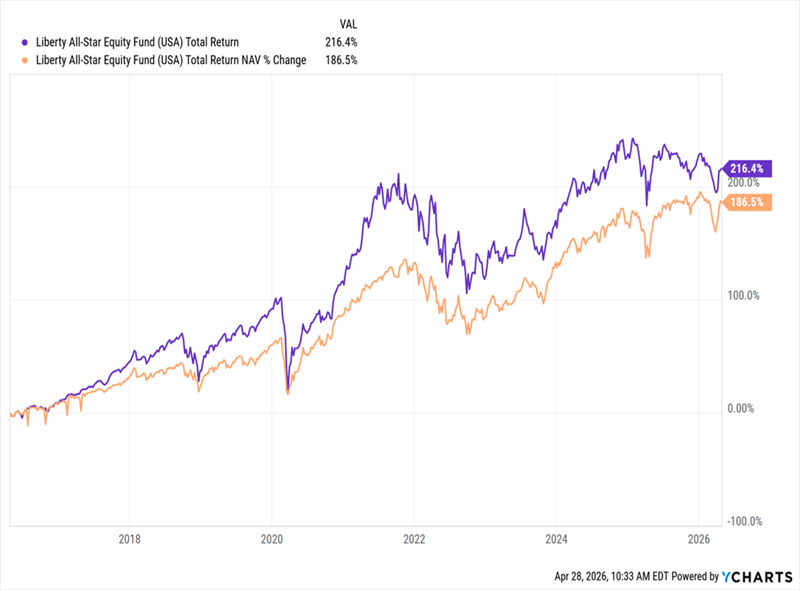
Moreover, the fund’s strong returns over the last decade—216% on a market-price basis (in purple below) and 187% based on NAV (in orange)—have been more than enough to keep USA’s payout rolling out at a high rate. With the economy’s strong (and improving) prospects, I see that continuing:

USA’s Market Price (and Portfolio) Deliver

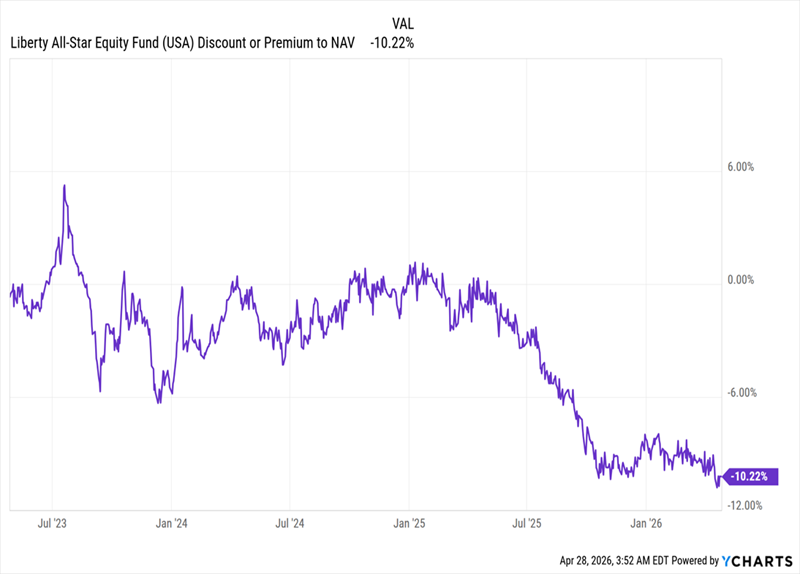
That gap between the fund’s own performance and that of its portfolio is unique to CEFs. As you can see at right in the chart above, it’s narrowed lately, setting up the discount opportunity you can see in the chart below:

USA’s Discount Hits COVID-Era Lows

USA now trades at a 10% discount to net asset value (NAV, or the value of its underlying portfolio). That’s far below its 4.2% long-term average and the lowest it’s been since the dark days of COVID. It’s also far too large of a markdown for a large-cap fund that’s performing (and maintaining high dividends) as well as this one is.

Moreover, any gains in the stocks USA holds are likely to compound as the fund’s discount narrows over time.

This leaves us with a fund sporting a big yield, strong performance and a discount unseen since COVID. And that deal comes at a time when the economy is strong and growing. It’s a situation that clearly shows why CEFs are our first stop when we’re hunting for value, no matter what the rest of the market is doing.

These 5 Overlooked Funds Pay Dividends 60 Times a Year, Yield 9.7%

USA’s “floating” dividend is actually unusual among CEFs. Many pay monthly, in fixed, predictable amounts.

Investors in “regular” stocks and ETFs almost never get that luxury!

Nothing in Contrarian Outlook is intended to be investment advice, nor does it represent the opinion of, counsel from, or recommendations by BNK Invest Inc. or any of its affiliates, subsidiaries or partners. None of the information contained herein constitutes a recommendation that any particular security, portfolio, transaction, or investment strategy is suitable for any specific person. All viewers agree that under no circumstances will BNK Invest, Inc,. its subsidiaries, partners, officers, employees, affiliates, or agents be held liable for any loss or damage caused by your reliance on information obtained.

Reinvesting dividends:KISS

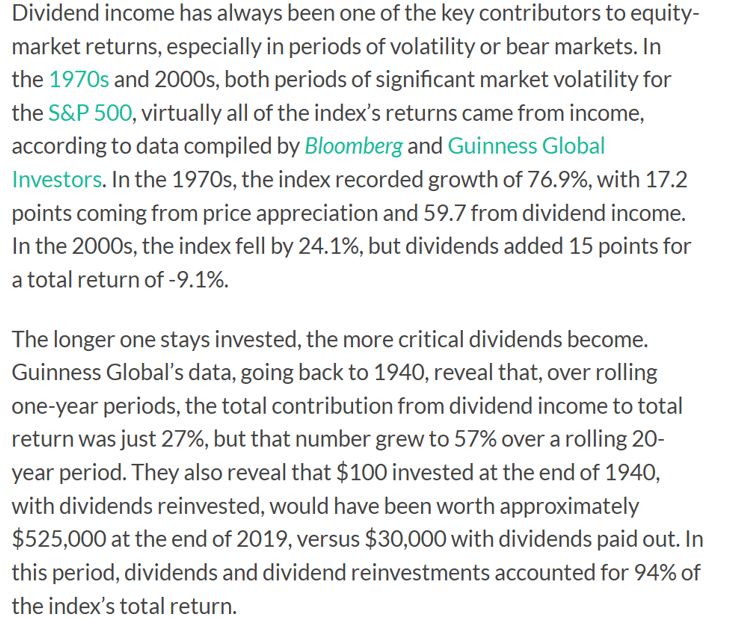
Reinvesting dividends: why it could leave you £30,000 better off

Dividend paying companies in your portfolio can provide a reliable income but potentially millions of investors are missing out on thousands of pounds by not reinvesting dividends

By Laura Miller

A man looking at his dividends on his phone
Dividend paying companies in your portfolio can provide a reliable income but potentially millions of investors are missing out on thousands of pounds by not reinvesting dividends(Image credit: Getty Images)

Reinvesting dividends offers a sure-fire way to boost your returns and increase your chances of outsized gains from your investments over the longer term. But many investors are missing out – new research has suggested they could be leaving nearly £30,000 on the table over the long term.

Dividends are payments made by a company to its shareholders, representing a portion of the company’s profits. They are a way for companies to share their success with investors and can be paid out in cash or additional shares of stock.

Investors keen not to disturb their capital and to keep it growing, often draw down just the dividends, creaming those extra payments off the top of their fund for an income, especially in retirement as part of a pension. Some investment funds are designed for investors to take dividend income this way.

Get 6 free issues +
a free water bottle

Stay ahead of the curve with MoneyWeek magazine and enjoy the latest financial news and expert analysis, plus 58% off after your trial.

But while dividend-bearing investments are particularly important for income seekers, long-term academic studies on the returns from UK equities have proven that they overwhelmingly account for most of the real return (after inflation) of the UK stock market.

Jason Hollands, managing director at wealth manager Evelyn Partners, said: “Where dividends are reinvested, rather than taken, this creates a very powerful compounding effect.

“This means investors benefit not just from the returns on the original cash invested, but also the returns on the gains made on the dividends which are ploughed back into further share purchases.”

Impact of not reinvesting dividends

Investors’ dividend decisions – to reinvest or not reinvest – can have a significant impact on long-term returns, analysis from Hargreaves Lansdown found.

Over the past year – March 2025 to February 2026 – 698,000 Hargreaves Lansdown clients received a total of £1.25 billion in dividend income, an average of £1,795 per investor.

Around one in three (31%) are set to automatically reinvest their dividends. In contrast, six in 10 (59%) leave their dividend income as cash on the platform. One in 10 (10%) withdraw it to a nominated bank account (some investors may invest cash balances later).

Hargreaves modelled the outcomes of reinvesting dividends compared with taking them as cash, using a FTSE All-Share tracker. Over longer time periods, the difference in outcomes is stark.

A £10,000 investment over 10 years could grow to around £22,000 if dividends are reinvested. This compares to an approximately £16,000 capital return and a £4,000 dividend payout. Over 20 years, this rises to nearly £34,000 with dividends reinvested, but only around £17,500 in capital return, and a dividend payout of around £7,500.

Emma Wall, chief investment strategist at Hargreaves Lansdown, said younger investors have the most to gain by reinvesting dividends.

“Over 30 years a £10,000 investment could grow to around £74,000 if dividends are reinvested, compared with just £29,000 capital return and £15,000 dividend payout. This means investors could miss out on just shy of £30,000 if the dividend income is kept on account.”

PeriodCapital return, with dividend payouts left on accountTotal return (dividends reinvested)Difference in % terms
10 years98.80%122.97%24.5%
20 years151.85%239.56%57.8%
30 years347.39%640.49%84.4%

Source: Hargreaves Lansdown

Reinvesting FTSE 100 dividends

To take another example, over the last forty years to 2025, the FTSE 100 has made a capital return of 391%. This is equal to 205% in real terms – meaning after inflation – as the UK consumer price index inflation rose 186% over this period, by Evelyn Partners’ calculations.

But with UK dividends reinvested the total return is a far more impressive 1,926%.

Hollands said: “While it can be nice to see ad hoc dividend income appear in your bank account, if you don’t need the income now, it is far better to opt for a dividend reinvestment scheme.

“Or, if you are a fund investor, to choose ‘accumulation’ shares classes where any income from the fund portfolio is automatically rolled up rather than distributed.”

Tom Stevenson, investment director at Fidelity International, said a myth has built up that the FTSE 100 has been a serial underperformer: “And when you look only at the headline index level, it’s not hard to see why.”

The UK’s blue-chip index peaked at 6,930 right at the end of the last century, literally on New Year’s Eve 1999. It didn’t get back to that level until February 2015 and then took another nine years to finally make it to 8,000. It’s been a long hard slog.

“But when you factor in the relatively high dividend yield on UK shares, often above 4%, the total return from UK shares starts to look a great deal more interesting,” he pointed out.

Reinvesting dividends meant that the FTSE 100 got back to its 1999 high much more quickly – by February 2006 rather than February 2015. Today the total return index stands more than three times higher than at the peak of the dot.com bubble, said Stevenson.

Missing out on dividend reinvesting

Millions of investors could be missing out on thousands of pounds each, however, by failing to reinvest their dividends, according to Aberdeen Asset Management dividend research.

According to Aberdeen’s findings, 42% of UK investors either said ‘no’ or ‘don’t know’ when asked if they are reinvesting their dividends – equal to 7.5 million investors in the UK.

Analysis by Aberdeen looked at nine major markets over a ten-year period to the end of February 2025 and the impact of reinvesting dividends on returns if an investor had started with a £10,000 lump sum investment.

The biggest difference between total return (reinvesting dividends) versus capital return (not reinvesting dividends) was seen in the Dow Jones Index. It delivered £37,016 on a total return basis over 10 years. This compares to £29,651 on a capital return basis – a difference of £7,365 over 10 years.

Some may be surprised to see the Dow Jones Index lead here given the US is not typically associated with dividends. But that just shows the power of the compounding effect and its impact on the higher total return on the index’s performance.

Because while the S&P 500 delivered the largest total return on £10,00 invested over 10 years – at £41,485 versus £34,699 on a capital return basis – the difference between capital and total return was smaller at £6,786.

The FTSE World Index came third, at £32,002 returns on a total return basis compared to £25,439 on a capital return basis; a difference of £6,563.

The difference was most stark when looking at the AIM market. AIM only delivered positive returns after 10 years, and that was only on a total return basis i.e. when dividends were reinvested, returning £11,335 versus £9,851 when dividends weren’t reinvested.

Interestingly, the FTSE100, often famed for its dividends, came in at number five in Aberdeen’s analysis. Over 10 years it provided a total return of £18,548 versus £12,682 on a capital return basis; a difference of £ 5,866.

Ben Ritchie, head of developed market equities at Aberdeen, said: “Reinvesting dividends is key to long-term returns. While the impact has been seen over the past three and five years, it’s not until ten years that the true magic of compounding really kicks in and delivers, assuming that markets are moving in the right direction – upwards.

“Many income investors rely on their regular dividends to meet their outgoings. But it is compound interest that helps get portfolios to sufficient scale so they can reap the income rewards later on.”

Index10 year capital return10 year total return (Dividends Reinvested)£ difference over 10 years (amount made from total return versus capital return)
Dow Jones29,65137,0167,365
S&P 50034,69941,4856,786
FTSE World25,43932,0026,563
MSCI Europe15,95422,0376,083
FTSE 10012,68218,5485,866
MSCI Emerging Markets13,58817,9484,360
FTSE 250 including investment trusts11,76715,4463,679
FTSE 250 excluding investment trusts11,25414,8063,552
AIM9,85111,3351,484

Source: Bloomberg, 28 February 2025

Picking dividend winners

As well as the powerful effect of dividend reinvestment, it is worth looking out for reliable, consistently dividend paying companies for another reason.

“A company that is able to pay a sustainable and growing dividend that is amply covered by its earnings per share can be regarded as shareholder friendly and able to generate healthy cash flows,” said Hollands.

However, some caution is also required, especially where the level of dividend yield appears “too-good-to-be true”.

“When buying shares with high dividend yields, it is important not to get dazzled by the highest headline yields without digging deeper into how well supported those payouts are by the underlying profits,” Hollands said.

Targeting higher yielding stocks can be a bit of a trap, as a very high yield can be an indication that the market does not believe the dividend payout rate is sustainable and the outlook for the business is poor, so a low share price creates the effect of a high yield.

It is much better to find companies that have the potential to grow their dividends over time, because the underlying business is performing well.

“It’s also worth pointing out that recently many companies have now adopted share buybacks alongside dividends, which can help enhance shareholder returns, so these might be considered alongside dividends,” Hollands said.

The SNOWBALL invests mainly in Investment Trusts because most have built up reserves, to pay their dividends in times of market stress.

Some Investment Trusts pay an enhanced dividend, commonly 6% of NAV form income and capital. These dividends can then be re-invested into the higher part of your Snowball as the underlying shares continue to grow, in time, in value.

The tale of the Dog and the tail

The recognised financial advise is to concentrate on the body and leave the tail to luck. Don’t buy anything unless you are prepared to hold for a minimum of 5 years is the mantra.

Good news for those charging for the advice, no complaints for at least 5 years.

When you want to take income from your portfolio, one piece of advice is to buy an annuity.

Canada Life figures show the 65-year-old with a £100,000 pension pot could buy an annuity linked to the retail price index (RPI) that would generate a starting annual income of £3,896. That’s up from £2,195 in the New Year following a 77% spike in rates this year.
Oct 22

A huge gamble with your future as the rate could be as above or higher but you have to surrender all your capital so Hobson’s choice.

The next option is to use the 4% rule, you can DYOR using the search button above.

Some people will not trade a dividend re-investment plan as they only concentrate on growing their capital.

If you trade a Snowball, as you never intend to sell any shares as you need the income to live on, the capital figure is of no importance.

A dividend investment plan is the only plan that you write down the yearly outcome and thus a total amount of income you will have when your retire.

You need to major on a ‘secure’ dividend, although no dividend is 100% secure, some dividends are more secure than others.

For those who near to their retirement date may prefer to

move their Snowball to less risky dividends, if they have achieved their plan.

If you have longer to retire you still need some ‘secure’ dividends as a bed rock for your Snowball but could include more higher yielding Investment Trusts and ETF’s. All still subject to the rules for the SNOWBALL

« Older posts Newer posts »

© 2026 Passive Income Live

Theme by Anders Noren — Up ↑