SEIT Part Seven – From Triumph to Earn This
The Final instalment brings together the holdings
Oct 19, 2026
Dear reader,
Six investigations. Six very different investments. And rather a lot of numbers.
We’ve examined Primary Energy, Oliva, RED-Rochester, Odds ’n’ Sods, Driva and Onyx. Can we feel triumphant?
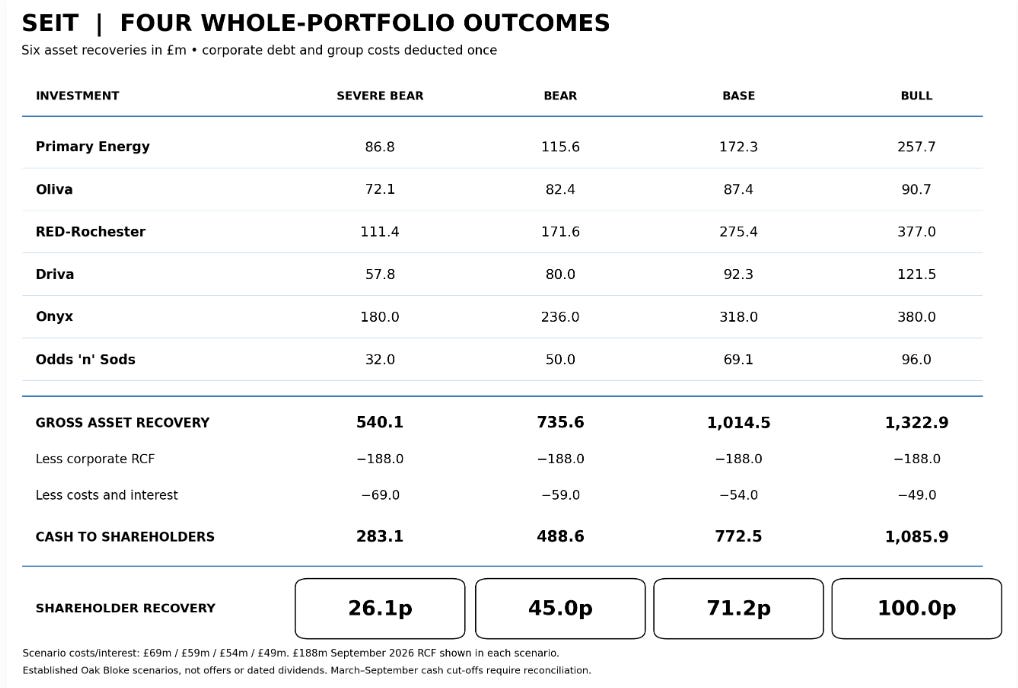
“DGI9, DGI9!” chant Detractors. And a six-times Severe Bear recovers just 26.1p per share. But that’s six investments going severely badly. What happens if some disappoint while others still deliver?
At the same 33p when I starting writing this series, SEIT’s share price trades approximately 58% below its March 2026 NAV of 77.8p. Is that pessimism justified, or is the market treating six very different investments as one collective and simultaneous set of disasters?
This final instalment reconciles all six investigations and tackles the question shareholders really care about: how much cash can we recover — and when?
Let the reckoning begin.
1. What we’ve discovered
The first thing worth recognising is that these aren’t six versions of the same investment.
Primary and Driva could provide early liquidity. Oliva generates cash while awaiting disposal. RED and Onyx may reward patience, while the Odds ’n’ Sods call for more opportunistic realisations.
Each has its own risks, valuation drivers and potential buyers.
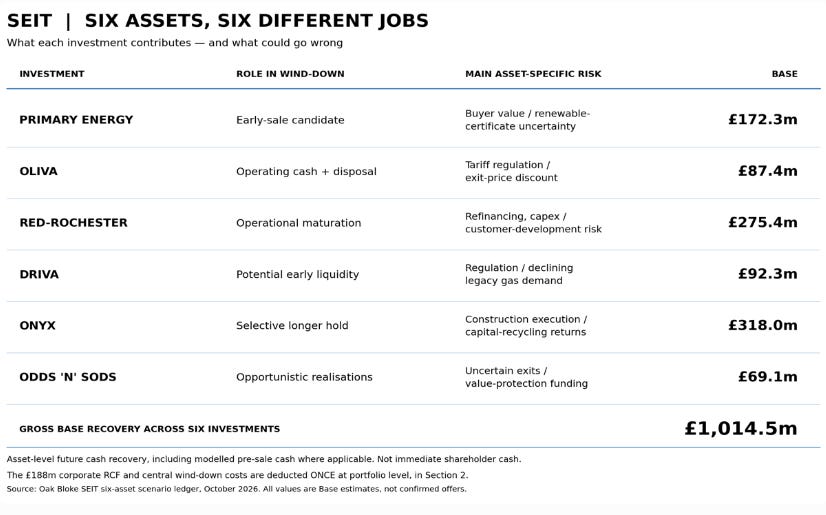
A regulatory setback in Sweden doesn’t necessarily damage US solar installations or an industrial energy system in Rochester, NY.
But neither are these investments completely independent. They share exposure to financing conditions, buyer appetite and SEIT’s corporate borrowing.
Six different investments. Six different outcomes. One shared balance sheet.
The logic of assuming all six simultaneously suffer Severe Bear outcomes may be an unnecessarily pessimistic starting point.
2. From assets to shareholders
My six Base Case asset recoveries total £1,014.5m. But that’s not what shareholders receive.
SEIT must repay its £188m corporate revolving credit facility (RCF), alongside an estimated £44m of remaining central and wind-down costs and £10m of financing interest.
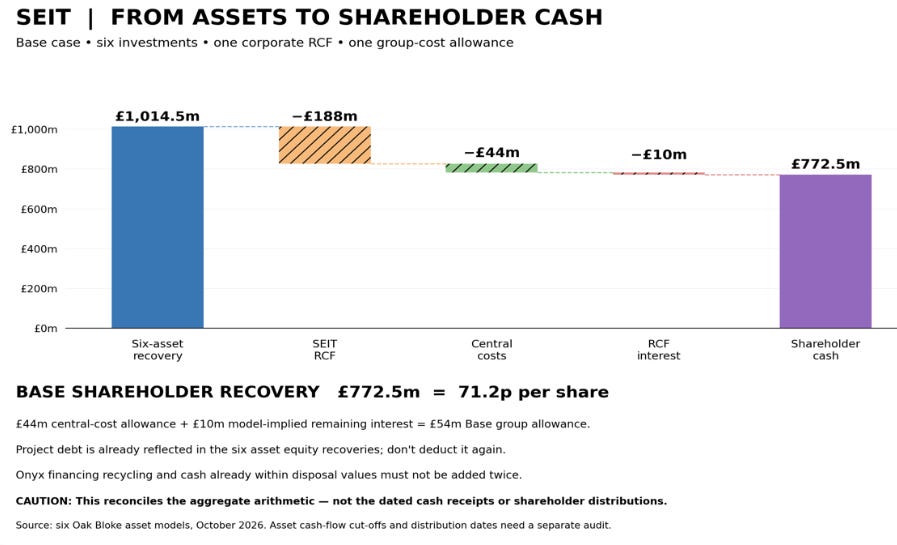
That leaves £772.5m, or 71.2p per share, in my Base Case.
Importantly, project-level debt is already reflected in our asset recovery estimates. Nor can we count Onyx’s recycled cash twice or deduct the notional RCF allocations used in earlier articles again.
These are estimates of eventual recovery, not promised distributions. The timing of receipts, debt repayment and shareholder returns remains crucial.
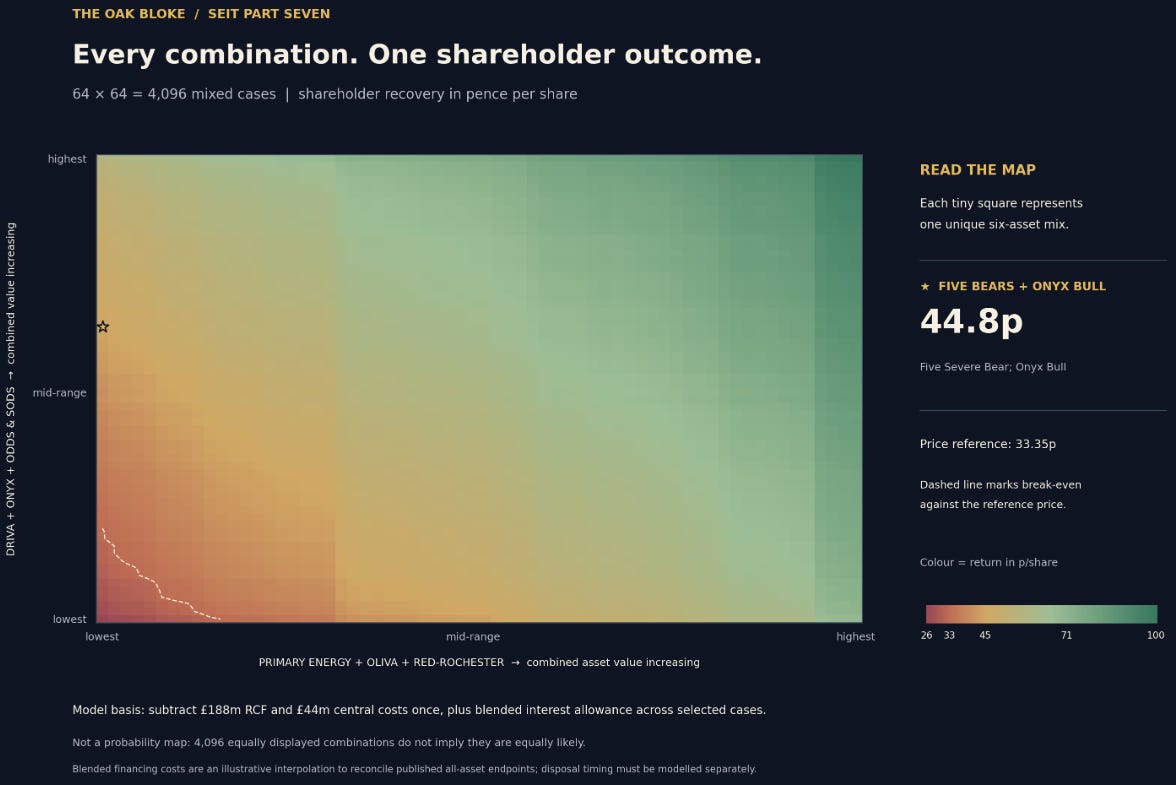
3. The Severe Bear, Bear, Base and Bull – 4096 outcomes – one picture
For the six articles covering the six assets, each with 4 scenarios I pondered how to represent this with a picture. The difficulty is there are 4 scenarios × 4 scenarios × 4 scenarios × 4 scenarios × 4 scenarios × 4 scenarios = 4096 outcomes.
Pie Chart? Waterfall? 4096 graphics and a Veeeeeeeeeeeery long article? Or just some illustrations?
And that’s why I love the following chart.
The dotted line represents SEIT’s share price of 33p. The outcomes range from 26.1p when everything suffers Severe Bear to 100p when everything delivers Bull.
What fascinates me is how many combinations still produce a nominal recovery in excess of 33p.
That’s not proof the odds favour shareholders. These 4096 scenarios aren’t equally likely. But it does show how much can go wrong without necessarily destroying the investment case.
4. How much can you Bear?
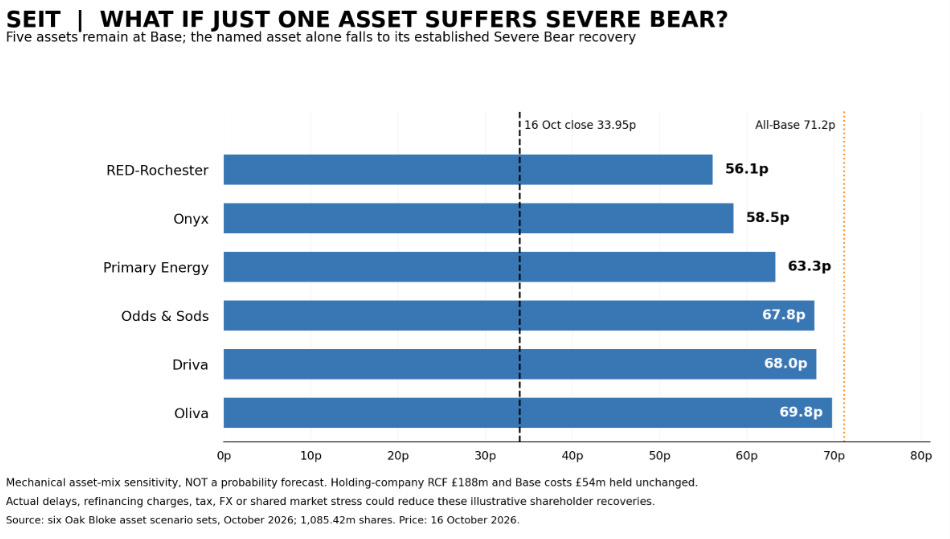
Interestingly a severe bear at one asset and a Base case for the rest yielded an interesting result.
RED is the biggest individual threat: its Severe Bear, with the other five investments at Base, reduces recovery to approximately 56.1p/share.
Even that remains comfortably above the 33p share price.
One asset having a disaster doesn’t necessarily mean SEIT shareholders do.
What is also apparent is that Oliva, Driva or Odds/Sods could have a disaster instead and it doesn’t really matter. A poor outcome at those still delivers huge upside overall.
5. Sacrificing assets in Saving Private Onyx
My “strategy” set out over six articles to grow Onyx while shielding it and focusing on realisations from Primary, then Oliva, Odds’n’Sods, then Red and Driva is deliberate.
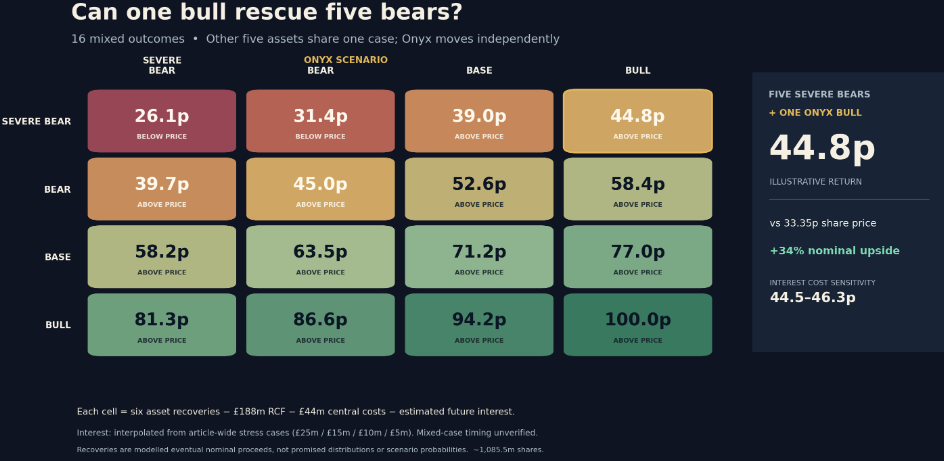
Severe Bear at all other fivc assets even potentially via sacrificial disposal pricing, and a Bull Case for Onyx yields 44.5p.
In other words the key question for Onyx is do you “EARN THIS”.
Perhaps in 2030 in a metaphorical visit to a cemetery Onyx will say to its fallen co-assets:
“I hope that was enough. I hope that, at least in your eyes, I’ve earned what all of you have done for me.”
It then turns to its shareholders and asks:
“Tell me I’ve led a good life. Tell me I’m a good asset.”
They reply (satisfied with a 44.8p per share capital return outcome despite the disaster and carnage and row of white war graves at all of the other five):
“You are.”
6. Why the Base is below reported NAV
SEIT’s March 2026 NAV was 77.8p/share, against my modelled Base recovery of 71.2p.
NAV estimates the present value of future investment cash flows. My model estimates eventual shareholder recoveries after asset disposals, financing and wind-down costs.
NAV is just an estimate. Actual capital recovered and returned to shareholders is the modelled Base Case where assets take bullets – and the NAV doesn’t escape unscathed.
7. Pinned down by a £188m DCF problem
SEIT’s biggest near-term challenge is its £188m corporate RCF, with interest and administration costs accumulating while assets await disposal.
Like a MG42 Machine Gun pinning down the SEIT assets for now.
Three investments could provide substantial liquidity:
- Primary Energy: £172.3m Base recovery.
- Driva: £92.3m Base recovery.
- Oliva: £87.4m Base recovery.
As the graphic shows, Primary combined with either Driva or Oliva could extinguish the RCF. Driva and Oliva together would fall just £8.3m short.
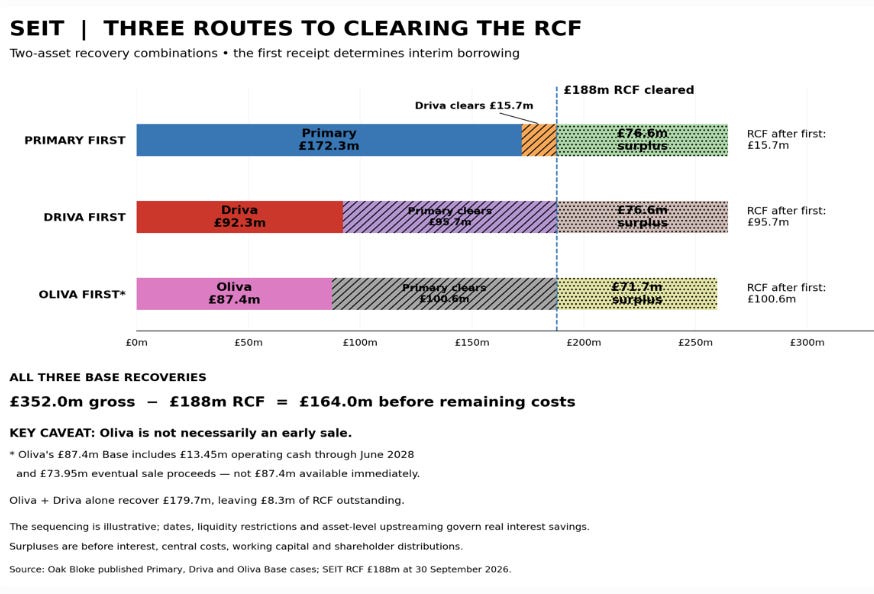
All three could recover £352m, leaving £164m after RCF repayment, before remaining costs.
But timing matters. Oliva’s recovery includes operating cash through June 2028 and eventual disposal proceeds. The Oliva-first route is therefore illustrative rather than an assumed disposal timetable.
SEIT doesn’t necessarily need to sell all three to clear its borrowing. It needs sufficient proceeds, soon enough to stop the interest clock.
But that’s also the dilemma: Sell early to stop the financial bleeding, even if that involves some financial bleeding, or wait for a better price while the costs accumulate?
8. Should SEIT sell everything quickly?
No.
Nor should it simply retain every asset in pursuit of the highest possible theoretical NAV. The correct strategy is selective.
A reasonably priced early disposal can remove borrowing pressure and allow the other assets to be sold more patiently. Forcing RED or Onyx into a premature sale could destroy substantially more value than would be saved in holding-company interest.
The preferred approach remains:
Sell suitable mature assets first. Repay the RCF. Allow the more complicated investments enough time to demonstrate the value for which buyers will actually pay. Return surplus capital as soon as practicable.
Primary and Driva are logical early candidates, subject to achievable bids.
Oliva provides cash generation and an alternative source of disposal proceeds.
RED deserves time for its operational improvements, subject to refinancing discipline.
Onyx is the principal candidate for selective maturation — provided the additional value exceeds the capital, financing and execution risk required to achieve it.
The Odds & Sods should be realised opportunistically, with limited value-protecting expenditure rather than indiscriminate investment.
The object is not to maximise the last pound of aggregate proceeds while keeping shareholders waiting indefinitely.
It is to maximise the value of the cash returned, taking account of time.
9. Time — the missing dimension in NAV
There’s an enormous difference between receiving 71.2p in 2028 and receiving 71.2p in 2030.
The nominal recovery is identical. The XIRR annualised investment return isn’t.
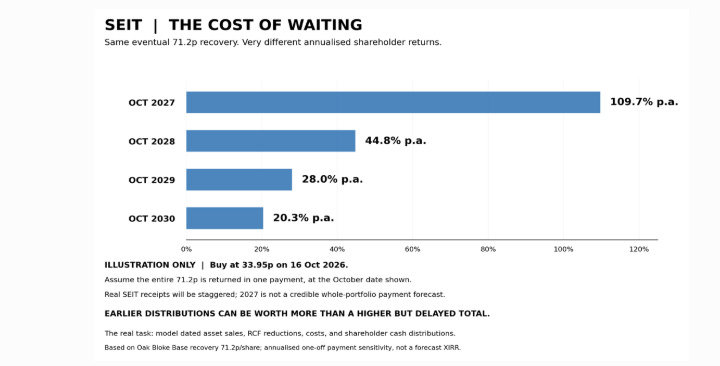
Our Base estimates 71.2p of eventual shareholder recovery, but not when each distribution arrives.
Selling Primary, Driva or Oliva could reduce borrowing and bring distributions forward. Retaining RED or Onyx might generate additional value — but only if that improvement compensates shareholders for waiting.
That’s why the next disposal matters so much. It doesn’t just establish a valuation; it can change the timing of every subsequent shareholder return.
The objective isn’t to maximise the last penny recovered. It’s to maximise the time-value of the pennies shareholders actually receive.
10. The Detractor’s Flagellation
“DGI9! DGI9!” chants the Detractor. Trotting out the same, tired old line.
The Detractor can still hope for 26.1p. That would be more than a 20% write down from today’s share price and let’s not forget the Oak Bloke 25 for 25 is on the hook for 40p not 33p, remember.
The detractor can point to substantial write-downs, SEIT’s consumption of considerable capital and disappointed shareholders.
Buyers might demand bigger discounts than I’ve modelled. Refinancing could become expensive. Onyx might need more capital, while RED takes longer to mature.
And six different investments aren’t immune to a common enemy: a miserable market for infrastructure disposals.
4,096 possible combinations don’t make the favourable ones inevitable.
But the Detractor’s argument has a weakness.
Primary, Oliva, RED, Driva and Onyx aren’t imaginary businesses. They own operating infrastructure, with customers, contracts and cash-generating assets. My calculations suggest that even some decidedly unpleasant combinations could produce positive shareholder recoveries.
The Detractor’s strongest argument isn’t that everything is worthless. It’s that SEIT might fail to turn that value into cash before time, interest and costs devour too much of it.
And there’s only one way to settle that argument: Show us the money.
11. Conclusion — Earn This
Six investigations. Six very different investments. And 4,096 possible combinations of outcomes.
My Base Case suggests £772.5m, or 71.2p per share, after SEIT’s borrowing and estimated wind-down costs. Against a 33p share price that’s an attractive proposition.
SEIT doesn’t need all six investments to succeed.
Even five Severe Bears alongside an Onyx Bull produce a modelled recovery of approximately 44.5p/share. That’s not a guarantee, nor necessarily an attractive annualised return if shareholders must wait until 2030.
And the six investments aren’t completely independent. A difficult market for infrastructure disposals could hurt them all. The strategy therefore isn’t to sacrifice good assets cheaply in needless sacrifice in the hope that Onyx saves the day.
Realising assets intelligently, extinguishing the £188m RCF and give certain investments capable of earning a better return sufficient time to do so.
Price matters. Timing matters. But Cash returned matters most.
The Detractors can chant “DGI9” until they’re Pooh in the face.
SEIT’s next disposal will tell us considerably more than the next NAV announcement. Considerably more than a repeating chant.
Six articles have examined what SEIT’s investments might be worth. This seventh article attempted to illustrate how much can go wrong and the outcome is a net gain.
SEIT’s management have the task to turn those valuations into actual shareholder returns.
Regards
The Oak Bloke.
Disclaimers:
This content is for educational and informational purposes only. It does not consider your personal circumstances and is not financial, investment, tax, legal, or professional advice. Nothing here is a recommendation, offer, or solicitation to buy, sell, or hold any investment. Investing involves risk, including
Leave a Reply